


Why Did Mondelez International (MDLZ) Move Today?
Mondelez International (MDLZ) has been busy in the snack aisle, rolling out CHIPS AHOY! Minis Drizzled cookies and RITZ Gluten Free Crackers. These moves widen its reach across indulgent and gluten free snacking.
These launches land as Mondelez International’s share price trades at US$63.80, with the stock up 5.9% on a 30 day share price return and 18.9% year to date. The 1 year total shareholder return of 8.7% suggests steadier progress over a longer stretch.
Scan how Mondelez International compares with other snack and beverage players by reviewing a curated set of 21 high quality undiscovered gems with strong fundamentals that are not yet widely followed.
Mondelez International keeps extending its snacking reach, yet the share price already reflects steady returns. Are investors paying a fair price for that strength, or has the recent enthusiasm moved the valuation ahead of itself?
Most Popular Narrative: 8% Undervalued
Against the last close at $63.80, the most widely followed narrative points to a fair value of about $69.13 for Mondelez International, which frames the current price as leaving some upside if the thesis plays out.
The company is continuing to reinvest upside into brands, emerging markets and distribution, with raised 2026 organic net revenue guidance to at least 2% and maintained EPS guidance alongside double digit advertising and consumer spending. This points to an ongoing effort to build future revenue and earnings rather than maximize short term profit.
See why 102 investors see Mondelez International as 8% undervalued.
Result: Fair Value of $69.13 (UNDERVALUED)
Still, the Mondelez International story can be knocked off course if cocoa markets tighten again or if North American demand softens while reinvestment stays high.
Find out about the key risks to this Mondelez International narrative.
Another View: Mondelez International On Earnings Ratios
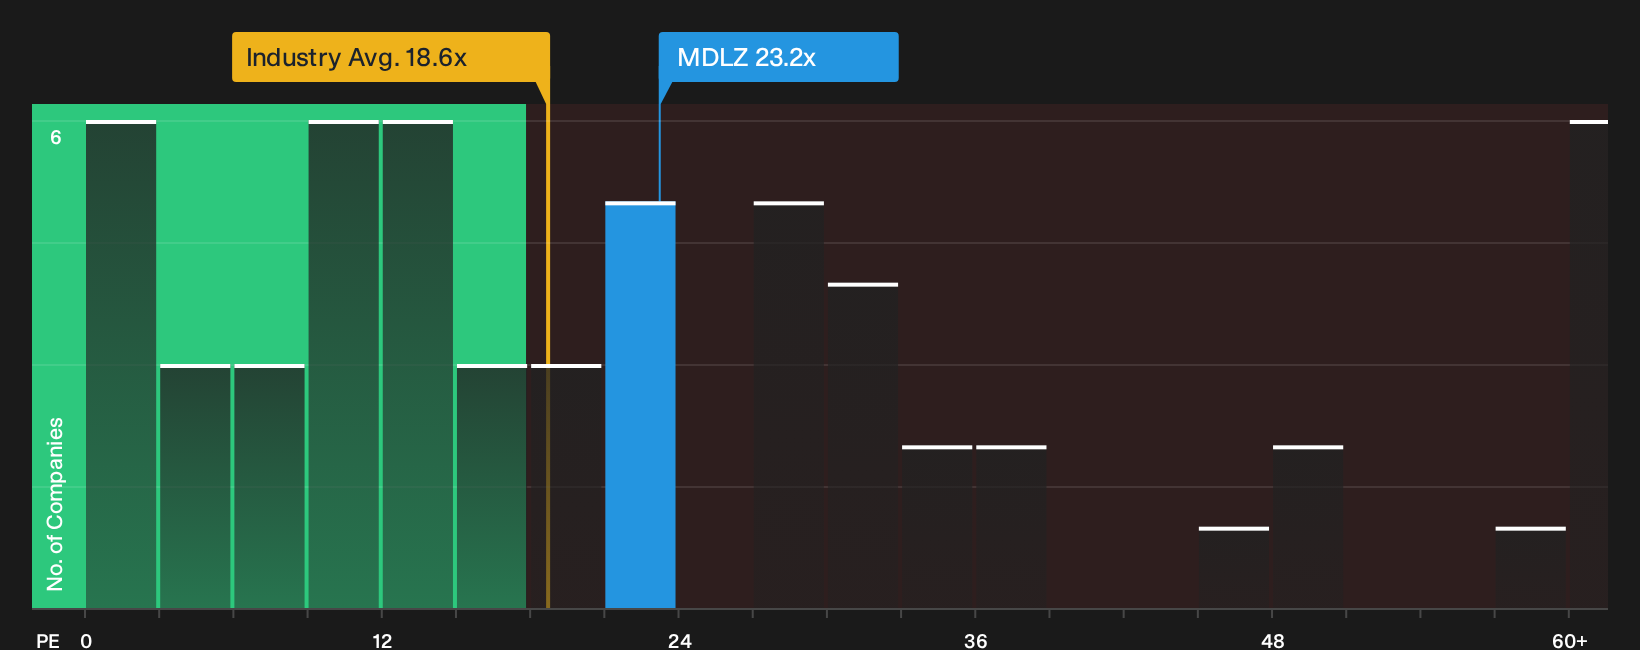
The first story presents Mondelez International as undervalued against a fair value of $69.13. On simple earnings ratios, the picture looks less generous. The current P/E of 23.2x is higher than the US Food industry at 18.6x and above a fair ratio estimate of 21.4x, which points to less room for error if growth disappoints.
For investors weighing this, the question becomes whether Mondelez International’s brands and reinvestment justify paying more than both the sector and that fair ratio, or whether patience might offer a better entry point when expectations cool. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Mondelez International’s valuation and risk profile. If that feels unresolved, act quickly and review the data yourself, starting with 3 key rewards and 1 important warning sign
Ready to find more ideas beyond Mondelez International?
Do not stop with a single stock. Broaden your watchlist with a few focused screens that surface different types of opportunities other investors may be missing.
- Target resilient compounding potential by scanning 29 high quality undervalued stocks that combine solid fundamentals with prices that still look reasonable.
- Prioritise stability and sleep better at night by checking a 30 resilient stocks with low risk scores that filters for companies with stronger risk profiles.
- Hunt for future standouts early by reviewing a 7 elite penny stocks with strong financials that highlights smaller businesses with healthier financials than their size suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com