


Westamerica Bancorporation (WABC) Q3 Earnings And Buybacks Put Valuation Back In Focus
Westamerica Bancorporation (WABC) has put fresh numbers and capital actions in front of investors, pairing third quarter earnings with an updated share repurchase tally and a reaffirmed quarterly dividend.
At a share price of $61.38, Westamerica Bancorporation has seen its 1-year total shareholder return reach 31.44%, backed by a 28.33% year to date share price gain. This suggests momentum has been building as buybacks, steady earnings and the reaffirmed dividend shape how investors weigh growth potential against risk.
Scan how Westamerica Bancorporation compares with other banks that have strong balance sheets and earnings resilience using our hand-picked list of solid balance sheet and fundamentals (24 results) in the same sector.
After a 31.44% 1 year total return, Westamerica Bancorporation sits at a more demanding entry point. Does that recent climb justify paying up now, or does patience around valuation make more sense?
Price-to-Earnings of 12.8x: Is it justified?
Valuation on Westamerica Bancorporation today hinges on what investors are willing to pay for each dollar of profit. At a P/E of 12.8x with a $61.38 share price, the market is putting a clear tag on that earnings stream.
The P/E ratio measures how much you pay for $1 of earnings, which is especially closely watched for banks where profit and balance sheet quality matter more than fast revenue expansion. For WABC, five year earnings growth of 3.3% per year and what are assessed as high quality earnings give some context for why investors might accept paying a multiple in the low teens.
Compared with a peer average P/E of 22.9x, the stock trades on a materially lower earnings multiple, suggesting investors are not assigning the same premium as they are to the broader peer group. At the same time, the P/E of 12.8x sits above both the US Banks industry average of 11.6x and an estimated fair P/E of 10.2x. This points to a valuation level that the market could eventually lean back toward if sentiment cools.
Explore the SWS fair ratio for Westamerica Bancorporation.
Result: Price-to-Earnings of 12.8x (OVERVALUED)
Still, richer expectations can crack if Westamerica Bancorporation faces credit quality pressure, or if lending demand softens and challenges the current earnings profile.
Find out about the key risks to this Westamerica Bancorporation narrative.
Another View: What The SWS DCF Model Says
The P/E ratio presents Westamerica Bancorporation as slightly expensive, yet the SWS DCF model points in the opposite direction. With the shares at $61.38 and the model estimating future cash flow value at $110.25, this framework instead suggests that the stock may be undervalued. Which lens do you place more weight on when profit multiples and cash flow calculations differ?
Look into how the SWS DCF model arrives at its fair value.
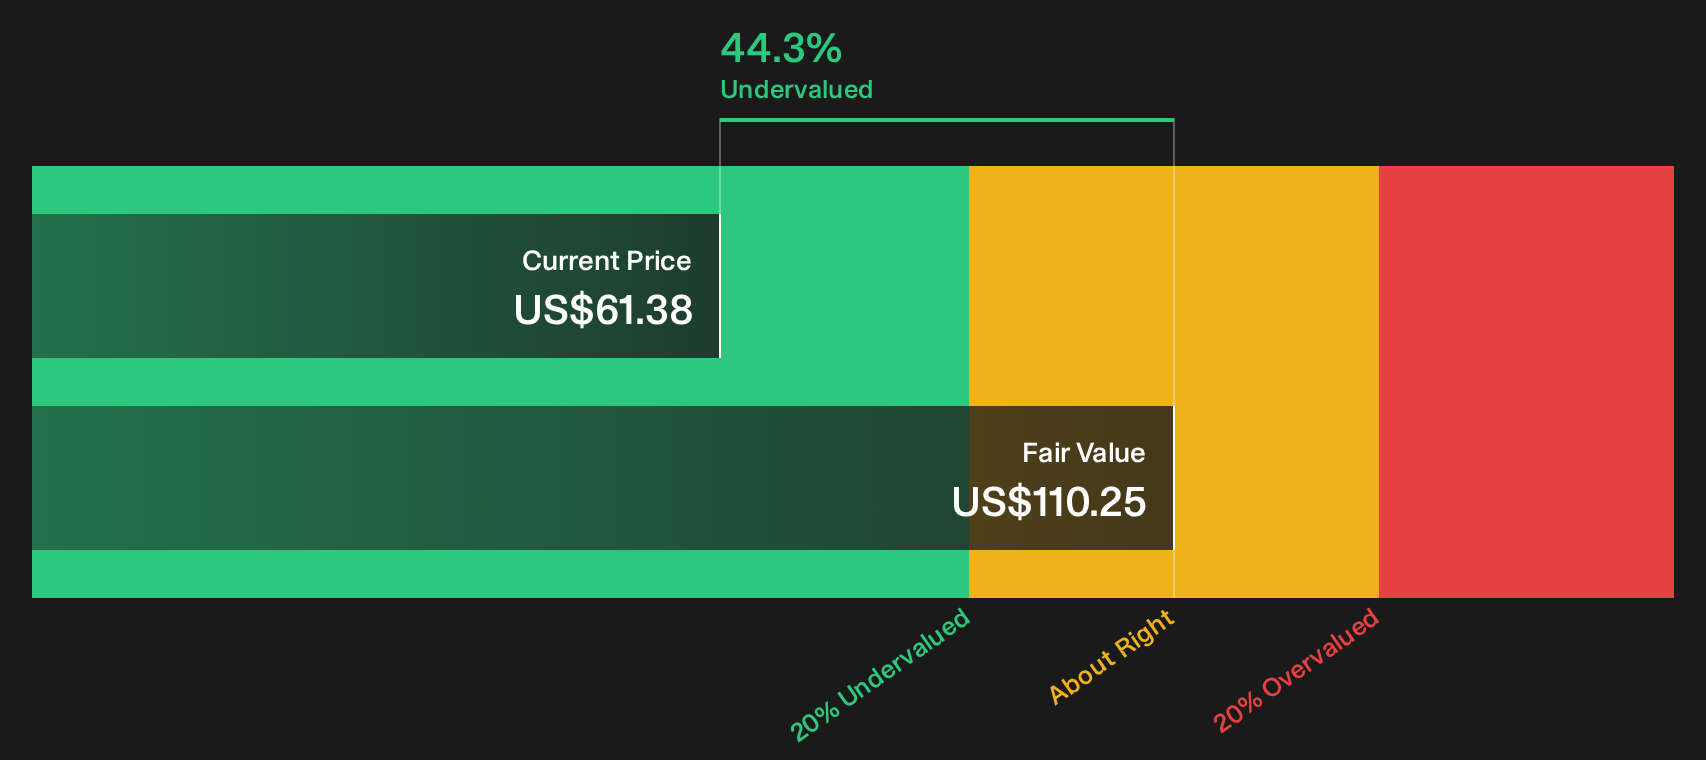
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westamerica Bancorporation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the richer P/E and the DCF signal on Westamerica Bancorporation today is normal, so move fast on your own homework and pressure test both sides of the argument using the 2 key rewards
Looking for more investment ideas beyond Westamerica Bancorporation?
If you stop at Westamerica Bancorporation, you risk missing other opportunities that fit your goals just as well, or possibly even better.
- Target resilience by scanning companies with stronger balance sheets and fundamentals using our focused list of solid balance sheet and fundamentals (24 results).
- Hunt for value in stocks where quality and pricing both look appealing by reviewing the hand picked 29 high quality undervalued stocks.
- Prioritise stability and defensive characteristics by checking out a curated 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com