


Metso Oyj (HLSE:METSO) Q3 Orders Strengthen The Case For Its Valuation
Metso Oyj (HLSE:METSO) just paired a fresh Q3 earnings update with a leadership shift in its key Aggregates segment, giving investors new data on both operations and management direction.
Recent trading tells a mixed story for Metso Oyj, with a 1-day share price return of 2.12% and a year-to-date share price return of 8.86%. At the same time, the 1-year total shareholder return of 22.60% and the 3-year total shareholder return of about 12x suggest that longer term momentum has been much stronger than the past month’s weaker 30-day share price return of 3.92%, as investors weigh the Q3 earnings, order intake and leadership change against earlier gains.
Spot opportunities similar to Metso Oyj's order-driven story by scanning our hand-picked 612 high quality undiscovered gems with strong fundamentals that the wider market may still be overlooking.Metso Oyj now trades at €16.41 while analyst targets cluster closer to €18.34 and intrinsic value work points to an even larger gap. Is that spread mispricing, or is it a fair cushion for execution risk?
Most Popular Narrative: 9% Undervalued
Metso Oyj’s most followed narrative pegs fair value at €18.10, compared with the current €16.41 share price. This leaves a modest valuation gap that depends on services growth, technology heavy projects, and cash generation remaining resilient.
Strong and rising order intake in Minerals services, with aftermarket now representing 68% of segment sales and contributing to higher gross and adjusted EBITA margins in Q2 2026, indicates faster growth and margin expansion potential for recurring service revenues versus capital equipment and supports earnings quality.
See why 20 investors see Metso Oyj as 9% undervalued.
Result: Fair Value of €18.10 (UNDERVALUED)
Still, softer aggregates demand in Europe and higher logistics and energy costs could squeeze Metso Oyj’s margins and weaken the services-led valuation case.
Find out about the key risks to this Metso Oyj narrative.
Another View: What Metso Oyj’s P/E Is Telling You
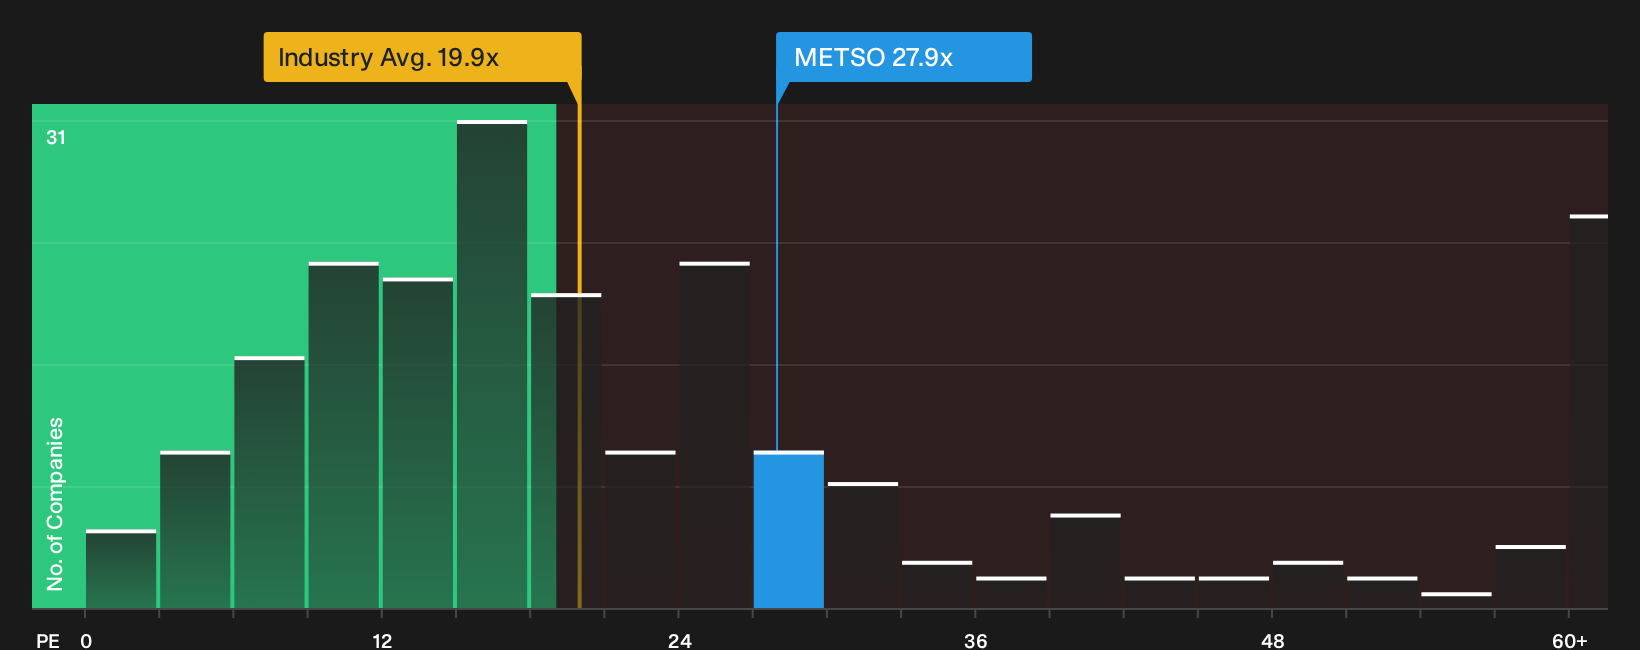
On earnings multiples, Metso Oyj looks expensive at a P/E of 27.9x compared with 19.9x for the wider European Machinery group and 21.8x for peers. Yet the fair ratio sits higher at 31.6x. That gap suggests investors are already paying up, but not for the full earnings profile. How comfortable are you with that middle ground on valuation risk?
To stress test that viewpoint against the underlying numbers, take a closer look at how the current price, peer comparison and fair ratio line up in our valuation breakdown. Then decide whether this premium feels justified for your own portfolio using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Unsure whether the Metso Oyj story is as optimistic as it sounds or still too finely balanced. Act while the data is fresh by reviewing the 3 key rewards
Looking for more investment ideas beyond Metso Oyj?
If Metso Oyj has sharpened your appetite for fresh ideas, do not stop here. Broaden your opportunity set now and give yourself more options.
- Target quality at a discount by scanning our hand picked 194 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (207 results) so your next pick starts from a position of financial strength.
- Reduce unpleasant surprises by focusing on 221 resilient stocks with low risk scores that score well on stability, so you are not chasing every headline just to keep up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com