


Descartes Systems Group (TSX:DSG) Wins WEL Companies Deal, Is The Stock Above Fair Value?
Descartes Systems Group (TSX:DSG) is back in focus after WEL Companies adopted its broker transportation management system, integrating it with CARRIER1 Vault to coordinate both in-house trucking and external carrier capacity.
Recent momentum in Descartes Systems Group has been strong, with a 30-day share price return of 18.44% and a 90-day move of 31.01% to CA$131.57. The 1-year total shareholder return has declined 2.5%, and the 3-year total shareholder return is 35.98%.
Scan beyond Descartes Systems Group and evaluate other logistics and software players showing strong momentum with the hand picked 9 high quality undiscovered gems.
For Descartes Systems Group, this kind of price swing can mirror improving business results or it can simply reflect investors crowding back into a popular story. Which side of that line does the current valuation sit on?
Most Popular Narrative: 3% Overvalued
Against a CA$131.57 last close, the most followed narrative for Descartes Systems Group pegs fair value at CA$128.28, suggesting investors are paying a small premium that leans heavily on the long term earnings story.
Ongoing digital transformation and automation initiatives in transportation and supply chain sectors, combined with Descartes' leadership in real-time shipment tracking (MacroPoint) and AI-driven optimization, are enhancing customer stickiness and differentiation, likely supporting net margin expansion and increasing share in flat or declining end-markets.
See why 25 investors see Descartes Systems Group as 3% overvalued.
Result: Fair Value of CA$128.28 (OVERVALUED)
Still, the Descartes Systems Group story could be knocked off course if acquisition driven growth slows, or if global trade rules shift faster than customers can adapt.
Find out about the key risks to this Descartes Systems Group narrative.
Another View: Cash Flows Tell a Different Story
Price tags and narratives both point to Descartes Systems Group as slightly expensive, yet the SWS DCF model lands in a different place. On that framework, CA$131.57 is below an estimated future cash flow value of CA$159.60, which frames the current quote as a discount instead of a premium. It raises a simple question. Are earnings multiples overstating risk, or are cash flow assumptions doing too much heavy lifting?
For readers who want to see the full cash flow build and stress test the inputs themselves, Look into how the SWS DCF model arrives at its fair value..
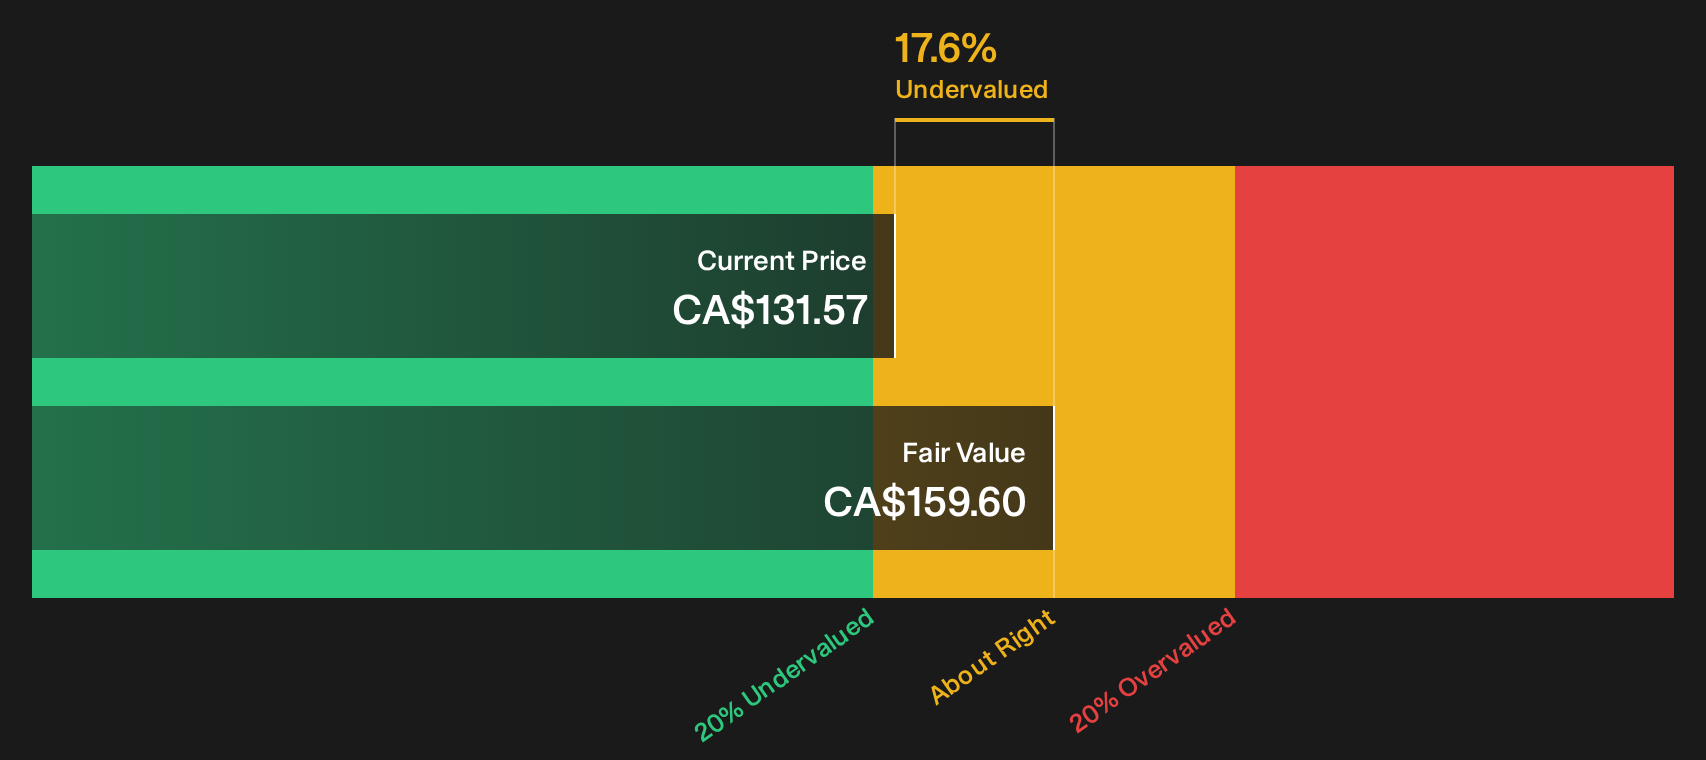
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Descartes Systems Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Descartes Systems Group so far. If you want to move quickly and make up your own mind on the trade off between concerns and upside potential, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Descartes Systems Group?
If you only focus on Descartes Systems Group, you risk missing other setups that fit your style, timeframe, and appetite for risk and resilience.
- Target potential value opportunities before the crowd notices by scanning the 3 high quality undervalued stocks that match your quality and price discipline.
- Build a steadier portfolio backbone by reviewing the list of solid balance sheet and fundamentals (7 results) that pair financial strength with cleaner balance sheets.
- Limit unwanted surprises by filtering for the 8 resilient stocks with low risk scores that align with a calmer, more predictable return profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com