


Camtek (CAMT) Raises Guidance As Its Valuation Story Comes Back Into Focus
Camtek guidance reset puts revenue trajectory in sharper focus
Camtek (NasdaqGM:CAMT) lifted its third quarter revenue outlook to about US$160 million to US$161 million, tied to a projected 27% year-over-year increase and fresh multi period guidance.
Camtek shares have pulled back recently, with a 30 day share price return of down 17.6% and a 90 day share price return of down 20%. Even so, the latest guidance reset highlights stronger demand and keeps long term total shareholder returns, including a roughly 146% three year gain, firmly positive.
Capitalize on Camtek’s guidance momentum by scanning a curated field of semiconductor peers with strong balance sheets and fundamentals using our list of solid balance sheet and fundamentals (24 results).Camtek is guiding to stronger business volumes while the share price has moved the other way. Is this reset mostly about sentiment, or has the recent slide already realigned valuation with the new revenue path?
Most Popular Narrative: 31% Undervalued
Camtek’s most followed narrative pegs fair value at about $176.20, above the recent $121.16 close. This frames the updated guidance against expectations for extended AI driven demand and margin discipline.
The product cycle shift toward Hawk and Eagle G5 systems, which already account for about 50% of systems revenue in Q2 2026 compared with roughly 30% of total revenue in 2025, is tilting Camtek’s mix toward higher priced platforms that management expects to support higher gross margin and operating income.
Rising inspection and metrology intensity in advanced packaging and HBM4, where Camtek is the reference 3D metrology tool for major HBM players and is qualifying for additional 2D and metrology steps, can increase the number of process steps it serves per wafer and supports higher revenue per customer.
See why 34 investors see Camtek as 31% undervalued.
Result: Fair Value of $176.20 (UNDERVALUED)
Still, the Camtek story leans heavily on advanced packaging and AI linked HBM demand, and any reset in sector multiples could quickly test this undervaluation narrative.
Find out about the key risks to this Camtek narrative.
Another View: Camtek pricing sends a different signal
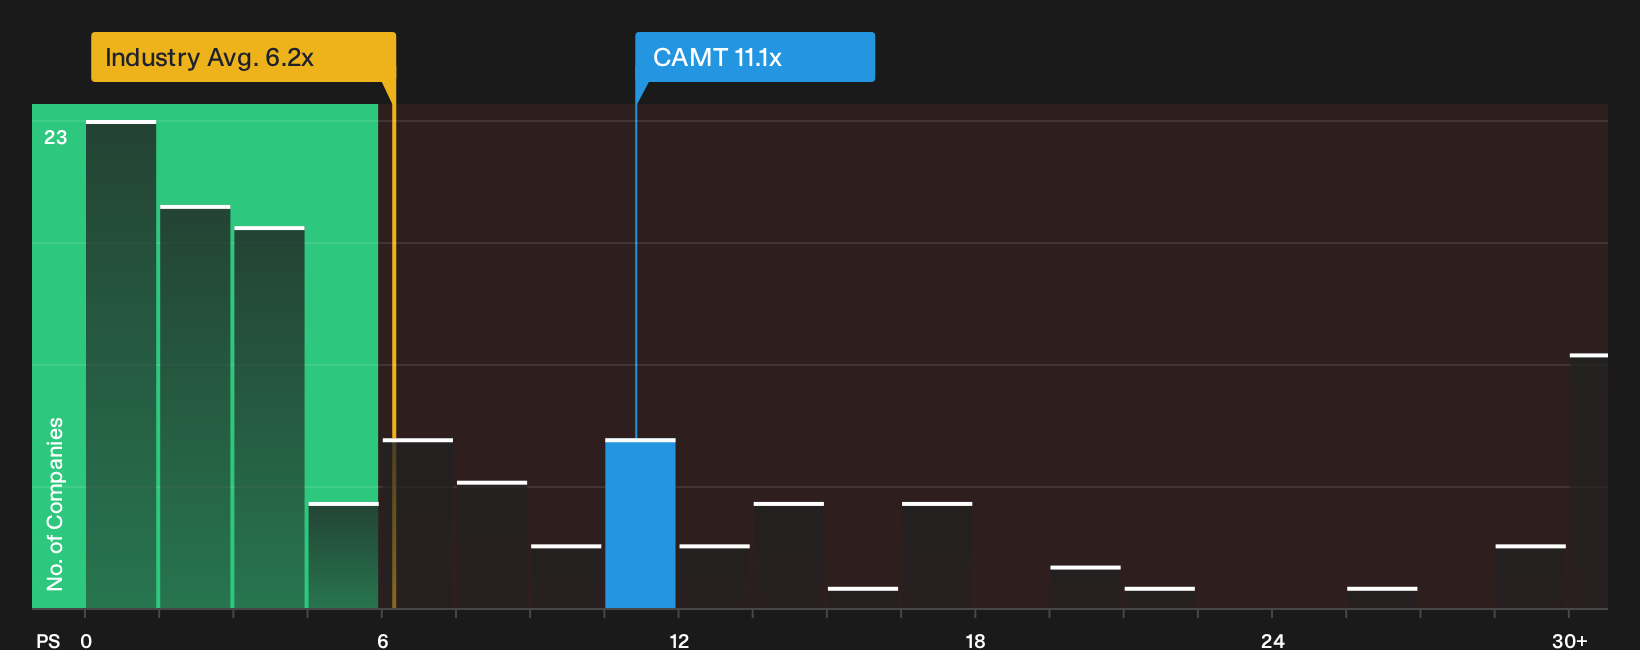
The fair value narrative presents Camtek as undervalued at $176.20, yet the market is already assigning a relatively high P/S of 11.1x. That compares with 7.8x for peers, 6.2x for the broader US Semiconductor group and a fair ratio of 6.1x. This suggests investors are paying for execution rather than buying what appears to be a clear bargain. Which version of value aligns more closely with your view?
To examine this pricing view more closely, it helps to see how the current valuation compares visually with peers and the fair ratio in our valuation breakdown, including the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Camtek can either sharpen conviction or create noise, so move quickly, review the underlying data, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more Camtek-like investment ideas?
If Camtek’s guidance reset has sharpened your focus, do not stop here. Use the next few minutes to scan fresh opportunities that could fit your playbook just as well.
- Target resilient compounding potential by combing through companies with robust cash positions and manageable leverage using the list of solid balance sheet and fundamentals (24 results).
- Hunt for pricing that still looks reasonable relative to fundamentals by reviewing the 29 high quality undervalued stocks before others re-rate them.
- Prioritise calm through market swings by shortlisting candidates from the 30 resilient stocks with low risk scores that aim to limit portfolio shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com