


Crown Castle (CCI) Could Be 10% Undervalued On SpaceX Tower Talks
SpaceX talks put fresh attention on Crown Castle
Reports that SpaceX is in discussions to lease Crown Castle (CCI) towers and potentially become a large tenant have suddenly put the tower owner back on the radar for many investors.
The SpaceX headlines hit just after Crown Castle lifted its full year 2026 net income guidance on 21 October, and that one two punch has helped drive a 26.72% 30 day share price return, even though the year to date share price performance is still down 3.08% and the 1 year total shareholder return has declined 8.22%. The 3 year total shareholder return is up 12.42%, while the 5 year total shareholder return is down 38.91%. This points to short term momentum building after a difficult longer stretch for investors.
Spot emerging momentum across communications infrastructure by scanning the hand picked 55 AI infrastructure stocks that could benefit from rising demand for wireless and data connectivity.Crown Castle has already rerated sharply on the SpaceX headlines and higher 2026 earnings guidance. The real question now is how much of the potential upside is already priced in.
Most Popular Narrative: 9% Undervalued
Crown Castle's most followed narrative puts fair value at $94.82 a share, compared with the latest close at $85.97. This frames the recent SpaceX headlines against an existing tower focused earnings story.
The ongoing growth in U.S. mobile data demand, together with Ericsson projections for usage per smartphone to more than double and management’s expectation that AI applications could roughly triple uplink traffic, supports continued amendments and densification on Crown Castle towers that may add to rental revenue over time.
See why 45 investors see Crown Castle as 9% undervalued.
Result: Fair Value of $94.82 (UNDERVALUED)
Still, Crown Castle faces real pressure from the expected Sprint and DISH churn, and a weaker backdrop for higher margin pre construction services could challenge the bullish tower thesis.
Find out about the key risks to this Crown Castle narrative.
Another View: Crown Castle Through The P/E Lens
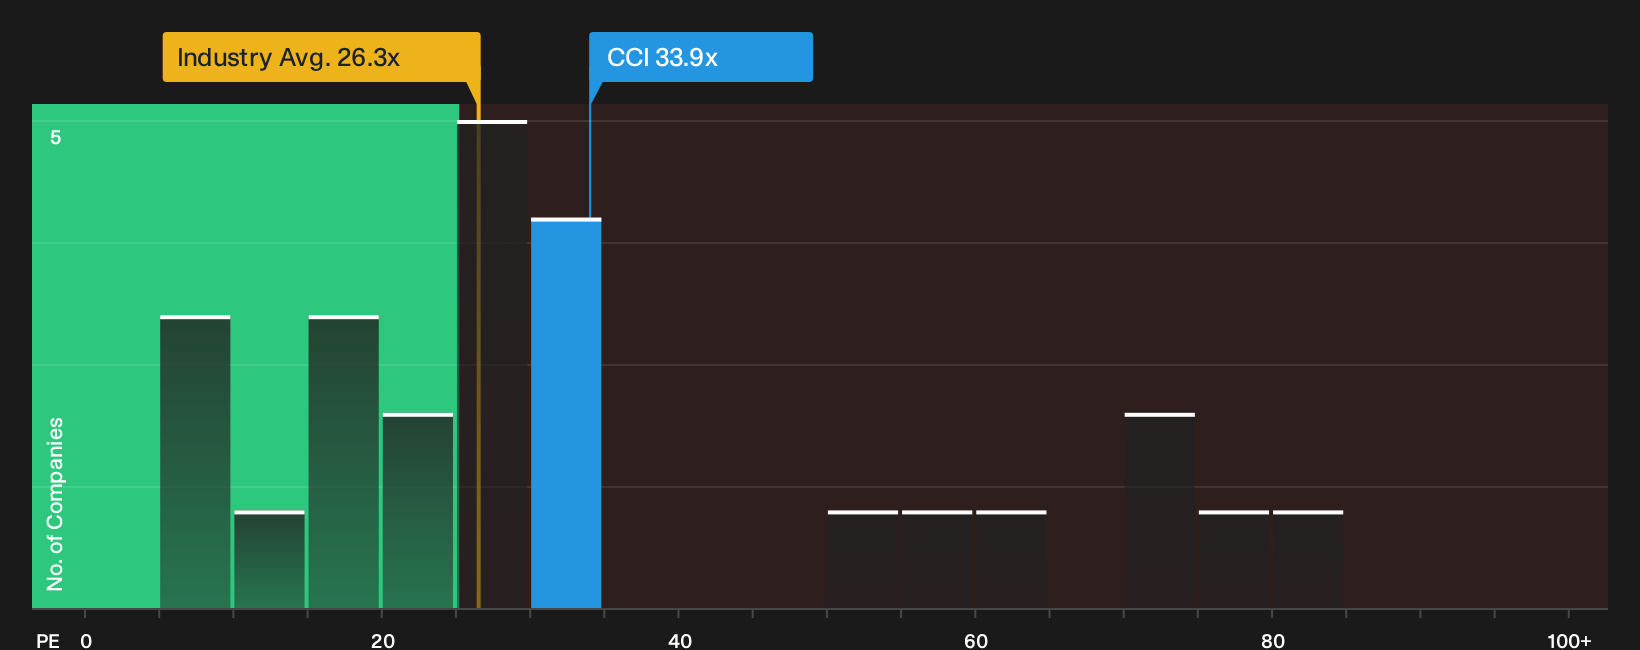
Crown Castle screens differently when the focus shifts from cash flows to its P/E ratio. At 33.9x earnings, the stock trades slightly above the peer average of 33.3x and sits well above the North American Specialized REITs group at 26.3x. The fair ratio sits even higher at 39.5x, which suggests the market could still move either toward a richer multiple or closer to the broader sector, depending on which story investors ultimately trust more.
For a closer look at what the numbers imply for Crown Castle's risk and opportunity profile, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Crown Castle so far. Momentum, new tenant headlines and valuation gaps all point in different directions, so move quickly and weigh both sides by reading through the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Crown Castle?
Do not stop with a single tower REIT. Use the Simply Wall Street Screener to hunt for fresh opportunities that fit your style before the crowd notices.
- Target potential mispricings by scanning our hand picked 29 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that focuses on businesses with lower risk scores and steadier historical profiles.
- Spot resilient payers by checking a curated 5 dividend fortresses built around higher yielding stocks with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com