


Learn Why The Bull Case For Cenovus Energy Stock Could Change Following Earnings Expectations
- Cenovus Energy is preparing to report quarterly results that analysts expect to show significantly higher earnings per share and revenue compared with the prior year, supported by progress on long life oil sands and offshore projects.
- The same forecasts that point to stronger near term profit also describe how Cenovus Energy’s integrated model and project pipeline could influence future cost efficiency, free cash flow generation, and debt reduction plans.
- We will now look at how Cenovus Energy’s investment narrative could be shaped by these earnings expectations and project execution.
Scan how Cenovus Energy’s setup compares with other potential breakouts across our hand picked list of 3 high quality undervalued stocks for your next round of research.
Cenovus Energy Investment Narrative Recap
To own Cenovus Energy, you need to believe its integrated oil sands and refining setup can keep throwing off cash as big projects like Narrows Lake, West White Rose and Foster Creek move from heavy spending into steadier production. The near term story still hinges on converting that build out into lower unit costs and dependable operating performance.
The key short term catalyst is whether upcoming earnings confirm that higher expected EPS and revenue are flowing through to margins and free cash flow, not just headline growth. The biggest near term risk remains rising Canadian policy costs and taxes, which could blunt benefits from project completion if they keep climbing.
The most relevant recent data point is the market expecting Cenovus Energy to post EPS of US$1.21 on US$11.71b of revenue for the September 2026 quarter, with consensus EPS lifted 4.23% in the past month. This focus on stronger quarterly profitability sits directly on top of the long life oil sands buildout and the now lighter maintenance cycle.
If reported results line up with those expectations, investors get a cleaner read on how well Cenovus Energy is converting its integrated model into cash after years of heavy capital spending. A softer print would not change the physical asset base, but it would sharpen questions around tax drag, condensate exposure and how much room is left for further cost gains.
Cenovus Energy's current earnings are estimated at CA$6.7b, with analysts forecasting CA$6.3b of earnings and CA$56.7b of revenue by 2029. That outlook assumes yearly revenue growth of 1.7% and an earnings decline of CA$0.4b from earnings today.
Uncover why Cenovus Energy's fair value indicates an 11% potential upside to its current price that may not last much longer.
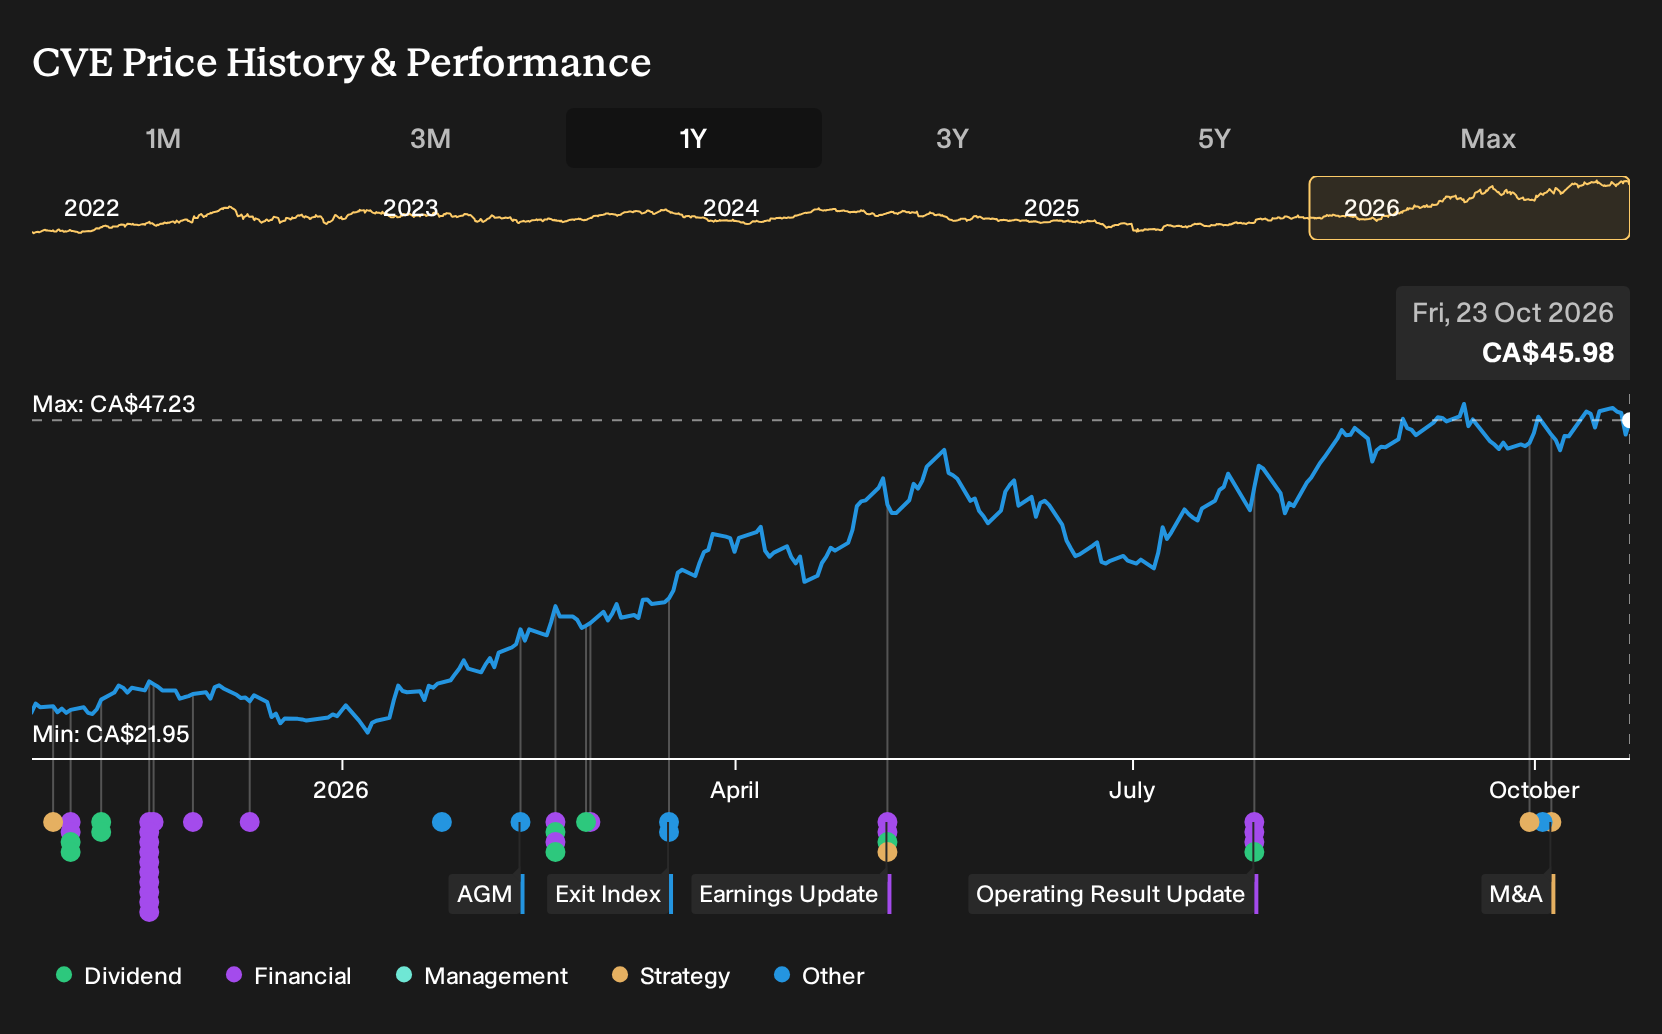
Exploring Other Perspectives
Short term earnings risk is where the lowest Cenovus Energy analysts draw a hard line. While the consensus narrative points to CA$6.3b of earnings on CA$56.7b of revenue by 2029, the bearish view sits nearer CA$3.2b and CA$57.2b. Those forecasts came before this earnings setup, so use the gap to test your own expectations.
Explore 3 other Cenovus Energy fair value estimates, including one that suggests it could be worth just CA$51.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cenovus Energy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cenovus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cenovus Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cenovus Energy?
Once you have a view on Cenovus Energy, it can help to compare that thesis against a wider watchlist so you see where the risk and income trade offs really sit for your portfolio.
- If you want income to do more of the heavy lifting, scan a set of potential high yield candidates through 3 dividend fortresses.
- For investors who care most about strength in the balance sheet and fundamentals, start with this focused list of solid balance sheet and fundamentals (7 results).
- If you are hunting for ideas that the market may not be paying close attention to yet, build a watchlist from a curated pool of 9 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com