


Is Longfor Group Holdings (SEHK:960) Undervalued Following Its Nine Month 2026 Operating Update?
Longfor Group Holdings (SEHK:960) is back in focus after releasing operating results for the nine months to 30 September 2026, detailing contracted sales volumes and revenue from its property operation and service activities.
At a share price of HK$4.935, Longfor Group Holdings has seen the 30 day share price return fall 9.53% and the year to date share price return decline 43.54%, while the 1 year total shareholder return is down 50.76%. This points to fading momentum as investors reassess both risk and recovery potential in light of the latest operating update.
Compare Longfor Group Holdings’ reset expectations with other beaten down real estate plays by scanning our hand picked 194 high quality undervalued stocks that still pair solid cash generation with balance sheet strength.
The share price slide at Longfor Group Holdings contrasts awkwardly with stable contracted sales and service revenue. Is the market marking down the business itself, or is it simply resetting sentiment around China property risk as the valuation shifts?
Preferred Price-to-Sales Multiple of 0.4x: Is it justified?
Valuation screens paint Longfor Group Holdings as inexpensive, with the stock trading on a P/S ratio of 0.4x compared with an estimated fair P/S level of 0.5x and a Hong Kong real estate sector average of 0.6x.
The P/S yardstick compares the company’s market value with its HK$78,353.551m of revenue and is often used when earnings are weak or loss making, as is the case here. For Longfor Group Holdings, that low multiple effectively means investors are paying less for each dollar of reported sales while still taking on the risks attached to a China focused developer and operator.
Relative to peers on a 0.6x industry P/S and a 1.3x peer average, the 0.4x tag looks compressed. The gap to the estimated fair P/S of 0.5x is also clear, which indicates that the market is heavily discounting the quality and durability of those revenues and may only move closer to that fair level if profit forecasts, funding quality or sentiment toward the sector shift meaningfully.
Explore the SWS fair ratio for Longfor Group Holdings.
Result: Price-to-sales of 0.4x (UNDERVALUED)
Still, the annual revenue decline and reported net loss of CN¥232.582m leave Longfor Group Holdings exposed if China property demand or funding conditions weaken further.
Find out about the key risks to this Longfor Group Holdings narrative.
Another view on Longfor Group Holdings’ value
The P/S workup presents Longfor Group Holdings as inexpensive, while our DCF model offers a different perspective. At HK$4.94, the stock trades well below an estimated future cash flow value of HK$18, which frames it as deeply undervalued based on that cash flow lens. Which signal do you weigh more heavily?
For a closer look at the moving parts behind that cash flow estimate and the assumptions built into it, take a moment to review the Look into how the SWS DCF model arrives at its fair value.
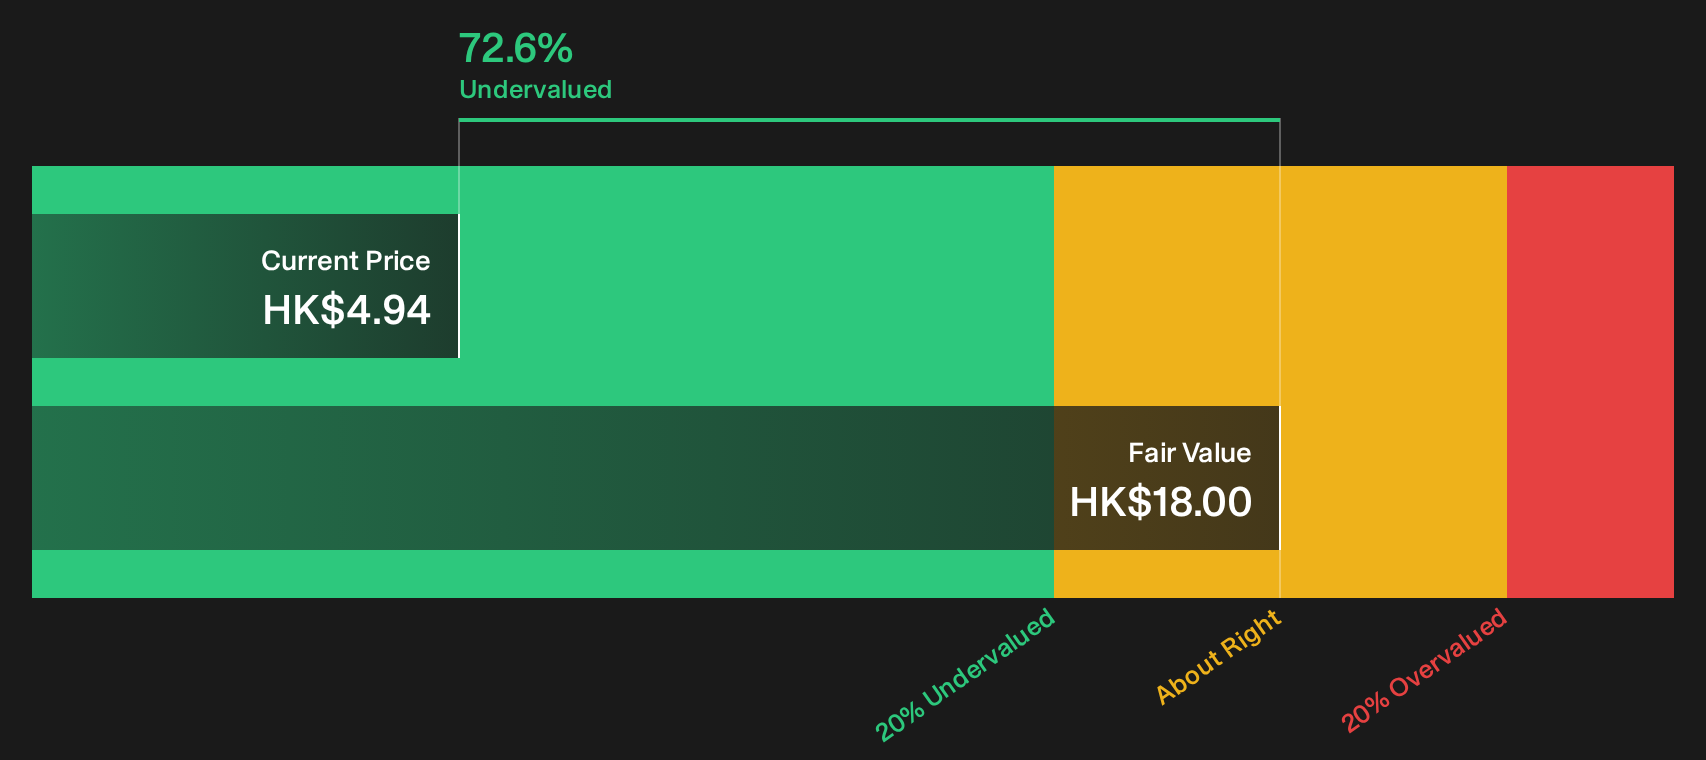
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Longfor Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Longfor Group Holdings looks mixed, with pressure on the share price but signals of underlying value still on the table. Act while the data is fresh and build your own thesis by weighing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Longfor Group Holdings?
Do not stop with Longfor Group Holdings. Use fresh stock ideas from structured screeners to pressure test your thesis and keep your watchlist one step ahead.
- Hunt for potential turnaround stories by scanning our beaten up value opportunities through the 194 high quality undervalued stocks.
- Anchor your portfolio with payout focused candidates by reviewing a curated pool of income ideas in the 226 dividend fortresses.
- Prioritise resilience by filtering for financially sturdy businesses in the list of solid balance sheet and fundamentals (205 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com