


Ameris Bancorp (ABCB) Buyback And Record Quarter Put Its Valuation Back In Focus
Ameris Bancorp (ABCB) just posted record third quarter earnings per share alongside higher net interest income, while also approving a fresh US$200 million buyback that points to ongoing capital returns despite rising charge offs.
Ameris Bancorp’s recent record quarter and renewed US$200 million buyback arrive as the share price trades at US$82.63, with a 7 day share price return of 3.65% but a 90 day share price return that has slipped 3.96%. At the same time, the 1 year total shareholder return of 12.75% and 3 year total shareholder return of about 1.4x suggest longer term momentum has been strong even as near term trading reflects a more cautious reset around higher charge offs and what investors are willing to pay for that earnings power.
Compare Ameris Bancorp’s record quarter and fresh buyback with other banks returning cash to shareholders by scanning our hand picked 5 dividend fortresses for potential ideas in the same income-focused lane.
Ameris Bancorp has record quarterly earnings, a larger buyback and a share price that has cooled over 90 days. Does that mix still skew the risk reward toward buyers at today’s valuation?
Most Popular Narrative: 12% Undervalued
Against Ameris Bancorp’s last close at $82.63, the most followed narrative points to a fair value near $94.17. This frames the fresh US$200 million buyback and recent record quarter as part of a wider earnings story that still leaves room in the valuation gap.
Analysts expect earnings to reach $539.7 million (and earnings per share of $7.75) by about October 2029, up from $376.3 million today.
In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 13.7x on those 2029 earnings, down from 14.5x today.
See why 1 investors see Ameris Bancorp as 12% undervalued.
Result: Fair Value of $94.17 (UNDERVALUED)
Still, the Ameris Bancorp story could change quickly if the US$82.5 million litigation accrual grows or if rising deposit costs squeeze the net interest margin faster than expected.
Find out about the key risks to this Ameris Bancorp narrative.
Another View: What Ameris Bancorp’s P/E Is Saying
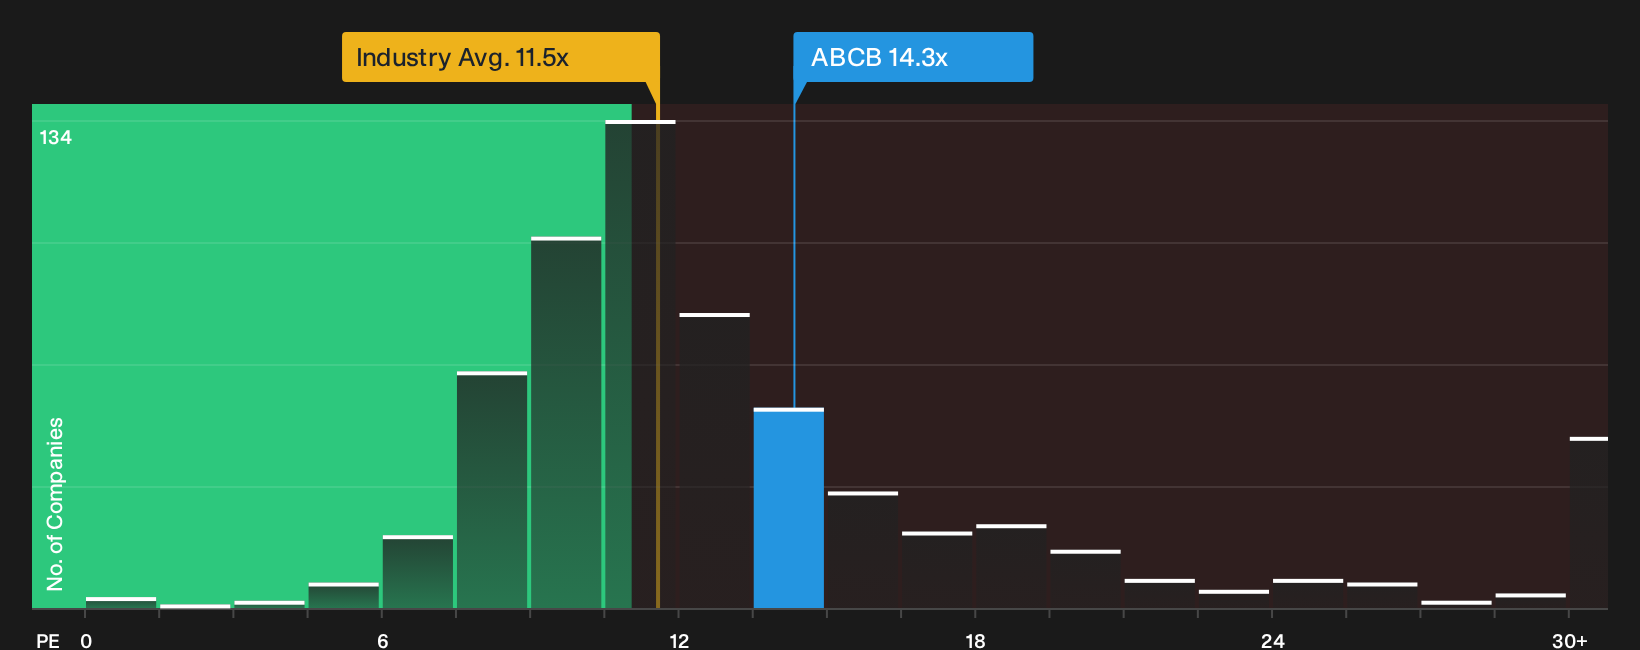
The fair value narrative pegs Ameris Bancorp at $94.17, yet the P/E of 14.3x paints a different picture. That multiple is higher than the US Banks industry on 11.5x, higher than the peer group on 11.1x, and above a fair ratio of 12.8x that the market could move toward. If sentiment cools, how comfortable are you owning a bank that screens as expensive on earnings even while it screens as cheap on fair value models?
To pressure test that earnings based view against a fuller set of valuation checks and peer comparisons, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or quiet opportunity: either way you are better off interrogating the numbers yourself and stress testing your own thesis on Ameris Bancorp. To see which potential upsides investors are currently focused on, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond Ameris Bancorp?
If Ameris Bancorp has sharpened your focus on quality, do not stop here. Use the Simply Wall St screener to spot other opportunities before the crowd.
- Target stronger income potential by scanning a curated set of 5 dividend fortresses that line up generous yields with robust underlying businesses.
- Hunt for value opportunities using the 29 high quality undervalued stocks that highlight companies combining solid fundamentals with prices that look compressed.
- Prioritise resilience first and look through the 30 resilient stocks with low risk scores that flags businesses with more defensive financial risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com