


Workiva (WK) Could Be 4% Undervalued On Its Return To Profit
Workiva (WK) is back in focus after its latest earnings release, where the reporting software provider posted revenue growth and moved from a net loss to a net profit, drawing fresh investor attention.
Recent trading has turned sharply in Workiva's favor, with a 7 day share price return of 13.9% and a 90 day gain of 53.9%. However, the 1 year total shareholder return is still down 3.8%, which suggests short term momentum has improved while long term investors remain under water.
Scan how Workiva's earnings momentum compares by reviewing the hand picked 21 high quality undiscovered gems that also pair strengthening fundamentals with renewed market attention.
Workiva has just flipped to profitability and the share price has sprinted ahead, yet long term returns are still in the red. Has most of the repricing already happened, or does the valuation still leave meaningful room?
Most Popular Narrative: 4% Undervalued
Workiva last closed at $85.80 compared with a widely followed narrative fair value of $89.80. This frames the recent rally as only a partial catch up rather than a fully priced story.
The analysts have a consensus price target of $89.8 for Workiva based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $105.0, and the most bearish reporting a price target of $80.0.
See why 8 investors see Workiva as 4% undervalued.
Result: Fair Value of $89.80 (UNDERVALUED)
Still, the bullish Workiva story can unravel if European rules such as CSRD or CSDDD shift materially, or if a weaker macro backdrop crimps customer budgets for new reporting projects.
Find out about the key risks to this Workiva narrative.
Another View: What Multiples Say About Workiva
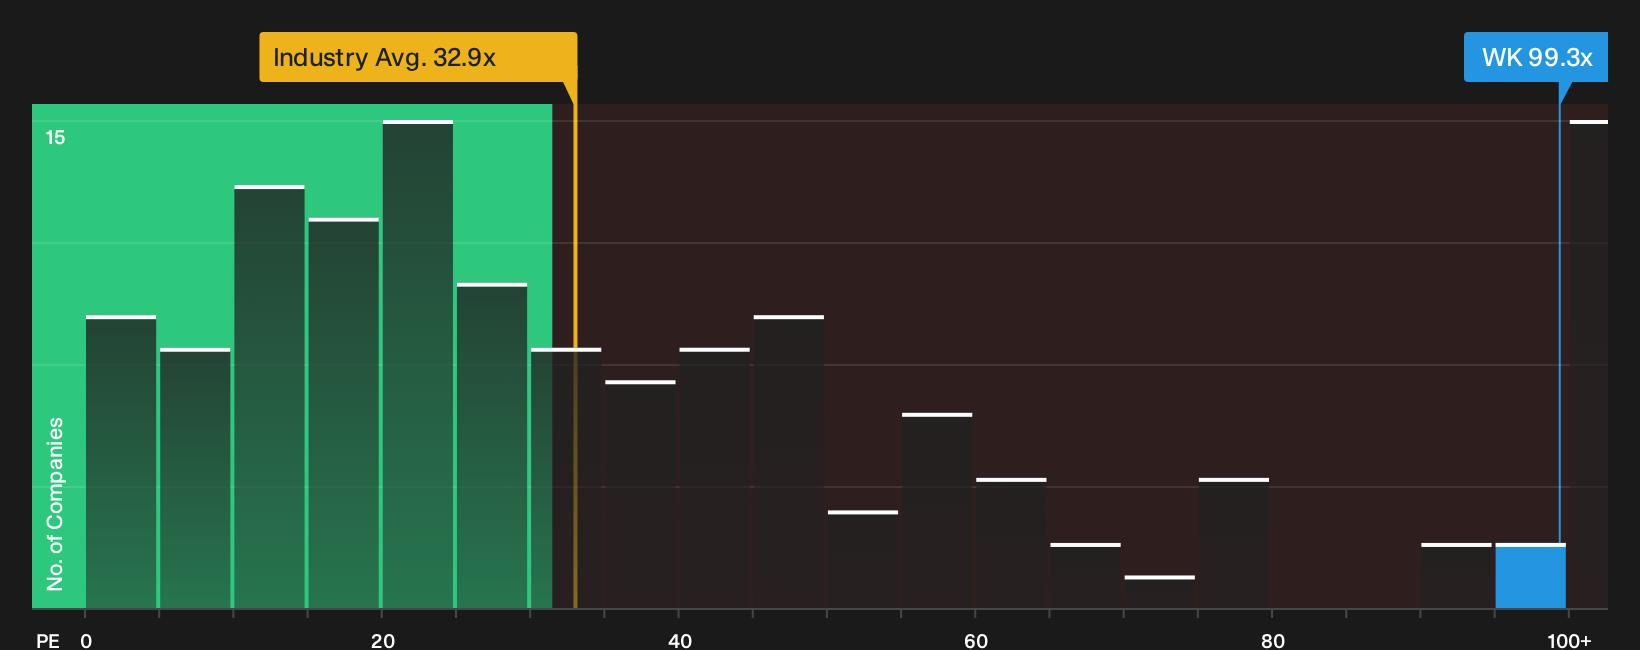
Our model based on P/E tells a very different story for Workiva. The shares trade on 99.3x earnings, compared with 51.8x for peers and 32.9x for the wider US Software group, while the fair ratio sits at 40.5x. That gap points to valuation risk rather than a simple bargain. Is this pricing more about excitement than fundamentals catching up?
For a closer look at how that P/E gap stacks up against history and peers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Workiva story so far. Move quickly, check the underlying data yourself, weigh the trade off between the 1 or more risks and 1 or more rewards, then review the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Workiva?
Do not stop your research at one ticker. Broaden your opportunity set with curated ideas that fit clear rules, so you are not relying on guesswork.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (24 results) that filter for companies with stronger financial footing and healthier fundamentals.
- Hunt for mispriced quality using the 29 high quality undervalued stocks to surface stocks that pair solid fundamentals with valuations that may not fully reflect them.
- Build dependable income streams by reviewing the 5 dividend fortresses focused on businesses offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com