


Ackermans And Van Haaren Is Just One Of Our 3 Top Value Stocks
AI focused capital spending has become a sticking point for big technology groups, with investors questioning when heavy outlays will translate into dependable cash generation. That kind of doubt can push even cash rich businesses below what detailed cash flow models suggest they are worth. For anyone hunting potential mispriced opportunities, this article walks through three stocks our cash flow screen flags as trading at a discount to their underlying money making power.
The three stocks highlighted next are only a sample, as the full cash flow screen surfaced another 460 companies with similarly interesting stories that are not covered here.
If you want to identify, filter, and analyze the highest conviction ideas from that broader list, head straight to the Undervalued Stocks Based On Cash Flows screener.
Ackermans & Van Haaren (ENXTBR:ACKB)
Ackermans & Van Haaren is a Belgian holding group whose €5.3b Marine Engineering & Contracting arm drives heavy dredging and offshore wind projects, alongside sizeable private banking, real estate and growth capital activities. The group has a market value of about €8.3b, which anchors the broader investment platform.
Ackermans & Van Haaren brings together marine infrastructure, financial services and real assets in a way that can matter for value-focused investors who prioritize steady cash generation over headline growth stories.
"The strong growth and record results achieved by Delen Private Bank and Bank Van Breda, with net inflows and synergetic collaboration, reflect revenue growth from financial services."
The key issue is how that improving profitability interacts with the unresolved question of how future funding choices could reshape the durability of those cash flows.
That funding puzzle is exactly what the full narrative for Ackermans & Van Haaren unpacks, highlighting where cash generation, capital allocation and Marine Engineering exposure could be quietly decoupling from sentiment.
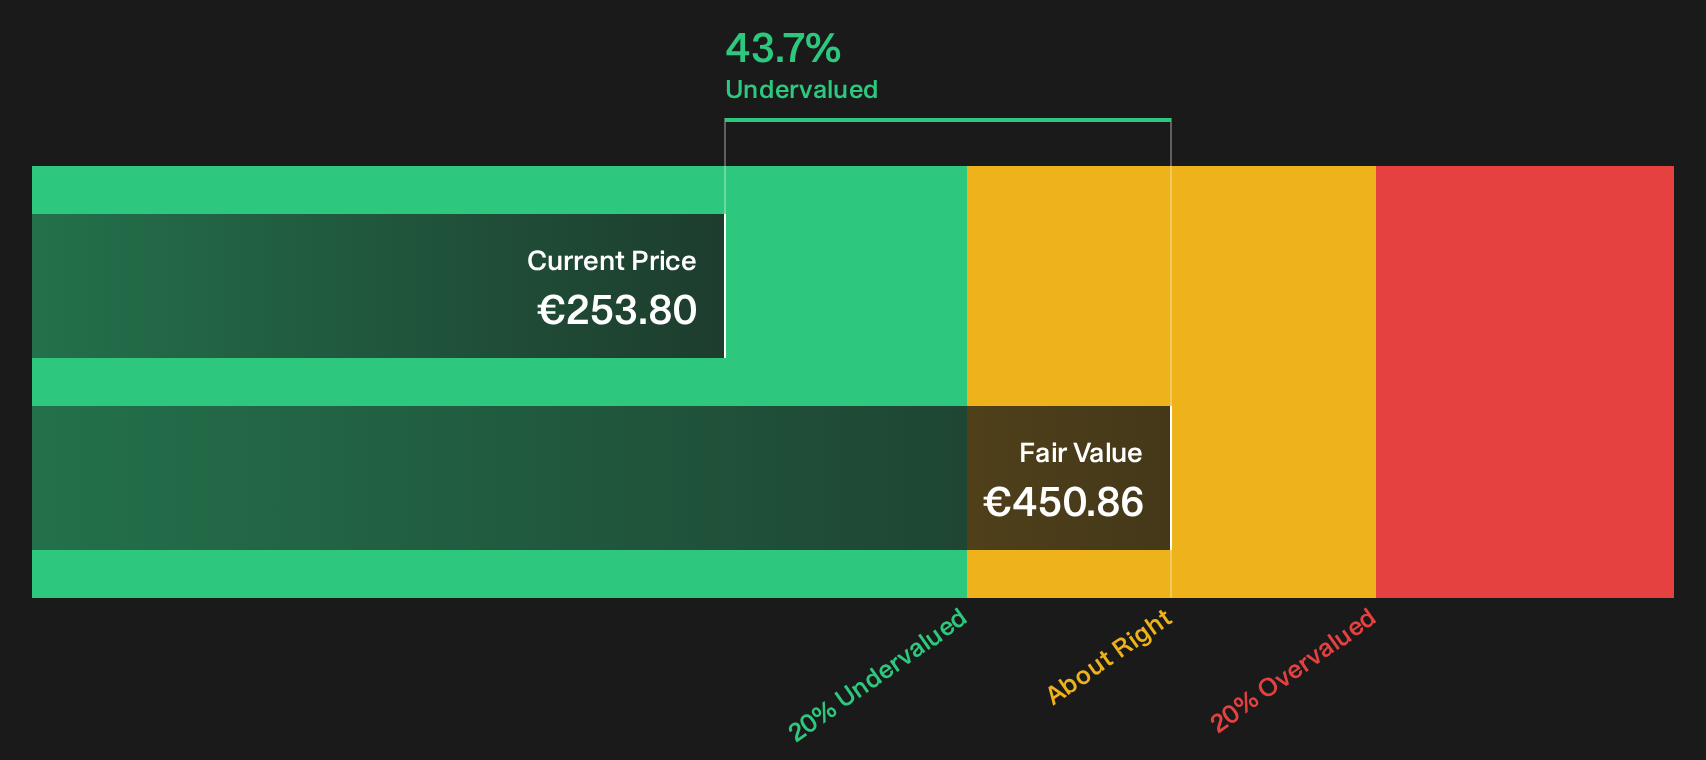
Protector Forsikring (OB:PROT)
Protector Forsikring is a non-life insurer focused on motor, property and liability cover, where underwriting and investment float drive the recurring cash flows that matter for this screen. It generated NOK 15.2b from property and casualty insurance and has a NOK 36.5b market value.
For the Undervalued Stocks Based On Cash Flows theme, Protector Forsikring matters because its day to day underwriting across motor, property and liability turns a stream of premiums into the type of recurring cash generation a DCF model can actually anchor on.
"Protector Forsikring continues to build out its data and AI tools across underwriting, claims and support functions, with management accepting higher current costs in order to raise decision accuracy and make the cost base more scalable, which is aimed at supporting net margins and earnings."
The real swing factor is how one quiet shift in the quality of those future underwriting results ultimately feeds through into long term profitability.
That underwriting swing factor is exactly what the full narrative for Protector Forsikring unpacks, mapping how Protector Forsikring’s AI spend, risk appetite and float returns could be quietly accelerating or stalling its cash engine.

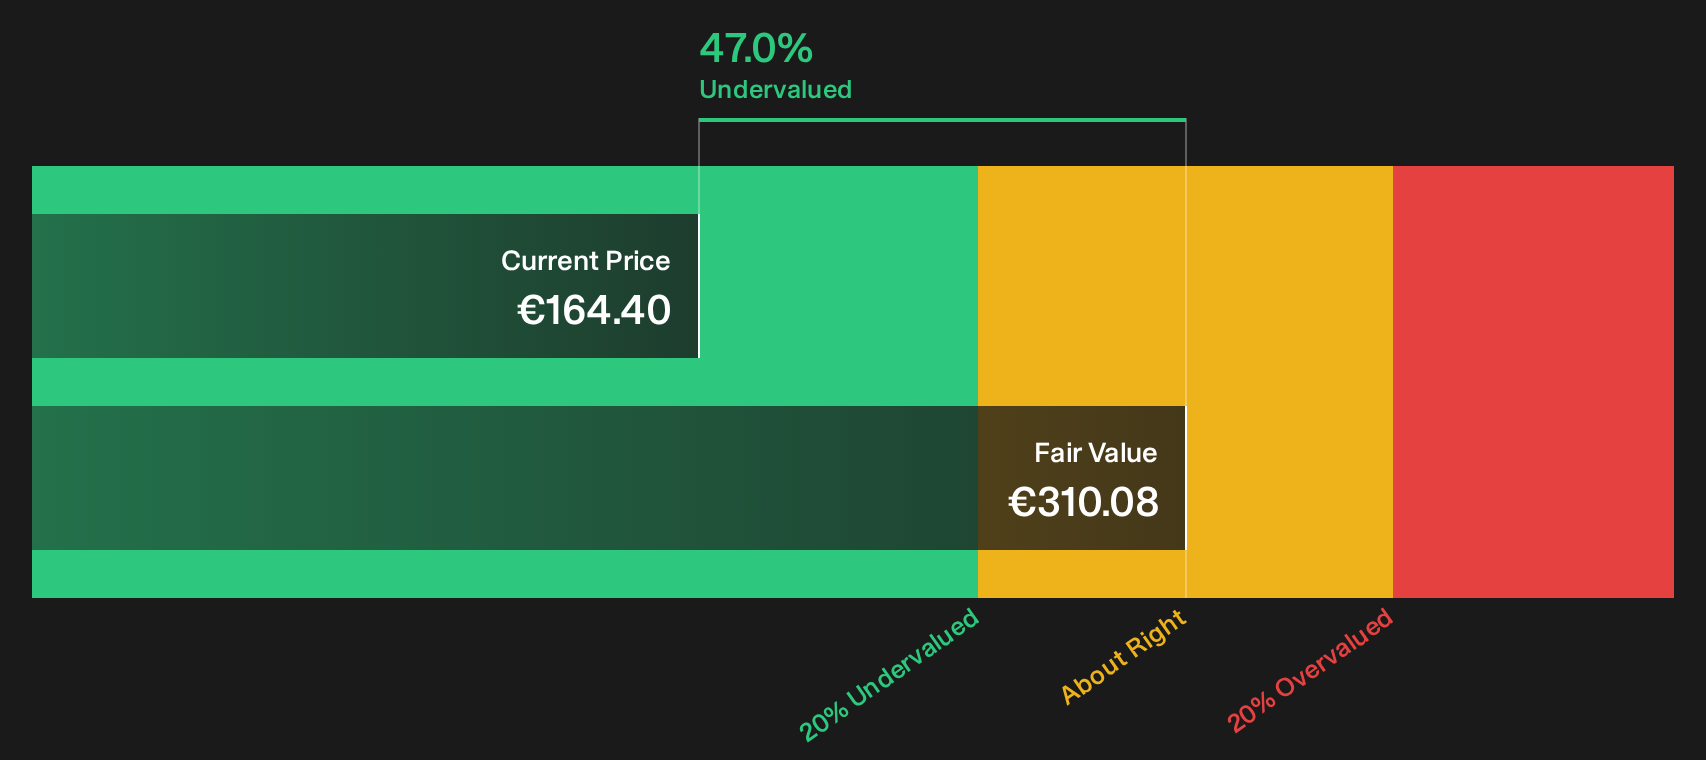
DEME Group (ENXTBR:DEME)
DEME Group is a marine contractor focused on offshore wind projects that can lock in long term, contract backed cash flows, alongside sizeable Dredging & Infra and Environmental work, with Offshore Energy generating about €2.2b of revenue and Dredging & Infra €2.0b, and the group valued around €4.1b.
For the Undervalued Stocks Based On Cash Flows theme, DEME Group interests investors who care about how contract backed offshore wind work translates into dependable cash generation over time, and how that visibility squares with the valuation debate around its cash flow models.
"The shares have traded only since June 2022, so the beta is measured on 50 months. Its 95 % interval runs from 0,52 to 1,54, which by itself moves the discount rate by whole percentage points."
Everything then hinges on how one unresolved pressure around future project returns shapes the cash yield investors eventually see on those contracts.
That pressure point is exactly what the full narrative for DEME Group unpacks, showing where project risk, contract quality and cash yields may be quietly accelerating or stalling the value story of DEME Group.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. When the next breakout list starts gaining momentum, early entries often get the best risk reward skew while it matters. Scan what others miss, and act now.
- Spot income workhorses that aim to keep paying while prices swing. Then scan the 226 dividend fortresses curated for balance sheet strength and payout resilience.
- Track reshaping trends in robotics and automation before they are fully priced in by checking the 95 robotics and automation stocks built around operational strength and cash discipline.
- Hunt for resilient balance sheets that could ride the next rate or credit cycle by reviewing the list of solid balance sheet and fundamentals (205 results) tailored for financial durability and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com