


Does Job Cuts Change The Bull Case For Westpac Banking (ASX:WBC)?
- Westpac Banking has begun a workforce shake up, with over 250 roles marked for redundancy since early October and about 140 more positions affected this week as part of a broader organisational restructure that management says is not driven by AI adoption.
- The Finance Sector Union is organising consultations across Westpac and NAB as staff respond to concerns about offshoring and the potential loss of Australian banking functions, putting a spotlight on how Westpac Banking balances cost reduction with service capacity and operational resilience.
- We will look at how Westpac Banking's investment narrative is affected by cost focused workforce restructuring that targets more than 250 roles.
Westpac Banking Investment Narrative Recap
To own Westpac Banking, you need to believe that its big technology and simplification programs, along with disciplined lending and funding, can keep returns acceptable even if margins stay tight and revenue growth is modest. The current workforce restructuring and union pushback are part of this cost story rather than a replacement for it.
In the near term, the key swing factor is whether cost initiatives like UNITE and broader restructuring genuinely lower the cost-to-income gap without disrupting customer service or credit quality. The biggest risk remains pressure on net interest margin and any rise in impairments from higher-yielding business and institutional lending.
The shareholder resolution to amend Westpac Banking’s constitution and allow advisory member resolutions at general meetings is the announcement that most closely relates to the restructuring headlines. It points to a potential increase in formal channels for investors to question how management uses its powers on issues such as jobs, technology spending and offshoring.
These resolutions would be advisory only, so they do not change day-to-day control of operations. They could, however, keep topics such as cost cuts, workforce structure and UNITE program execution more visible at the AGM. For a reader, that means catalysts and risks around expenses, service quality and balance sheet growth may be discussed more openly in future meetings.
What The Forecasts Assume For Westpac Banking
Westpac Banking's narrative projects A$24.7b revenue and A$7.7b earnings by 2029. This is built on analysts assuming 3.5% yearly revenue growth and about A$0.7b earnings increase from A$7.0b today.
Uncover why Westpac Banking's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
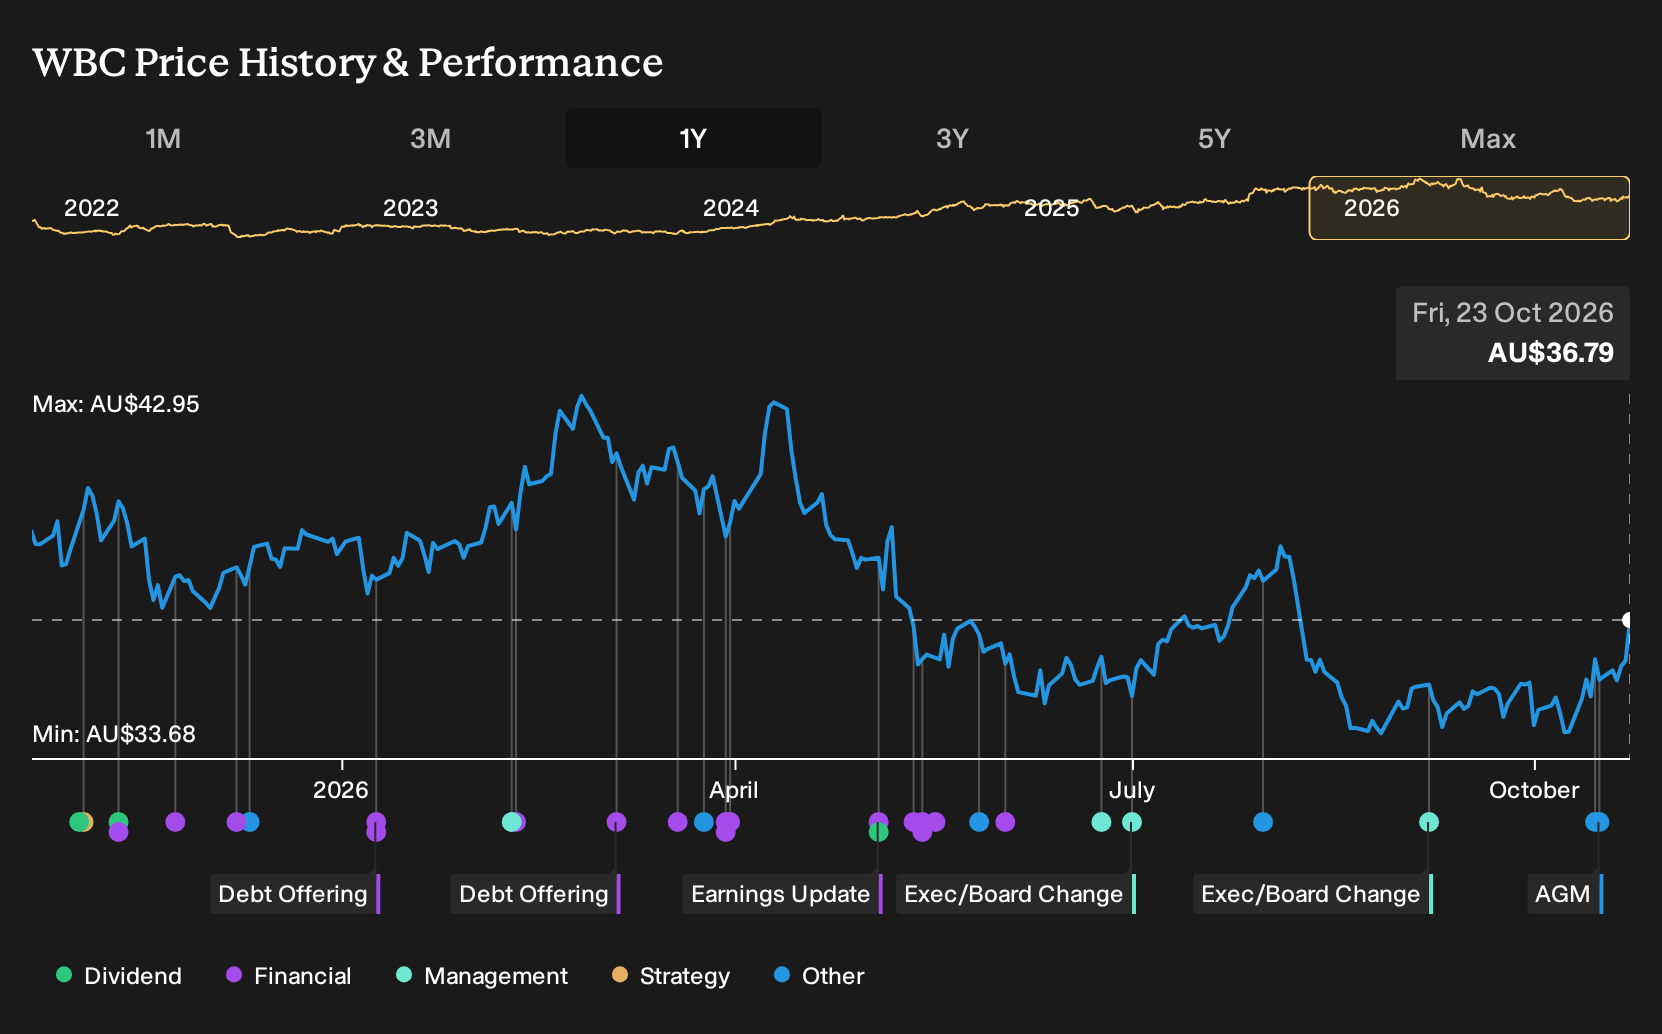
Exploring Other Perspectives
One alternate angle treats Westpac Banking’s cost focus as a catalyst rather than a risk. The most optimistic analysts were sketching out A$25.8b revenue and A$8.4b earnings by 2029 before this workforce and constitution news, so they saw deeper productivity gains. You can compare that upbeat scenario with the baseline and decide which story feels closer to your own view.
Explore 2 other Westpac Banking fair value estimates, including one that suggests it could be worth as much as A$33.47.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Westpac Banking research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Westpac Banking. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westpac Banking's overall financial health at a glance.
Looking For More Ideas Beyond Westpac Banking?
If the Westpac Banking story has sharpened your thinking on risk, dividends and balance sheet strength, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- For readers who want potential value with quality fundamentals, scan our handpicked 2 high quality undervalued stocks and see which companies fit a similar cost and efficiency mindset.
- If capital preservation sits higher on your priority list, filter for businesses that score well on resilience using our 6 resilient stocks with low risk scores to compare with Westpac Banking's risk profile.
- When you want to broaden the watchlist with sturdier finances, build a shortlist from the list of solid balance sheet and fundamentals (12 results) and see how those balance sheets stack up against the bank's own position.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com