


How New Investor Presentation Will Impact Dalrymple Bay Infrastructure Shares
- Dalrymple Bay Infrastructure released an investor presentation for Asian and Australian conferences, outlining its focus on operational execution, regulated coal export infrastructure and potential terminal capacity expansions at Dalrymple Bay Terminal.
- The presentation underlined Dalrymple Bay Infrastructure’s role in the global steelmaking supply chain and highlighted its objective of sustaining cash flows and distributions backed by long-term, regulated contracts.
- This development provides updated context for Dalrymple Bay Infrastructure's investment narrative, particularly in relation to its emphasis on operational excellence and capacity expansion.
Dalrymple Bay Infrastructure Investment Narrative Recap
To own Dalrymple Bay Infrastructure, you need to be comfortable with a regulated, coal linked infrastructure asset that leans heavily on long term take or pay contracts and CPI indexed tariffs for its cash generation. The investor presentation mostly reinforces that story rather than changing it. In the near term, the key swing factor remains how smoothly the NECAP program and terminal operations run while metallurgical coal volumes stay contracted.
The biggest operational risk is still execution and funding of that multi year capex program against rising all in interest costs toward about 7% and a dividend that analysts flag as not well covered. The new presentation does not materially alter that risk and reward profile. It simply refreshes the emphasis on utilisation, asset reliability and capital discipline.
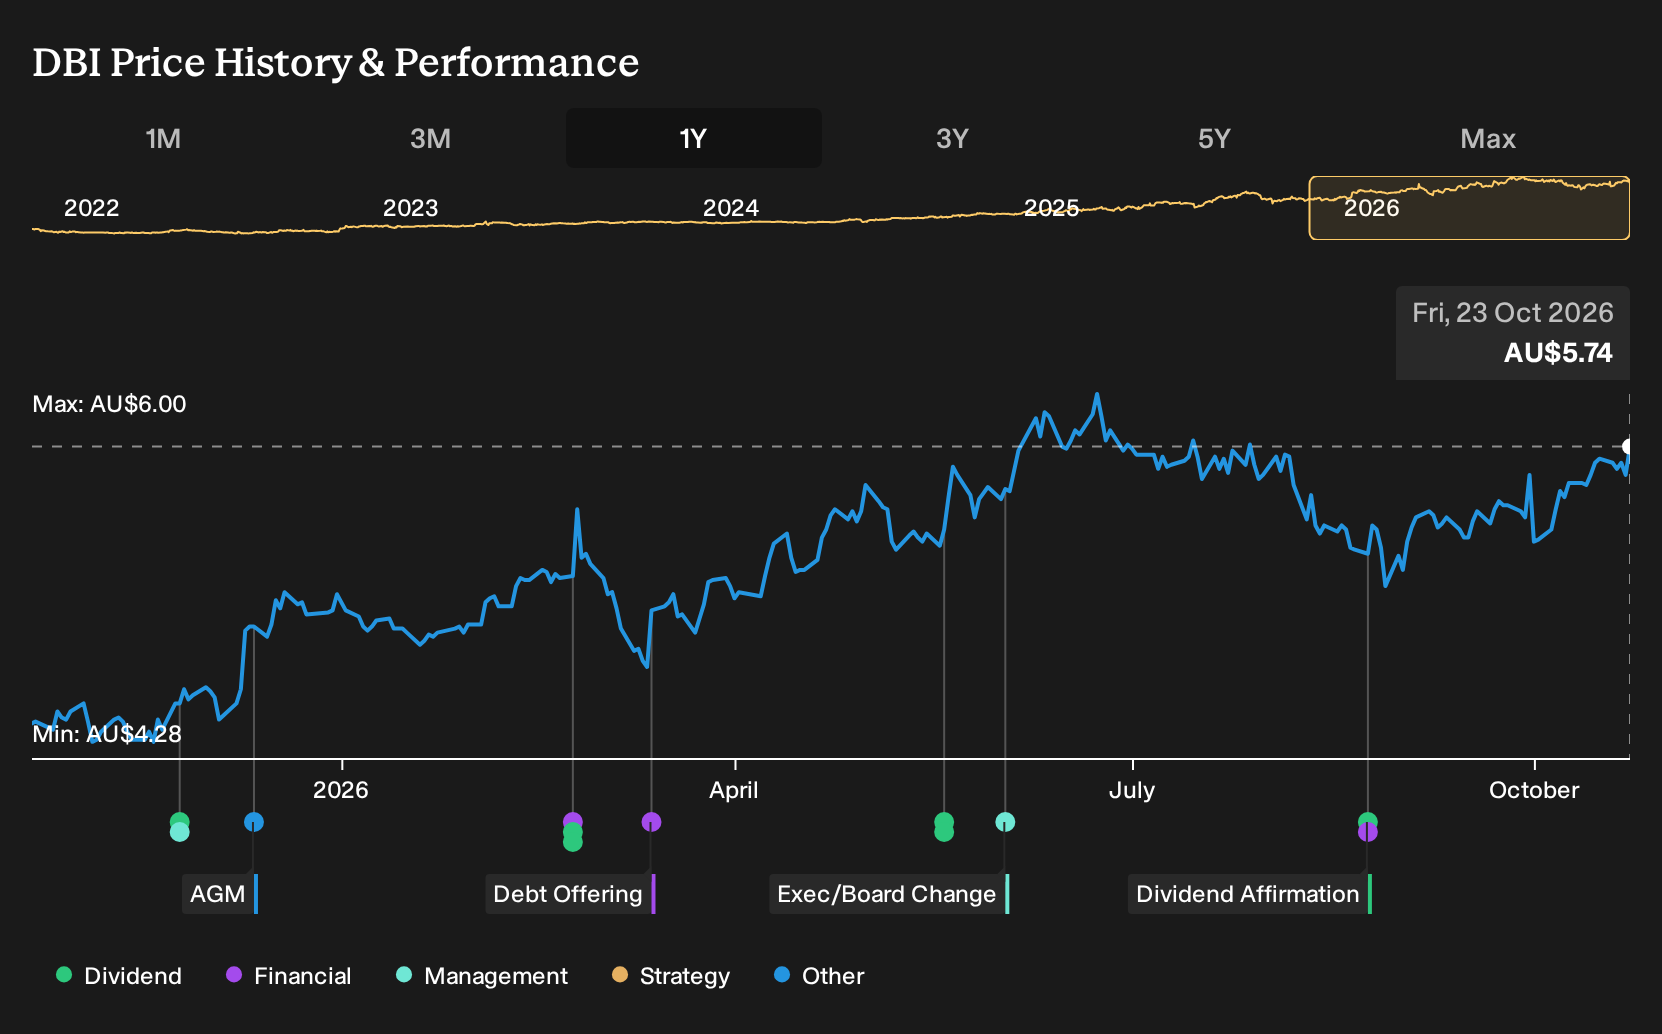
The recent investor presentation is the announcement that really matters here, because it ties directly to the main catalyst analysts focus on, namely converting regulated tariff settings and NECAP into higher EBITDA and funds from operations after 2027. Management used it to reiterate that the current 84.2 Mtpa capacity is fully contracted under 100% take or pay terms to at least June 2028 with pricing fixed to 2031.
That reminder links back to the regulated mechanics investors often anchor on. CPI indexation of the Terminal Infrastructure Charge to 2031, inclusion of qualifying capex in the asset base, and guidance that every A$0.10 per tonne lift adds about A$8.5m of revenue all frame the potential upside if NECAP is delivered cleanly. The same deck also implicitly highlights the risk that higher debt funding and weaker earnings coverage of interest and dividends could squeeze flexibility if execution slips.
Dalrymple Bay Infrastructure’s current analyst script points to A$1.0b in revenue and A$150.3m in earnings by 2029, based on an assumed 13.9% yearly revenue growth rate and an earnings increase of about 4.3x from A$35.3m today.
Uncover why Dalrymple Bay Infrastructure's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community put Dalrymple Bay Infrastructure anywhere between A$3.75 and about A$25.29, so retail opinion ranges from deep discount to rich pricing. When this is set against long-dated take or pay contracts, NECAP spend and ESG financing risks, there are strong reasons to test multiple viewpoints before committing fresh capital.
Explore 2 other Dalrymple Bay Infrastructure fair value estimates, including one that suggests as much as 341% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dalrymple Bay Infrastructure research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Dalrymple Bay Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dalrymple Bay Infrastructure's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dalrymple Bay Infrastructure?
If Dalrymple Bay Infrastructure has sharpened your focus on income, balance sheet strength or long dated assets, it can help to widen the lens and compare it with other businesses that share some of those traits but sit in different sectors or capital structures.
- If capital preservation and steady fundamentals matter most to you, start with a 6 resilient stocks with low risk scores that score well on resilience and financial strength.
- If you want potential mispricing combined with quality, scan a curated group of 2 high quality undervalued stocks that pair cash generation with solid fundamentals.
- If you are hunting for lesser known opportunities with cleaner balance sheets, check out a 15 high quality undiscovered gems that still fly under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com