


Benchmark Electronics (BHE) Could Be 23% Below Fair Value After Its Recent Pullback
Benchmark Electronics (BHE) has drawn fresh attention after a sharp pullback, with the share price down 20% over the past month and 17% over the past 3 months. Investors are reassessing what the current valuation implies.
That recent slide comes after a strong run, with the share price still showing a year to date gain of about 50% and a 1 year total shareholder return of about 57%. Momentum has faded in the short term, even as longer term holders remain well ahead.
Scan how Benchmark Electronics stacks up against a hand picked group of resilient peers using the 30 resilient stocks with low risk scores that filters for stocks with stronger risk profiles.
Bulls see Benchmark Electronics as a quality operator that has simply reset after a strong run. Bears view the drop as a warning. Which side does the current valuation actually support next?
Most Popular Narrative: 23% Undervalued
Benchmark Electronics currently trades at $65.81, while the most followed valuation narrative pegs fair value at $86 using a 9.1% discount rate. That gap hinges heavily on whether its biggest growth engines keep translating into real orders and earnings.
Benchmark Electronics is positioned to benefit from surging demand for advanced computing and AI infrastructure, now supported by 41% and 71% year-over-year AC&C revenue growth in Q1 and Q2 2026 driven by clustered AI and on prem cloud programs and by recognition as HPE’s 2026 Manufacturing Partner of the Year. Together these factors point to further contribution from upcoming high performance computing ramps into 2027 that can support revenue and gross margin.
See why 7 investors see Benchmark Electronics as 23% undervalued.
Result: Fair Value of $86 (UNDERVALUED)
Still, the Benchmark Electronics story can crack if insider selling persists while free cash flow stays thin, or if tighter component supply starts to choke deliveries.
Find out about the key risks to this Benchmark Electronics narrative.
Another View: Benchmark Electronics Through A Cash Flow Lens
The popular story says Benchmark Electronics is about 23% undervalued at a fair value of $86. The SWS DCF model tells a very different story. On that measure, BHE at $65.81 trades above an estimated future cash flow value of $45.63, which screens as overvalued. When cash and contracts start to diverge, which yardstick do you trust more?
Look into how the SWS DCF model arrives at its fair value.
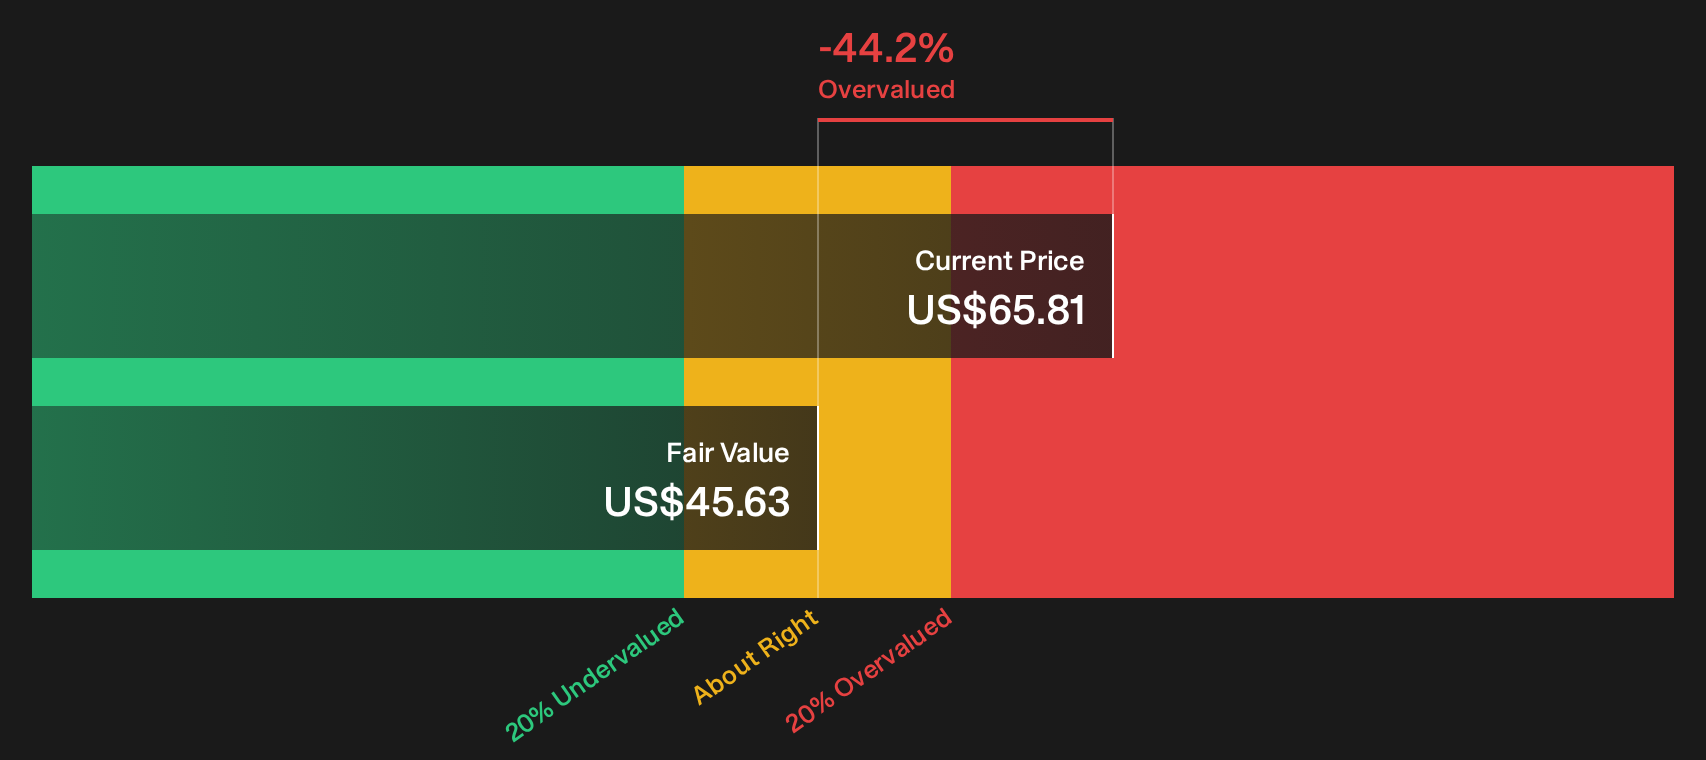
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Benchmark Electronics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Benchmark Electronics story so far. Act while the data is fresh, weigh both sides, and stress test the 3 key rewards and 1 important warning sign.
Looking for more Benchmark Electronics investment ideas?
If you stop with Benchmark Electronics, you miss the wider opportunity set. Use the Simply Wall St screener to line up your next potential moves with intent.
- Target quality at a discount by scanning the 29 high quality undervalued stocks which filters for businesses with solid fundamentals priced below what their cash flows may imply.
- Prioritise resilience and capital strength through the list of solid balance sheet and fundamentals (24 results) which highlights companies with sturdier finances and cleaner balance sheets.
- Get ahead of the crowd by tracking the 21 high quality undiscovered gems focused on under-the-radar stocks supported by stronger underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com