


Earnings Preview Could Be A Big Test For Albemarle (ALB)
- Albemarle is preparing to report Q3 2026 results after the close on 4 November, with analysts expecting higher earnings per share and revenue than a year ago, supported by its Energy Storage segment and ongoing cost and productivity initiatives.
- An important angle is how Albemarle’s efforts to cut capital spending and increase free cash flow intersect with investor attention on whether lithium volumes and pricing pressure might affect near term profitability.
- The focus then shifts to how Albemarle's investment narrative may be influenced by investor expectations for upcoming earnings performance.
Scan how Albemarle’s setup compares with other potential opportunities by lining it up against our hand picked 29 high quality undervalued stocks, which also pair free cash flow strength with disciplined spending plans.
Albemarle Investment Narrative Recap
To own Albemarle, you need to be comfortable with a lithium business that is tightly linked to electric vehicle and energy storage demand, while also exposed to commodity style pricing. The big near term swing factor is how much cost savings, productivity gains and reduced capital spending can offset management’s expectation of weaker lithium volumes and pricing pressure.
The key risk right now is that lithium prices and volumes stay soft for longer, which could restrain free cash flow after a period of heavy investment. The upcoming Q3 2026 report matters mainly as a check on whether cost cuts are translating into steadier margins in Albemarle’s Energy Storage segment.
The clearest recent anchor for this setup is Albemarle’s own guidance that lithium sales volumes and prices may decline in the near term while capital spending steps down and cost savings ramp. That combination puts the spotlight on execution. Investors are watching whether lower spending translates into healthier free cash flow without eroding the future project pipeline.
The 4 November earnings release now acts as a real time test of that message. If the update shows progress on the US$400m cost savings run rate and disciplined capex, then the story remains about how Albemarle manages a low price lithium environment. If pressure on Energy Storage margins is heavier than expected, the debate shifts back toward how durable those free cash flow gains really are.
Albemarle's narrative projects US$6.9b revenue and US$2.3b earnings by 2029. That assumes revenue grows at about 5.1% a year and earnings rise by about US$2.2b from the current US$57.4m baseline.
Uncover why Albemarle's fair value indicates a 69% potential upside to its current price, which could narrow quickly.
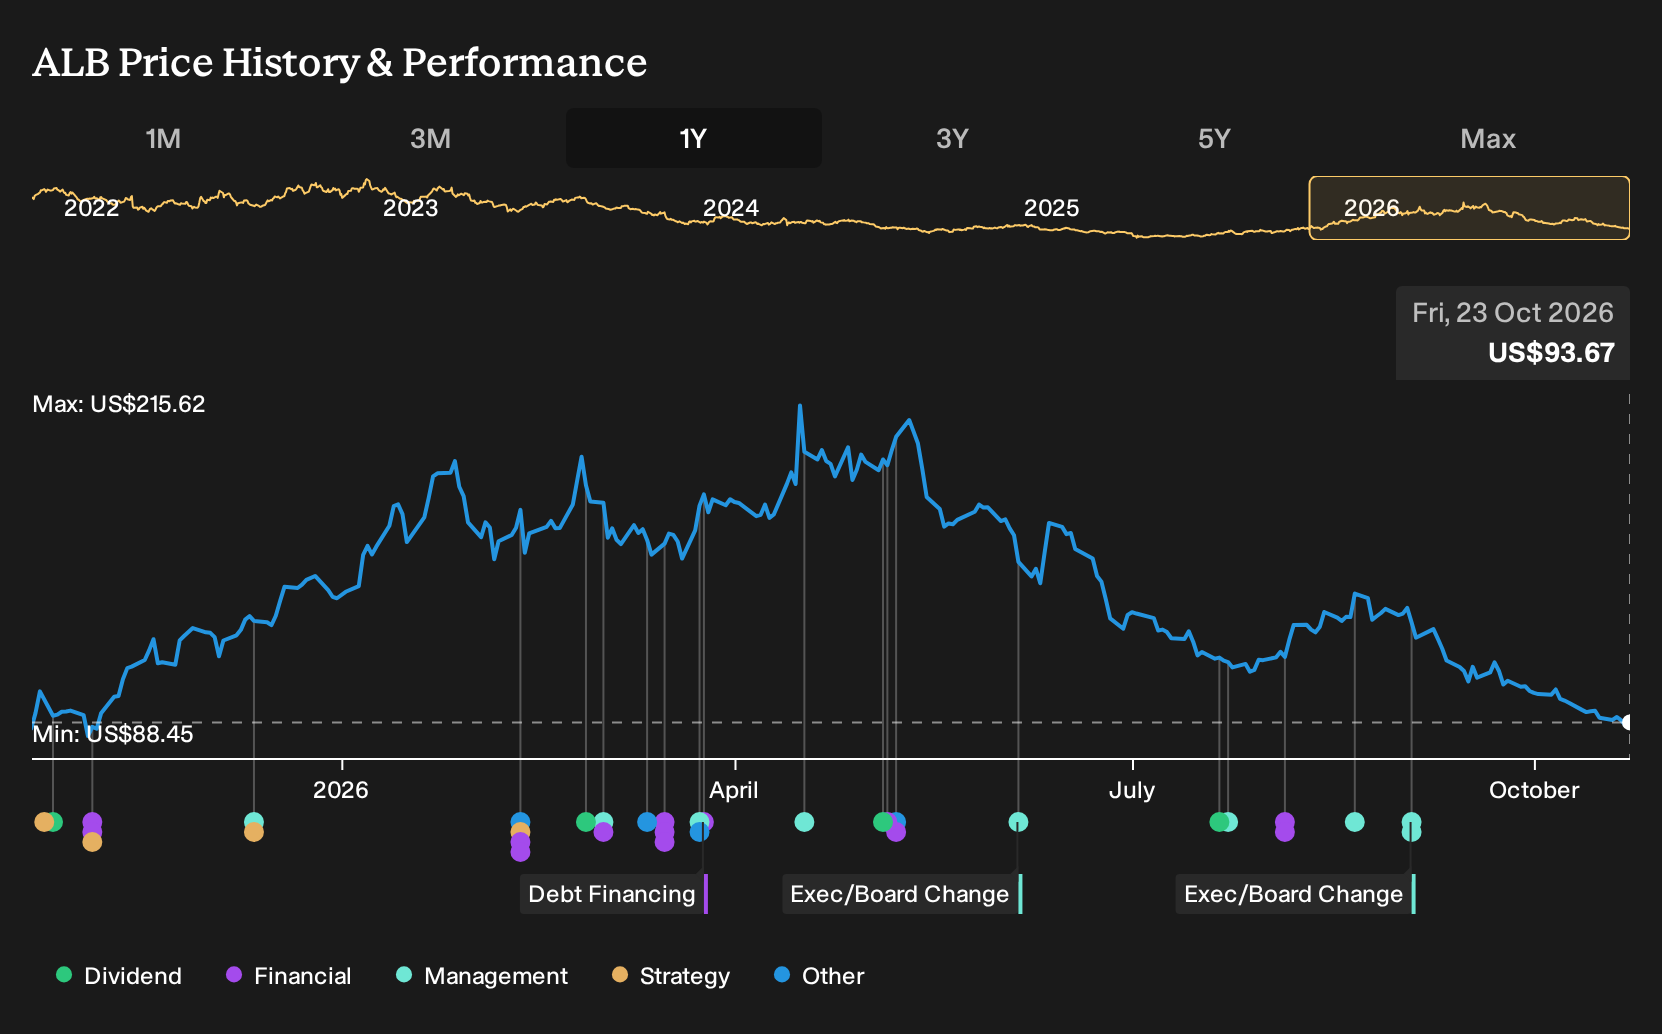
Exploring Other Perspectives
You might see Albemarle very differently if you worry about alternative battery tech. The most cautious analysts were modeling revenue of about US$5.2b and earnings of US$1.9b by 2029, which is well below the consensus path. Those forecasts came before this Q3 2026 update, so expect views to evolve as new data becomes available.
Explore 3 other Albemarle fair value estimates, including one that suggests it could be worth just $156.35!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Albemarle research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Albemarle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albemarle's overall financial health at a glance.
Looking For More Investment Ideas Beyond Albemarle?
If Albemarle has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you line up other opportunities that match your risk tolerance, income needs, or balance sheet focus in a few minutes.
- If capital preservation is high on your list, you could start with a basket of companies that screen as more resilient by reviewing 30 resilient stocks with low risk scores.
- If balance sheet strength matters most to you, filter for businesses with robust financial footing using the list of solid balance sheet and fundamentals (24 results).
- If you like finding earlier stage stories with room to grow, scan through the 21 high quality undiscovered gems and see which ones may deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com