


Is J. M. Smucker (SJM) Undervalued After Its Dividend Hike And 35% Run?
J. M. Smucker (SJM) announced updated income terms, with its Board approving a $1.12 per share dividend payable on December 1, 2026, to shareholders of record as of November 13.
The dividend decision comes after a strong run in the J. M. Smucker share price. The year to date share price return is 34.51% and the 1 year total shareholder return is 32.50%. The recent 1 day decline of 2.56% contrasts with a 30 day share price return of 7.42%, which indicates that momentum has been building over the medium term.
Scan how J. M. Smucker's dividend story compares with other income-focused opportunities by checking out the hand picked 5 dividend fortresses in today's market.
After a near 35% gain this year and a richer dividend on the table, J. M. Smucker now poses a harder question: Does the current price still leave enough potential reward for the risk you are taking?
Most Popular Narrative: 8.5% Undervalued
Compared with the last close at $129.98, the most followed narrative for J. M. Smucker points to a fair value of $142.13, which suggests the recent share price strength is still short of what that framework implies.
The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level while it continues to deleverage and manage the Hostess turnaround.
Sustained free cash flow around the US$1.1b to US$1.2b level, combined with leverage already at about 2.9x net debt to EBITDA, gives J. M. Smucker additional flexibility to keep reducing interest expense, consider future buybacks or reinvest behind high return brands, which can support future EPS growth.
See why 16 investors see J. M. Smucker as 9% undervalued.
Result: Fair Value of $142.13 (UNDERVALUED)
Still, the narrative relies on J. M. Smucker reversing pressure in Sweet Baked Snacks and avoiding a deeper FY27 sales decline than the 1% to 2% guidance.
Find out about the key risks to this J. M. Smucker narrative.
Another View On J. M. Smucker’s Valuation
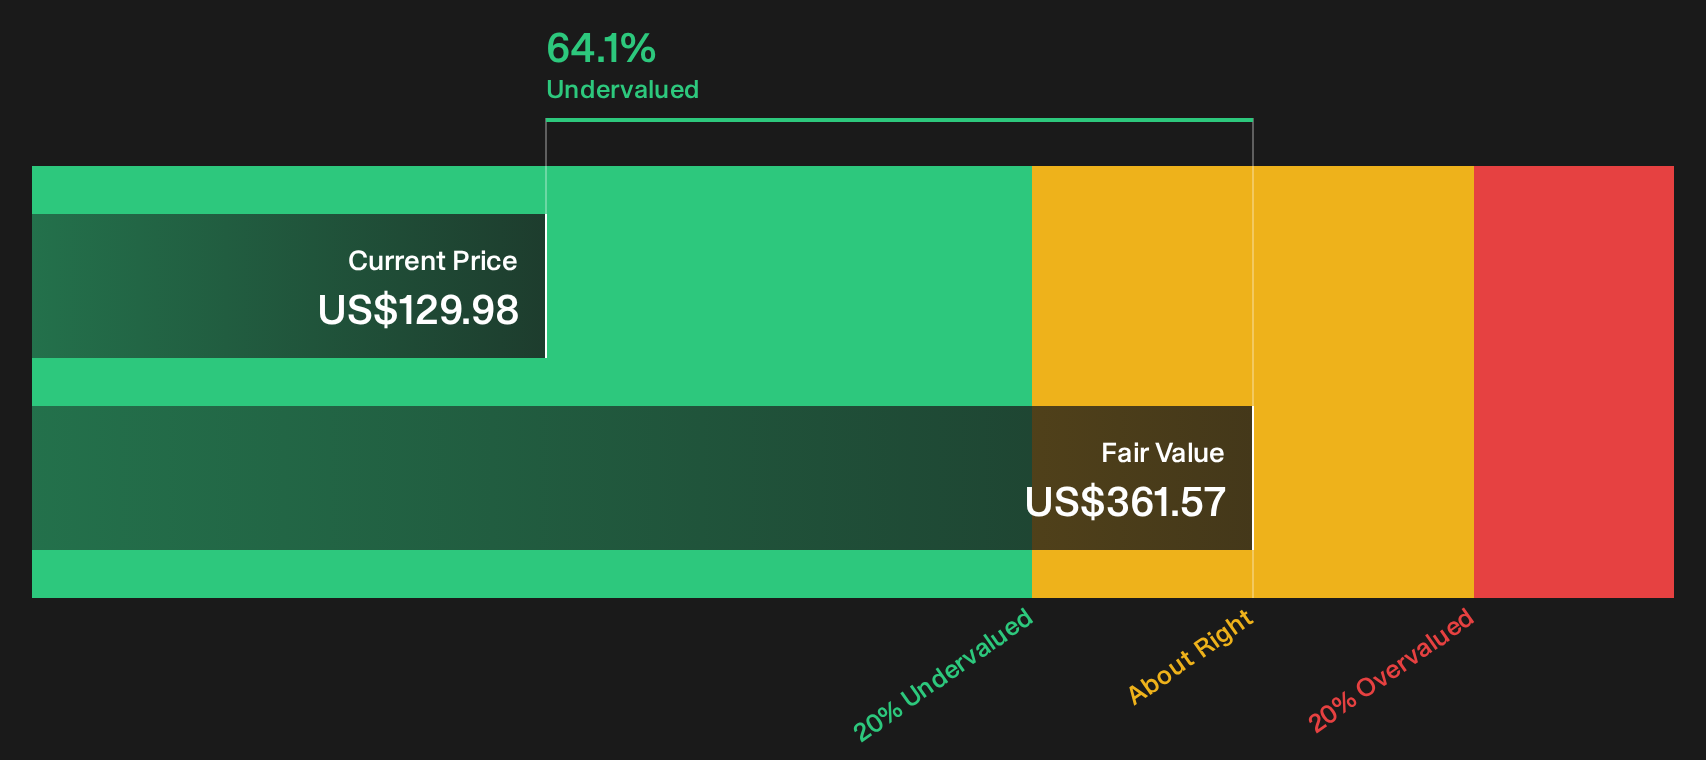
Analysts using the SWS DCF model see J. M. Smucker very differently from the 8.5% undervalued narrative. That approach values future cash flows at $361.57 per share, far above the current $129.98 price, which paints a picture of deep undervaluation. Which framework do you trust more when real cash is on the line?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals in the J. M. Smucker story. Weigh the income potential against the valuation debate, then move fast to test your own thesis with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond J. M. Smucker?
If J. M. Smucker has sharpened your thinking on income and value, broaden your watchlist now so you are not chasing the next move too late.
- Target steadier compounding by reviewing companies that score well on resilience and financial risk using the 30 resilient stocks with low risk scores.
- Hunt for compelling valuations by scanning the 29 high quality undervalued stocks that combine quality fundamentals with pricing that still looks reasonable.
- Spot early opportunities by sifting through the 21 high quality undiscovered gems where strong business foundations have not yet attracted wide attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com