


How Higher Rates At Charles Schwab (SCHW) Has Changed Its Investment Story
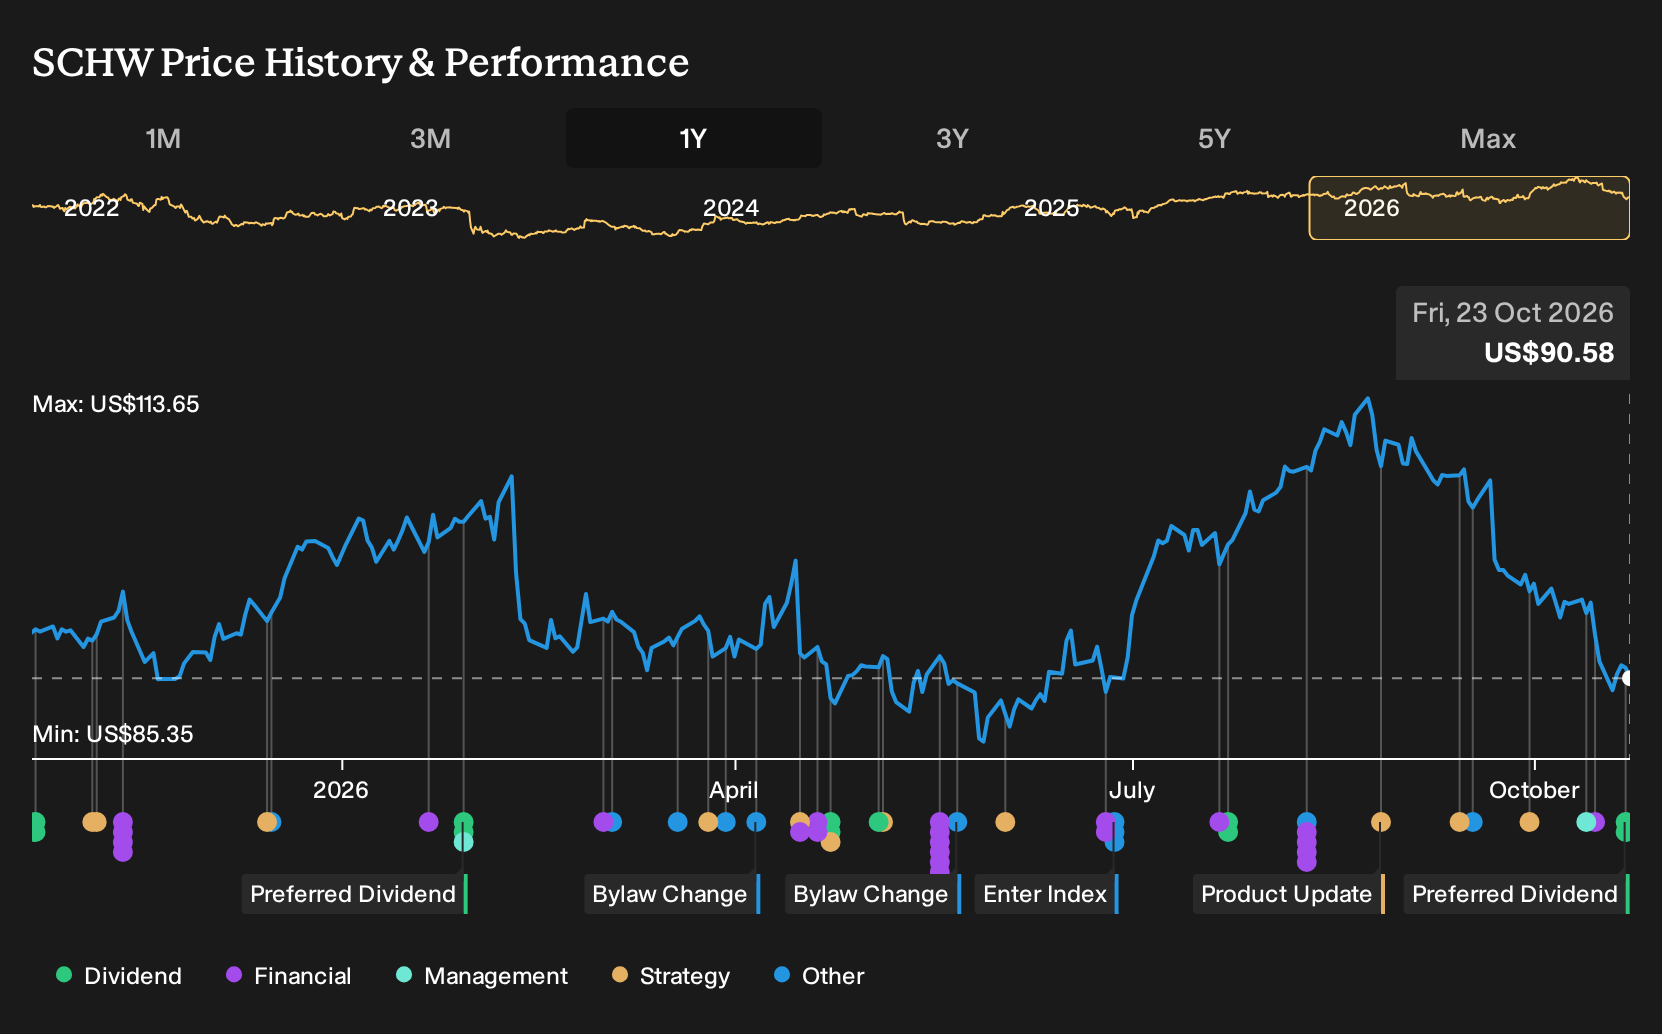
- Charles Schwab reported Q3 2026 net income of US$2.906b and regular quarterly common dividends of US$0.32 per share, alongside a series of preferred dividends across its D, F, H, J, K, and L preferred stock.
- The mix of higher earnings and ongoing capital returns highlights how Charles Schwab’s business model ties client cash balances and interest-sensitive revenue to board decisions on dividends.
- We will look at how Charles Schwab’s rate driven earnings profile and fresh dividend decisions feed into the broader investment narrative.
Charles Schwab Investment Narrative Recap
To own Charles Schwab, you need to be comfortable with a business that leans heavily on client cash, interest sensitive income, and scale driven efficiency. The latest quarter, with US$2.906b in net income and higher earnings per share, supports that rate driven engine. The recent dividend decisions look consistent with that backdrop and do not materially change the near term story.
The key short term swing factor still sits in how client cash mix evolves relative to sweep products, while expense growth stays in check as Schwab invests in technology and new offerings. The biggest risk remains cost creep and fee pressure outpacing revenue progress rather than anything seen in these announcements.
The regular US$0.32 quarterly dividend on common shares is the clearest data point for equity holders. It directly links recent earnings power with ongoing capital returns and gives you a live read on how comfortable the board is with Schwab’s cash generation and regulatory capital position right now.
That decision also fits into the wider catalyst narrative, where higher margin advice, lending and digital products are expected to carry more of the load over time, while Schwab keeps funding costs, fraud related exposures and technology spend under control. If you are tracking the stock, this dividend affirmation is one of the simpler markers to monitor alongside client activity and expense trends.
What The Charles Schwab Forecasts Are Really Assuming
Analysts are effectively asking you to judge Charles Schwab on a 2029 snapshot. Their models point to US$35.8b in revenue and US$15.4b in earnings by that year, based on 11.3% yearly top line growth assumptions and an earnings increase from US$9.7b today to US$15.4b, which is an increase of about US$5.7b.
Discover how Charles Schwab's fair value signals a 35% potential upside to its current price before other investors recognize and act on this opportunity.
Exploring Other Perspectives
One alternate Charles Schwab storyline leans on preferred equity risk. The most optimistic analysts had been pencilling in about US$40.2b of revenue and US$16.5b of earnings by 2029, which assumes heavy use of the balance sheet. You can see how this fresh round of preferred dividends might push those views even further in either direction.
Explore 3 other Charles Schwab fair value estimates, including one that suggests as much as 57% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charles Schwab research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charles Schwab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles Schwab's overall financial health at a glance.
Looking For More Investment Ideas Beyond Charles Schwab?
Once the Charles Schwab story is clear in your mind, the next step is to broaden your opportunity set so you are not relying on a single stock or theme. The Simply Wall St Screener helps you scan the market for companies that match your preferred mix of quality, resilience, and income potential in a structured way.
- If capital preservation sits near the top of your priorities, use the Screener to focus on 30 resilient stocks with low risk scores that may offer a calmer ride through market swings.
- If you prefer businesses with steady finances, filter for companies through a list of solid balance sheet and fundamentals (24 results) and review which ones line up best with your risk tolerance.
- If you enjoy searching for underfollowed stories, lean on the Screener to surface 21 high quality undiscovered gems that might not yet be widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com