


How Investors May Respond To CoreCivic (CXW) Earnings Beat
- CoreCivic recently reported earnings that came in ahead of expectations, with revenue growth running faster than sector peers and drawing attention to its detention and real estate platform.
- The company now trades at a premium P/E multiple compared with its sector, which suggests that investors place distinct value on its cash generation potential and federal contract exposure.
- This article will examine how CoreCivic’s investment narrative is being reshaped by its recent earnings results and comparatively faster revenue growth profile.
Look beyond CoreCivic's premium P/E and earnings beat to compare it with a handpicked 29 high quality undervalued stocks that may offer similar stories without the same valuation pressure.
CoreCivic Investment Narrative Recap
To stay comfortable as a CoreCivic shareholder, you need to believe the federal detention cycle and real estate platform can keep facilities busy and cash flowing, even if policy swings around funding and enforcement continue. The premium P/E and recent earnings beat both concentrate attention on whether occupancy, ICE detainee volumes and federal contracts can hold up.
Right now, the key near term swing factor is how federal funding decisions affect ICE and U.S. Marshals placements. A drop in detainee counts can quickly pressure utilization and margins. The biggest threat is that contracts are curtailed or repriced while the stock is already priced richly on a Fair Ratio basis.
The most relevant piece of context for this earnings beat is CoreCivic’s large real estate monetization, with about US$2.2b raised from selling four detention facilities to the government while keeping management contracts. That move put focus on how the business can recycle assets into cash while still relying on those locations for fee income.
This combination of cash proceeds, ownership of 56 specialized properties and remaining buyback capacity above US$700m gives management options on capital returns and debt reduction, even if operating trends level off. For you, the question is whether that financial flexibility offsets policy, funding and contract risk now embedded in a higher earnings multiple.
CoreCivic's current analyst script points to revenues of US$3.4b and earnings of US$516.8m by 2029, backed by assumed revenue growth of 11.6% a year and an earnings move of about 4x from US$127.9m today.
Uncover why CoreCivic's fair value indicates a 39% potential upside to its current price that could narrow quickly.
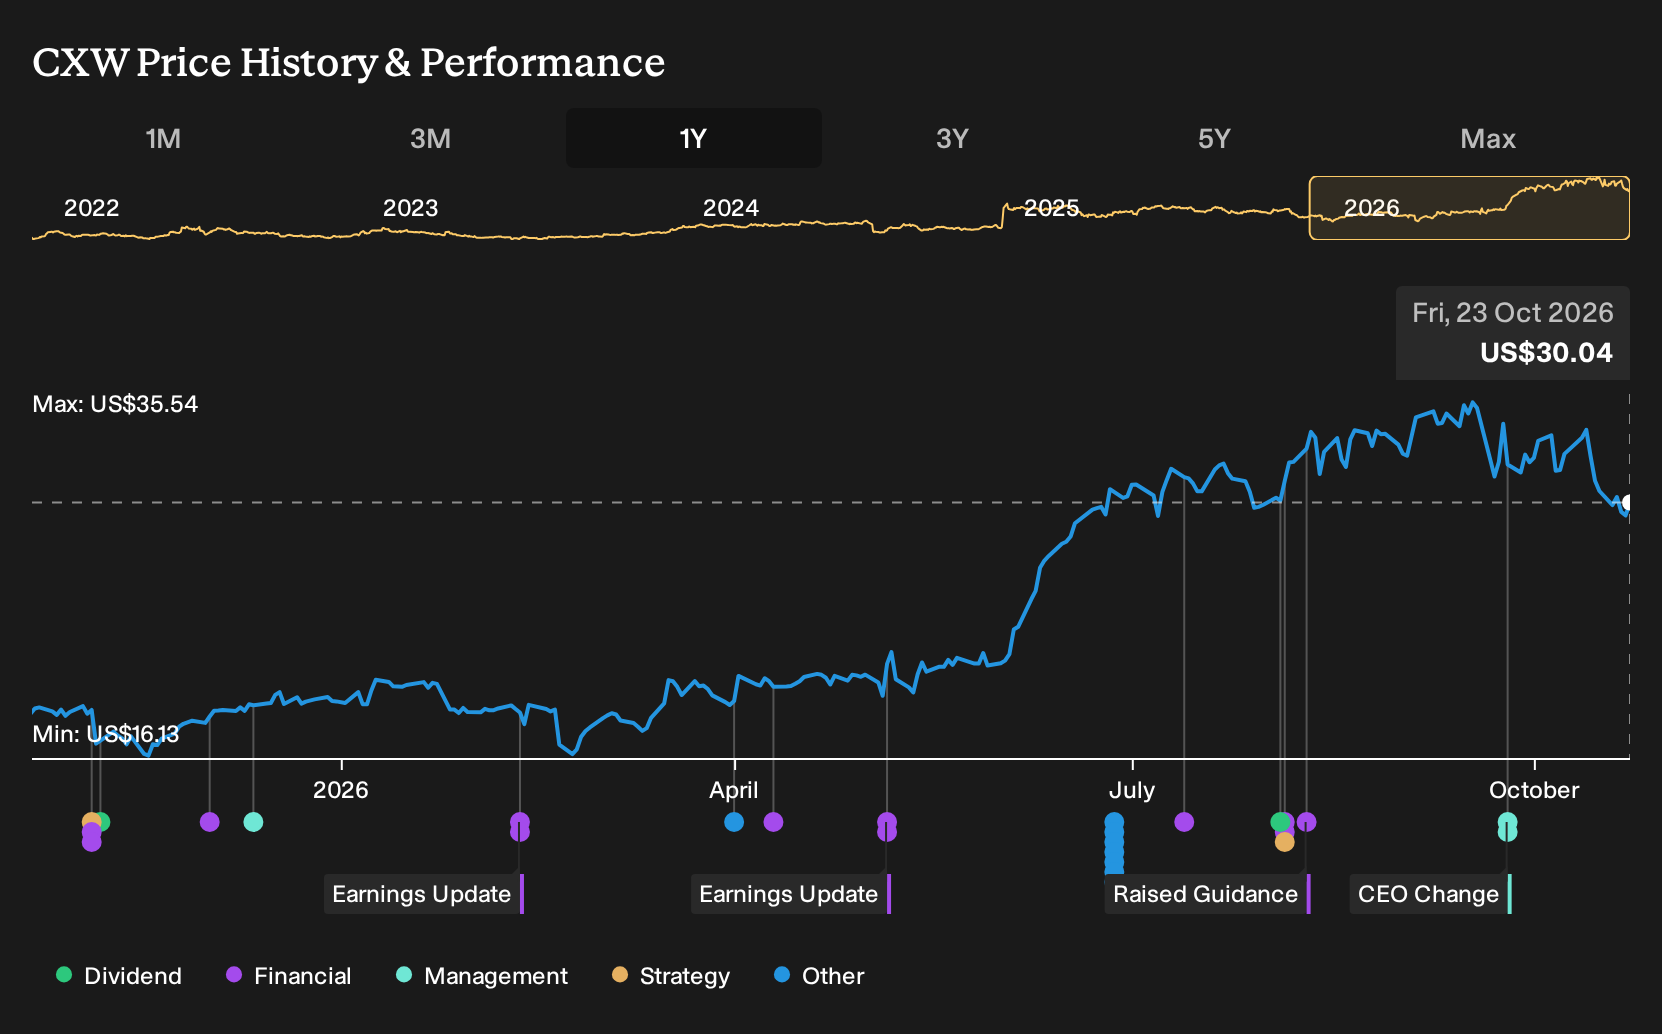
Exploring Other Perspectives
For CoreCivic, the bullish twist comes from idle capacity turning into a possible earnings engine. The most optimistic analysts were already pencilling in US$3.6b of revenue and US$162.1m of earnings by 2029, versus consensus at US$3.4b and US$516.8m. These forecasts pre date the latest earnings beat, so readers should anticipate that opinions may change and consider how both narratives might develop.
Explore 2 other CoreCivic fair value estimates, including one that suggests as much as 39% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your CoreCivic research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CoreCivic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which can help you evaluate CoreCivic's overall financial health at a glance.
Looking for more investment ideas beyond CoreCivic?
Once you have a view on CoreCivic, it can help to widen the lens and look for other companies with different risk and return profiles using the Simply Wall St Screener.
- If you want potential value without stretching on price, scan a curated 29 high quality undervalued stocks that combine quality fundamentals with lower implied expectations.
- For investors who care most about balance sheet strength, review a list of solid balance sheet and fundamentals (24 results) that may handle tougher conditions with fewer financial strains.
- Income focused readers can hunt for yield by checking a 5 dividend fortresses that aim to pair 5%+ payouts with resilient business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com