


FirstSun Capital Bancorp (FSUN) Draws Fresh Attention As Efficiency Improves But Is The Valuation Too Rich
Why FirstSun Capital Bancorp Is Back On Investors’ Radar
FirstSun Capital Bancorp (FSUN) is drawing fresh attention after reporting net interest income growth of 21.7% annually over five years, along with a 12 percentage point improvement in its efficiency ratio.
Recent trading has been constructive, with a 4.9% 7 day share price return and a 14.4% 90 day share price gain taking FirstSun Capital Bancorp to $39.81. However, the 1 year total shareholder return has slipped 1.6%, while the 3 year total shareholder return is up 35.6%, pointing to momentum rebuilding after a softer year.
Spot 29 high quality undervalued stocks that, like FirstSun Capital Bancorp, combine earnings power with improving efficiency ratios and may be setting up for the next leg of momentum.Bulls see FirstSun Capital Bancorp’s efficiency gains and net income growth as underpriced. Bears point to the softer 1 year return. Which story do the current valuation markers back up?
Price-to-Earnings of 39.7x: Is It Justified For FirstSun Capital Bancorp?
On the headline numbers, FirstSun Capital Bancorp looks expensive, with a P/E multiple of 39.7x against a last close of $39.81 and an estimated intrinsic discount of 42.9% from the SWS DCF model. That mix of a rich earnings multiple and a modelled gap to fair value is exactly what investors are debating.
The P/E ratio compares what you pay per share today to the earnings the bank generates per share. For a lender like FirstSun Capital Bancorp, this metric is central because profit levels can swing with credit costs, one off items, and the rate cycle, so a high P/E often implies the market is giving management credit for cleaner, stronger earnings ahead.
In this case, the current multiple sits far above both the peer group and the firm’s own fair ratio metric. FSUN is described as expensive on a 39.7x P/E versus a peer average of 13.6x and a US Banks industry average of 11.5x, and even compared to an estimated fair P/E of 28.3x the stock carries a premium. That signals investors are paying up relative to what the numbers imply the multiple could move toward, which leaves less room if earnings quality or growth forecasts do not play out as expected.
Explore the SWS fair ratio for FirstSun Capital Bancorp.
Result: Price-to-Earnings of 39.7x (OVERVALUED)
Still, if FirstSun Capital Bancorp’s earnings profile cools or the current 39.7x P/E multiple compresses toward banking peers, that momentum story can stall fast.
Find out about the key risks to this FirstSun Capital Bancorp narrative.
Another View On FirstSun Capital Bancorp’s Valuation
The P/E looks stretched, yet the SWS DCF model points in the opposite direction. On that framework, FirstSun Capital Bancorp at $39.81 is trading well below an estimated future cash flow value of $69.66, which frames the stock as undervalued on a cash generation basis. If earnings power normalises after recent one off items, which lens ends up closer to reality?
Look into how the SWS DCF model arrives at its fair value.
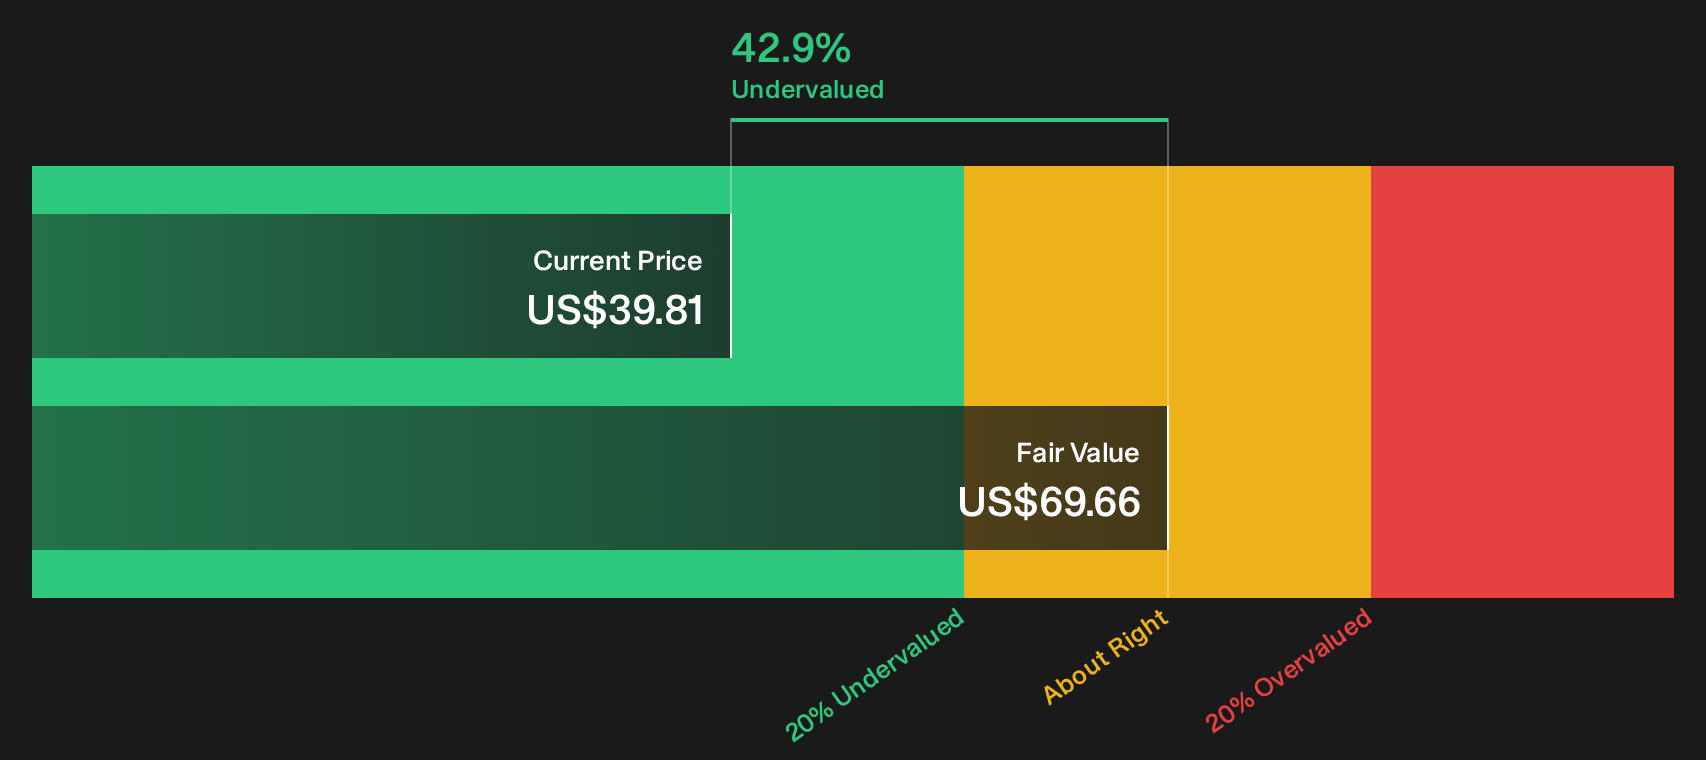
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstSun Capital Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on FirstSun Capital Bancorp leaving you unsure what to make of it. Act while the data is fresh and ground your own take in the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond FirstSun Capital Bancorp?
If FirstSun Capital Bancorp has sharpened your focus on bank valuations, do not stop here. Broader opportunities often emerge where pricing, quality, and resilience quietly line up.
- Target value opportunities early by scanning a curated 29 high quality undervalued stocks that highlights companies combining strong fundamentals with prices that screen below their implied quality.
- Prioritise resilience in rough markets by sifting through a 30 resilient stocks with low risk scores where balance sheets, earnings volatility, and risk scores are already filtered for you.
- Spot tomorrow’s potential leaders before the crowd by browsing a 21 high quality undiscovered gems built around smaller, fundamentally strong businesses that often sit off the usual radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com