


Is Earnings Beat Altering The Investment Case For Paychex (PAYX)?
- Paychex reported a stronger than expected fiscal Q1 2027, with earnings and revenue above estimates, supported by higher revenue per client, professional employer organization and insurance traction, and continued rollout of its WISE AI platform.
- Alongside the quarter, Paychex pushed deeper into AI driven services such as tax penalty protection and SixFifty’s agentic HR compliance tools, which shift complex payroll tax and employment law work from small businesses to the company’s own systems and specialists.
- We will now look at how Paychex's PEO and insurance outlook, supported by WISE AI, may influence its investment narrative.
Scan how Paychex is leaning on AI driven payroll and compliance tools, then compare it with hand picked peers in 55 AI infrastructure stocks to see which platforms may be building durable advantages.
Paychex Investment Narrative Recap
To be a shareholder in Paychex, you need to believe its human capital management model can keep shifting clients into higher value PEO and insurance offerings while WISE AI wrings more efficiency out of payroll and tax workflows. The recent Q1 beat and higher PEO and Insurance Solutions revenue outlook support that operating thesis. The key near term swing factor is whether AI driven productivity and mix shift can offset softer Management Solutions growth and pressure from lower interest income on client funds.
The biggest current risk is execution. Integrating Paycor, aligning products across customer sizes, and scaling AI tools without service hiccups all need to work cleanly. If cross selling into the Paycor base, ASO to PEO upgrades, or WISE adoption stall, the margin and earnings trajectory that underpins the Paychex story becomes harder to sustain.
The Paychex Tax Penalty Protection Service powered by WISE looks tightly linked to that thesis. It takes a complex, recurring pain point payroll tax issues and centralizes it inside Paychex’s systems and specialists. That creates a clearer value proposition for Paychex Flex customers and could support retention if the service consistently resolves issues and absorbs eligible penalties as advertised.
For catalysts, this product matters because it turns AI in the back office into something visible and concrete for clients. Strong uptake would reinforce the idea that WISE can both reduce manual work and justify richer service bundles alongside PEO and insurance. The risk is straightforward. If error resolution is slower or costlier than expected, the benefit to margins from AI and PEO mix shift could be harder to realize.
Paychex's narrative projects US$7.7b revenue and US$2.4b earnings by 2029. This implies 5.2% yearly revenue growth and an earnings increase of about US$600m from US$1.8b today.
Uncover why Paychex's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
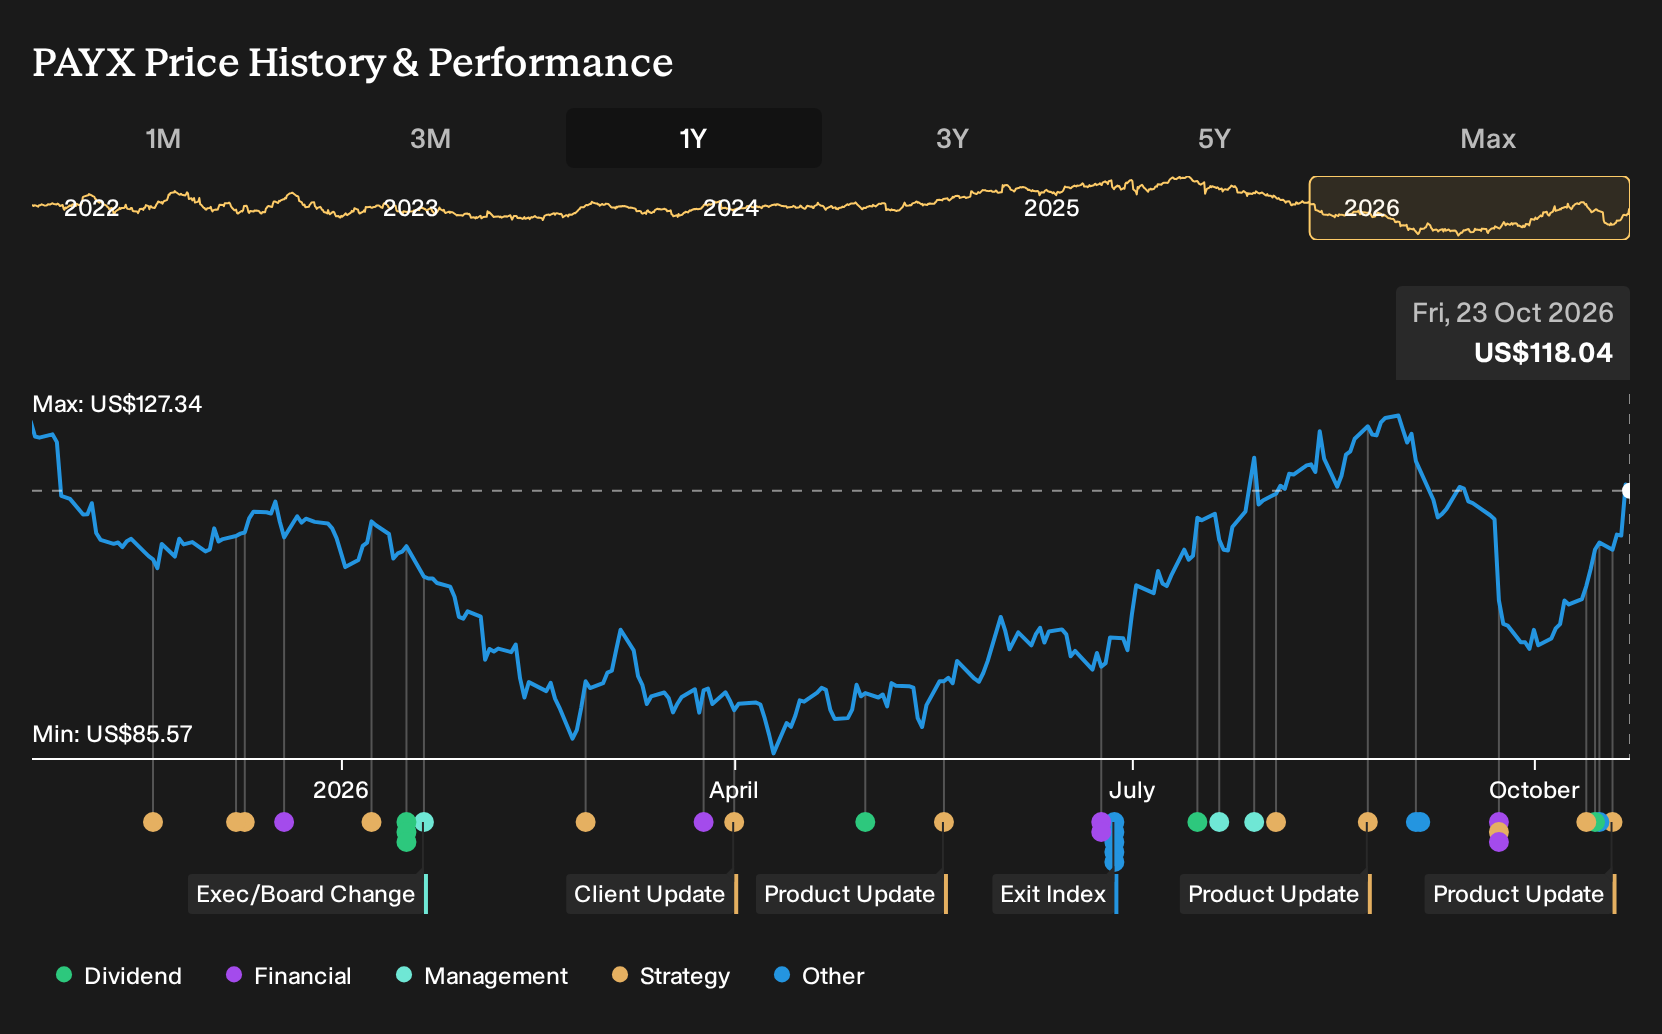
Exploring Other Perspectives
One alternate view focuses on Paychex interest income rather than AI. The most cautious analysts were assuming earnings of about US$2.3b on roughly US$7.6b of revenue by 2029 and a lower 17.3x P/E. That group sees slower benefit from WISE and Tax Penalty Protection. Use this spread in expectations as a prompt to compare several narratives for yourself.
Explore 3 other Paychex fair value estimates, including one that suggests it could be worth just $113.93.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paychex research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paychex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paychex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Paychex?
If the Paychex story has sharpened your thinking about quality, risk and forecast assumptions, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who want strong balance sheets and resilient fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can better withstand bumps in the cycle.
- If dependable income is your priority, zero in on companies in 5 dividend fortresses that combine elevated yields with an emphasis on sustainability.
- To widen the opportunity set beyond widely followed large caps, hunt through 21 high quality undiscovered gems that pair solid business quality with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com