


How Investors May Respond To NiSource Stock Microsoft Power Deal
- In October 2026, NiSource, through its NiSource Generation Company subsidiary, signed a 20 year energy agreement to supply Microsoft's planned northwest Indiana data center campus using about 1,100 MW of new generation capacity and 600 MW of contracted battery storage, fully funded by Microsoft.
- The structure keeps existing NIPSCO customers insulated from incremental data center costs. Management expects about US$1.75b of total electric bill savings, or up to US$140 per customer annually, highlighting how large-load contracts could change NiSource's customer economics.
- We will now examine how NiSource's investment narrative could shift as Microsoft fully funds this long term data center power buildout.
Scan how the NiSource data center deal compares with other grid and infrastructure beneficiaries by reviewing our curated list of 42 power grid technology and infrastructure stocks.
NiSource Investment Narrative Recap
To own NiSource, you need to be comfortable with a regulated utility that is leaning hard into large power users while still running a sizeable gas distribution footprint. The Microsoft agreement reinforces that story. It supports NiSource’s plan to grow its GenCo platform without shifting costs onto existing NIPSCO customers, which was already a key part of the thesis.
The near term swing factor still looks like regulatory and cost outcomes around that US$28.6b long term capital plan, not this single contract. The main risk does not change much. Heavy spending, equity issuance of US$400m to US$600m a year, and interest coverage that is already tight keep the balance sheet and rate decisions front of mind.
The most relevant reference point for this Microsoft deal is NiSource’s earlier GenCo agreements with Amazon and Alphabet. Those contracts were expected to deliver about US$1.4b of bill reductions for existing customers and helped prove regulators would support data center load if households clearly benefited.
Today’s announcement raises that expected NIPSCO customer savings to roughly US$1.75b and adds long dated visibility on 1,100 MW of new GenCo capacity plus 600 MW of battery storage. For you as an investor, the question is execution. NiSource has to deliver these projects on time and on budget, while managing leverage, regulatory scrutiny of gas capex, and union and storm related operating costs that have already pressured margins.
Analysts sketch a path where NiSource's revenue reaches US$8.4b and earnings reach US$1.3b by 2029, based on 6.9% yearly revenue growth and an earnings increase of about US$394m from US$906.0m today.
Uncover why NiSource's fair value indicates a 13% potential upside to its current price that could narrow quickly.
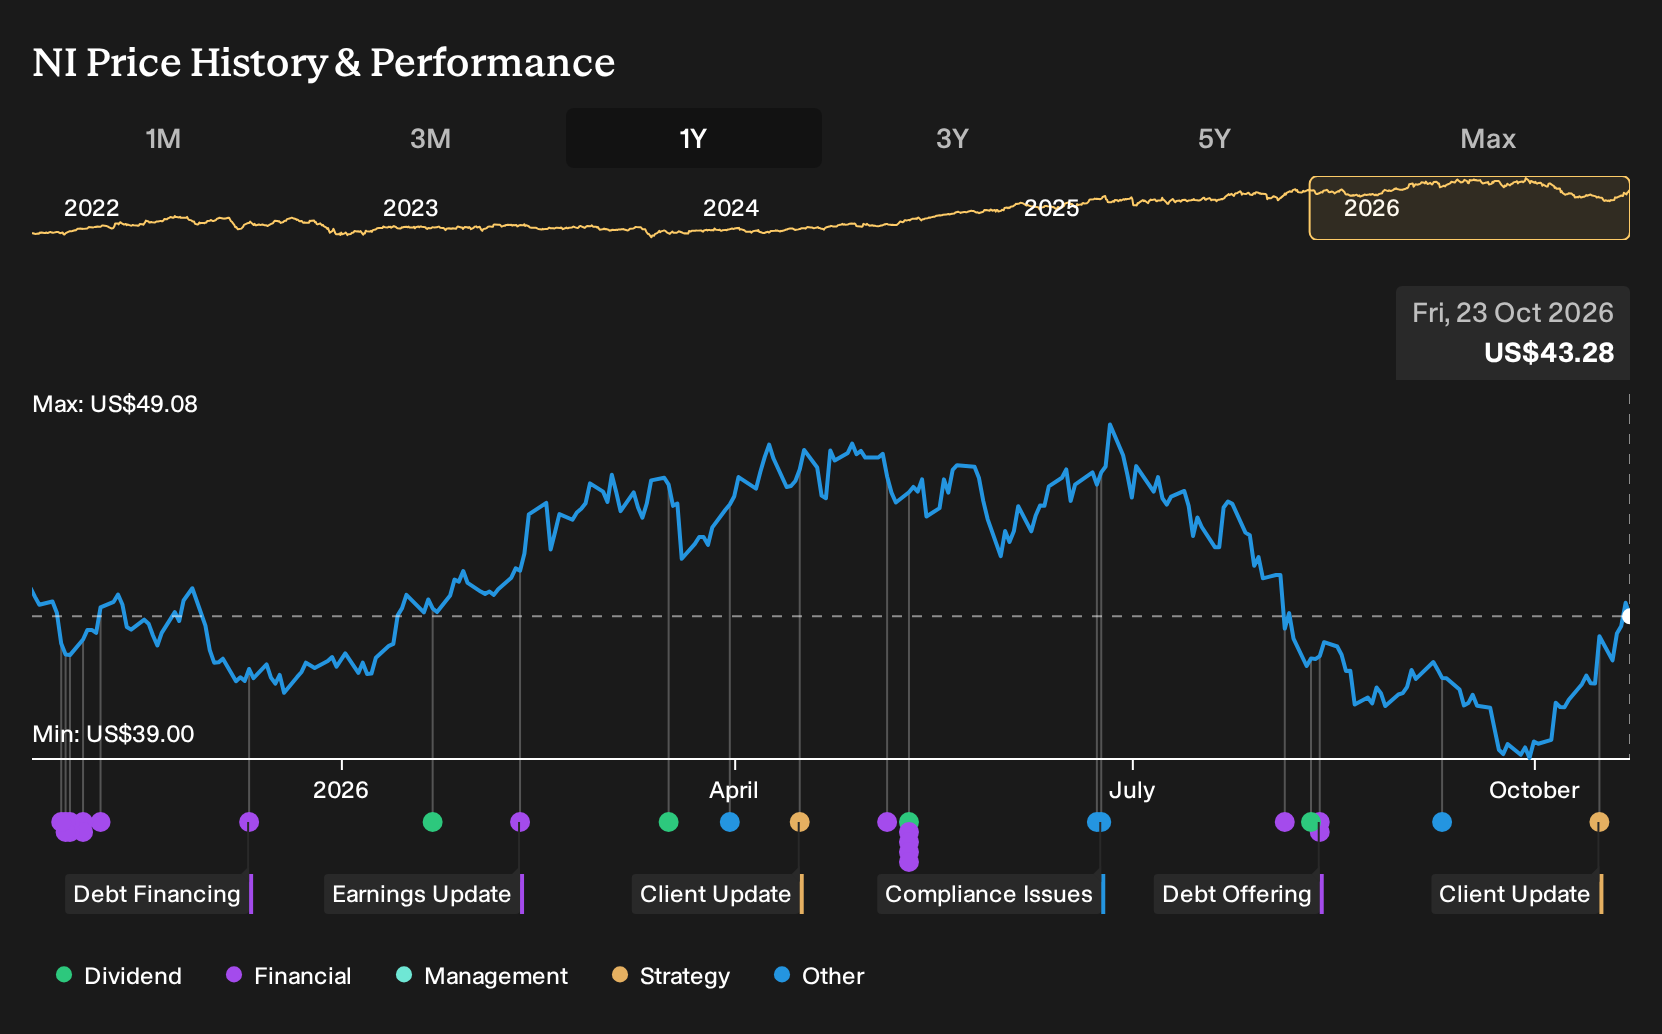
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$35.8 and US$48.7 per share, so private investors already span a wide gap on what NiSource is worth. When you add the Microsoft data center contract, as well as long term gas transition and funding risks, you get a story where opinions can diverge sharply. Explore those competing angles before deciding how NiSource fits in your portfolio.
Explore 2 other NiSource fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NiSource research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NiSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NiSource's overall financial health at a glance.
Looking for more investment ideas beyond NiSource?
Once you have a view on NiSource, it helps to set it against a broader watchlist of potential opportunities that fit different portfolio roles. The Simply Wall St Screener can point you toward very different types of businesses so you can balance quality, risk, and income in a way that matches your goals.
- If you want stability at the core of your holdings, start with a 30 resilient stocks with low risk scores that have more resilient financial and risk profiles.
- For investors who care about balance sheet strength and fundamentals first, compare NiSource with a list of solid balance sheet and fundamentals (24 results) that pass stricter quality filters.
- If you are hunting for less crowded opportunities, widen the search to a 21 high quality undiscovered gems that combine stronger metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com