


How Investors May Respond To Boyd Gaming (BYD) Weaker Q3 Profit
- Boyd Gaming reported Q3 2026 results with revenue of US$990.46 million and net income of US$124.93 million, alongside ongoing property upgrades and significant capital returns through buybacks and dividends.
- The sharp year on year drop in earnings, driven by the absence of last year’s large one off gain and softer Las Vegas destination business, contrasts with continued growth in Midwest, South and online operations, as well as a sizeable development pipeline led by the Norfolk resort.
- This article examines how Boyd Gaming’s investment narrative is affected by weaker Las Vegas trends alongside its Norfolk and online growth initiatives.
Scan the casino and entertainment space beyond Boyd Gaming by spotting other operators with similar renovation and capital return stories using our hand-picked 29 high quality undervalued stocks.
Boyd Gaming Investment Narrative Recap
To own Boyd Gaming, you need to believe the capex program, Norfolk resort and online joint ventures can offset softer Las Vegas destination trends and thinner net margins after the large one off gain in 2025. In the short term, the key swing factor is how quickly Las Vegas demand and renovated properties stabilise relative to the current construction disruption.
The biggest risk right now is that weaker destination play and ongoing projects like the Suncoast modernization and other refreshes weigh on EBITDAR for longer than expected and constrain free cash flow. The latest quarter confirms pressure on profit, but does not yet change the longer term capex and online growth narrative.
The most relevant update here is Boyd Gaming’s Q3 2026 result, which showed revenue of US$990.46 million and net income of US$124.93 million, down sharply from a prior period that was boosted by a large one off gain. That reset makes it easier to judge how the underlying casino, online and managed businesses are actually performing.
For catalysts, investors are watching how this earnings base interacts with the multi year capex pipeline, including the US$750 million Norfolk resort and the expanding online operations that delivered double digit growth after the FanDuel transaction. Execution risk is significant given construction disruption and softer Las Vegas properties, so progress at Norfolk and online EBITDAR delivery remain key markers.
What The Current Forecasts Say About Boyd Gaming
Analysts are effectively baking in a smaller but still profitable Boyd Gaming by the end of the decade, with softer Las Vegas trends and slimmer margins balanced against Norfolk, online growth and ongoing capital returns. The story is less about rapid expansion and more about how much earnings and cash flow the existing and planned asset base can support once the current investment cycle settles down.
Boyd Gaming's narrative projects US$4.4 billion revenue and US$206.6 million earnings by 2029. This assumes 2.4% yearly revenue growth and an earnings decrease of about US$1.6 billion from the US$1.8 billion of earnings today.
Those estimates sit alongside a sizeable shift in profitability. Analysts are pencilling in profit margins moving from 44.3% today to 4.7% in three years, which effectively recasts the group as a much lower margin operator that leans more on steady local gaming, managed fees and online income than on large destination wins or outsized one off gains.
On these numbers, the equity story depends heavily on what investors are willing to pay for those future earnings. Consensus assumes Boyd Gaming trades on a P/E of 35.1x by 2029 compared with 2.9x today and against a current US Hospitality sector multiple of 19.4x. This implies that the market would need to treat the stock as a premium asset even while underlying earnings are expected to be lower.
The same forecasts also rely on a shrinking share count to support per share metrics. Analysts expect the number of shares outstanding to fall by about 7.0% per year over the next three years. This lines up with the current mix of buybacks and dividends and helps explain how earnings per share can remain meaningful even with lower absolute profit.
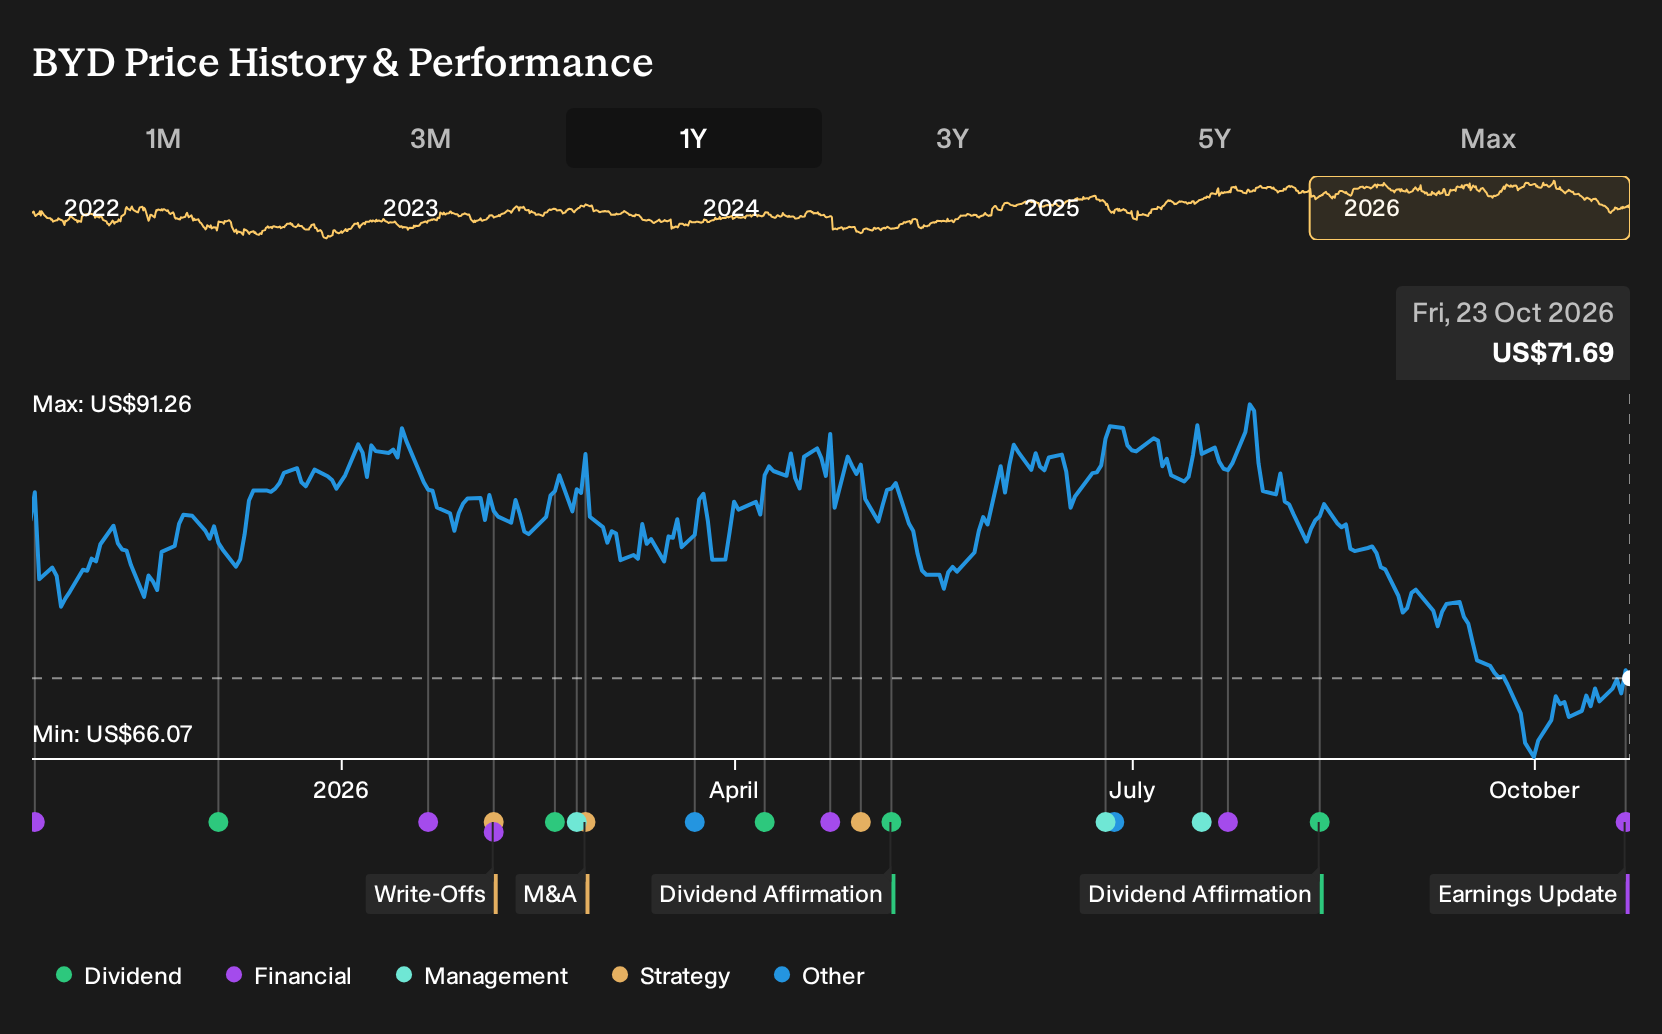
Pull this together and you get a fairly demanding setup. The implied fair value math uses a discount rate of around 10.2% to justify a consensus price target of US$92.75, which is 22.8% above the current US$71.62 share price, and rests on revenue of US$4.4 billion and earnings of US$206.6 million in 2029 at that higher P/E multiple.
For you as an investor, the task is to stress test those building blocks. That means asking whether a revenue growth rate of 2.4% a year, a large step down in profit margins, a higher future valuation multiple and continued share count reduction all feel realistic against what you know about Boyd Gaming's Las Vegas exposure, Norfolk build out, online partnerships and capital return track record.
Uncover how Boyd Gaming's fair value indicates a 29% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Simply Wall St Community members offer three fair value views for Boyd Gaming, ranging from 0.39x to 116.53x, which highlights how far apart retail expectations can be. You are weighing those against risks such as prolonged construction drag and softer Las Vegas demand, as well as catalysts like Norfolk, Sky River and online fees. Consider exploring all three viewpoints before deciding how Boyd Gaming fits your own thesis.
Explore 2 other Boyd Gaming fair value estimates, including one that suggests as much as 99% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boyd Gaming research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Boyd Gaming. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boyd Gaming's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boyd Gaming?
If Boyd Gaming has helped clarify what you want from a casino or leisure stock, the next step is to line it up against a wider watchlist. Use the Simply Wall St Screener to quickly surface other opportunities that fit your preferred mix of quality, income and risk.
- For investors who care most about resilient balance sheets and consistent fundamentals, start by scanning our list of solid balance sheet and fundamentals (24 results) to see which businesses match that profile.
- If downside protection matters to you as much as upside potential, narrow your focus to companies that score well on resilience by checking out the 30 resilient stocks with low risk scores that filters for sturdier profiles.
- When you want to unearth lesser known opportunities with strong underlying numbers, broaden your search through the 21 high quality undiscovered gems that highlights underfollowed stocks with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com