


How Investors May Respond To Bunge Stock Ahead Of Earnings And Viterra Integration
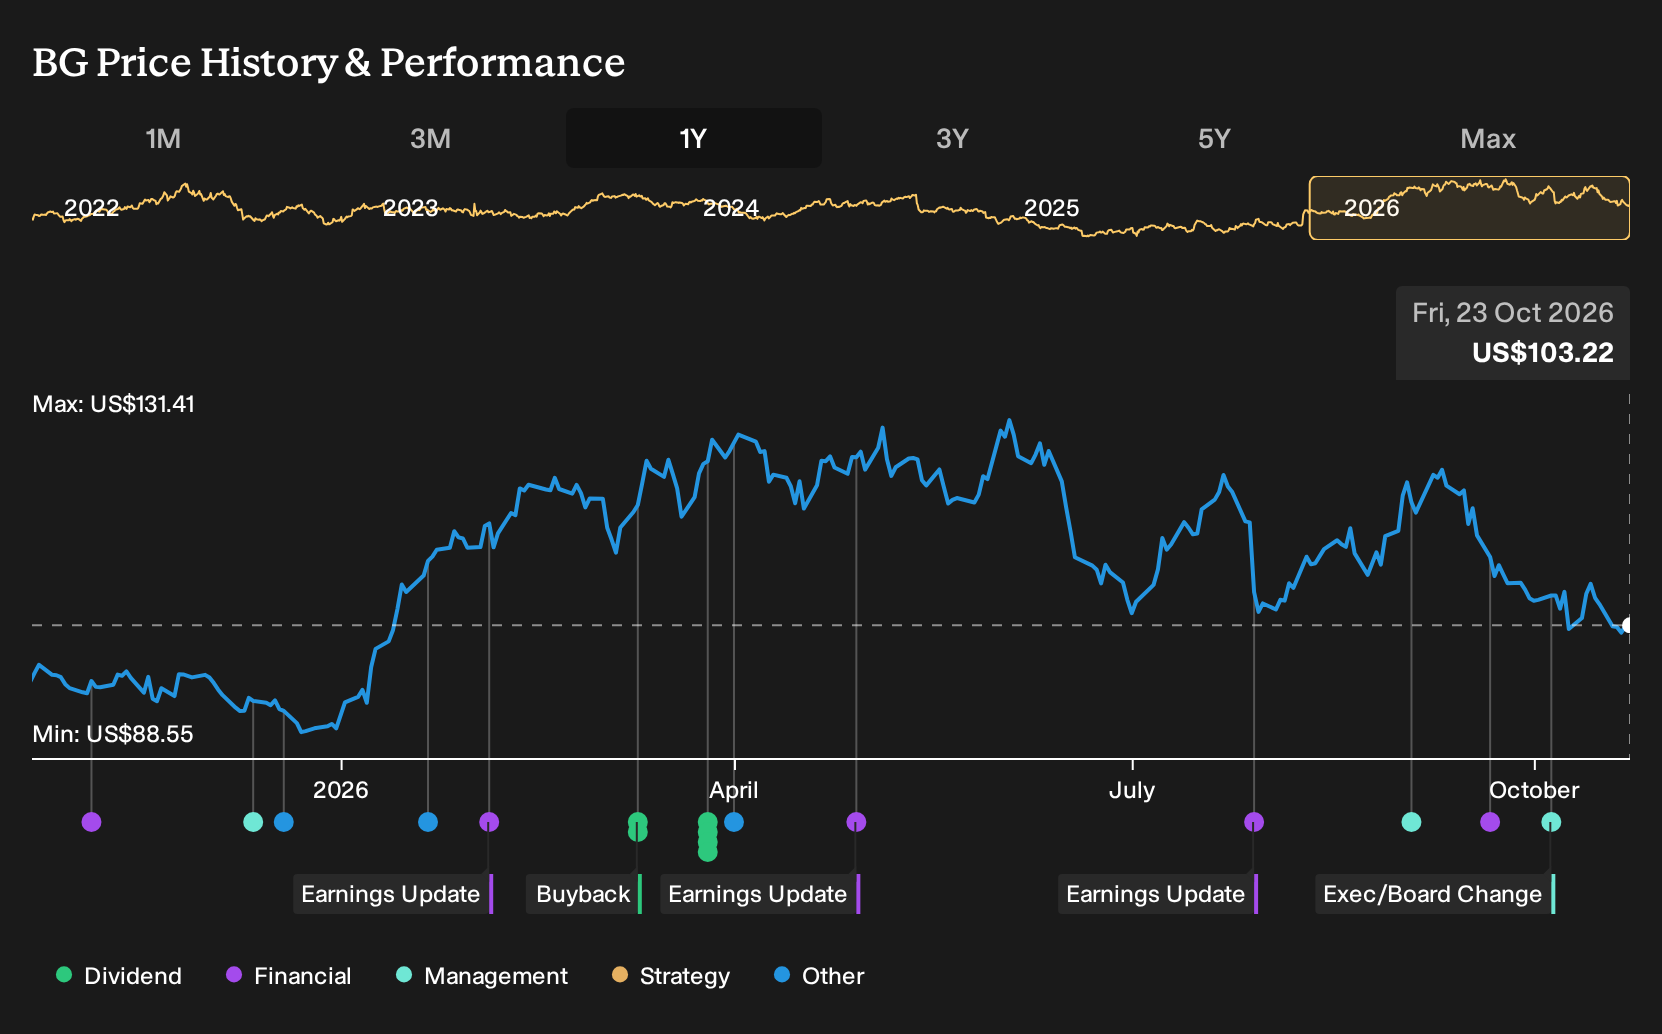
- Bunge Global recently moved closer to its next quarterly earnings release, with investors focused on how revenue, earnings and segment trends will appear in the reported numbers.
- The integration of the Viterra merger is in the spotlight as management works to capture cost savings while addressing softness in refined and specialty oils and some merchandising activities.
- We will now look at how Bunge Global's investment narrative lines up with the Viterra integration story and the pending earnings update.
Bunge Global Investment Narrative Recap
Bunge Global appeals to shareholders who buy into a fairly simple idea. A large, diversified agribusiness with meaningful processing capacity and a growing global footprint can convert steady demand for food, feed and fuels into consistent earnings, even when individual segments wobble. The near term hinge is whether Viterra integration and project ramp ups show through in cleaner, higher quality profit, not just headline volume.
The biggest swing factor right now is execution on that integration against pockets of weakness in refined and specialty oils and Grain Merchandising and Milling. If those softer areas do not stabilize, they can dilute any operating gains and keep margins tight. In the short term, the key risk is that higher leverage and thin free cash flow limit flexibility if cash generation disappoints.
The Viterra merger sits at the center of this current update for Bunge Global because it touches almost every operating line. Management is working to extract cost and commercial synergies while layering Viterra’s origination and logistics footprint onto Bunge Global’s processing network. Earnings day will help investors judge whether this enlarged platform is starting to translate into better segment balance and more resilient returns.
This deal also links directly to the main risks. Higher debt, weaker coverage from operating cash flow and a dividend that is not well supported by free cash flows all raise the stakes if integration is slower or merchandising stays soft. For anyone watching catalysts, the combination of synergy delivery, cash conversion and leverage trends is likely to matter more than short term share price reactions around the quarter.
Bunge Global's current analyst narrative points to US$95.3b in revenue and US$3.4b in earnings by 2029, based on an assumed 1.2% yearly revenue growth rate and an increase of about US$2.4b in earnings from the US$1.0b level today.
Uncover why Bunge Global's fair value indicates a 37% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Viterra synergies as the real swing factor for Bunge Global, not the current earnings run rate. Before this news, the bullish camp was modeling revenue of about US$97.5b and earnings of roughly US$3.5b by 2029. You can treat that as one possible path and compare it with more cautious views that may shift once the latest update lands.
Explore 3 other Bunge Global fair value estimates, including one that suggests potential upside of as much as 264% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bunge Global research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bunge Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bunge Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bunge Global?
After forming a view on Bunge Global, it can help to widen your watchlist and compare it with other businesses that have different risk and return profiles. The Simply Wall St Screener gives you a structured way to do that in a few minutes.
- If you prefer potential mispricing opportunities backed by solid fundamentals and want a focused starting list to review, then scan our curated set of 29 high quality undervalued stocks.
- If your priority is stability and balance sheet strength, you can narrow in on companies with lower financial risk by reviewing a 30 resilient stocks with low risk scores.
- For investors who want lesser known ideas with strong fundamentals, you can cast a wider net across 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com