


Hanover Insurance Group (THG) Could Be Fully Valued Following Better Earnings Sentiment
Hanover Insurance Group (THG) is back on traders’ screens after reaching a new 52-week high and posting a roughly 9.9% gain over the past month, in line with improving earnings sentiment.
In the short term, Hanover Insurance Group has carried solid momentum, with a 30-day share price return of 9.3% and a year-to-date return of 32.8% at a share price of US$237.73. At the same time, the 1-year total shareholder return of 38.7% and 3-year total shareholder return of 122.5% indicate a much stronger longer-term performance for investors than the recent quarter alone might suggest.
Scan beyond Hanover Insurance Group and review a handpicked 30 resilient stocks with low risk scores that have shown resilience similar to this insurer’s recent run to new highs.
Hanover Insurance Group now appears to be a solid operator priced for perfection after its sharp move and strong returns. The key question is whether the current valuation still offers a reasonable entry point for new money.
Most Popular Narrative: 20% Undervalued
On the most followed view, Hanover Insurance Group screens as undervalued, with a fair value estimate of $238.25 against the recent $237.73 share price. That leaves only a small price gap, so the real focus shifts to how the business executes on the plan that underpins that appraisal.
Disciplined capital management, supported by an affirmed A financial strength rating, a long record of dividend growth, and a new US$700m share repurchase authorization expected to run for several years, is aligned with long-term targets for mid to high teens operating ROE and around 10% growth in operating EPS and book value. This can help sustain earnings per share and capital return metrics already reflected in the current valuation.
See why 8 investors see Hanover Insurance Group as 0% undervalued.
Result: Fair Value of $238.25 (UNDERVALUED)
Still, Hanover Insurance Group faces two pressure points that could upset this fair value story: slower Specialty premium momentum and any reversal in recent catastrophe loss trends.
Find out about the key risks to this Hanover Insurance Group narrative.
Another View: Hanover Insurance Group On Earnings Multiples
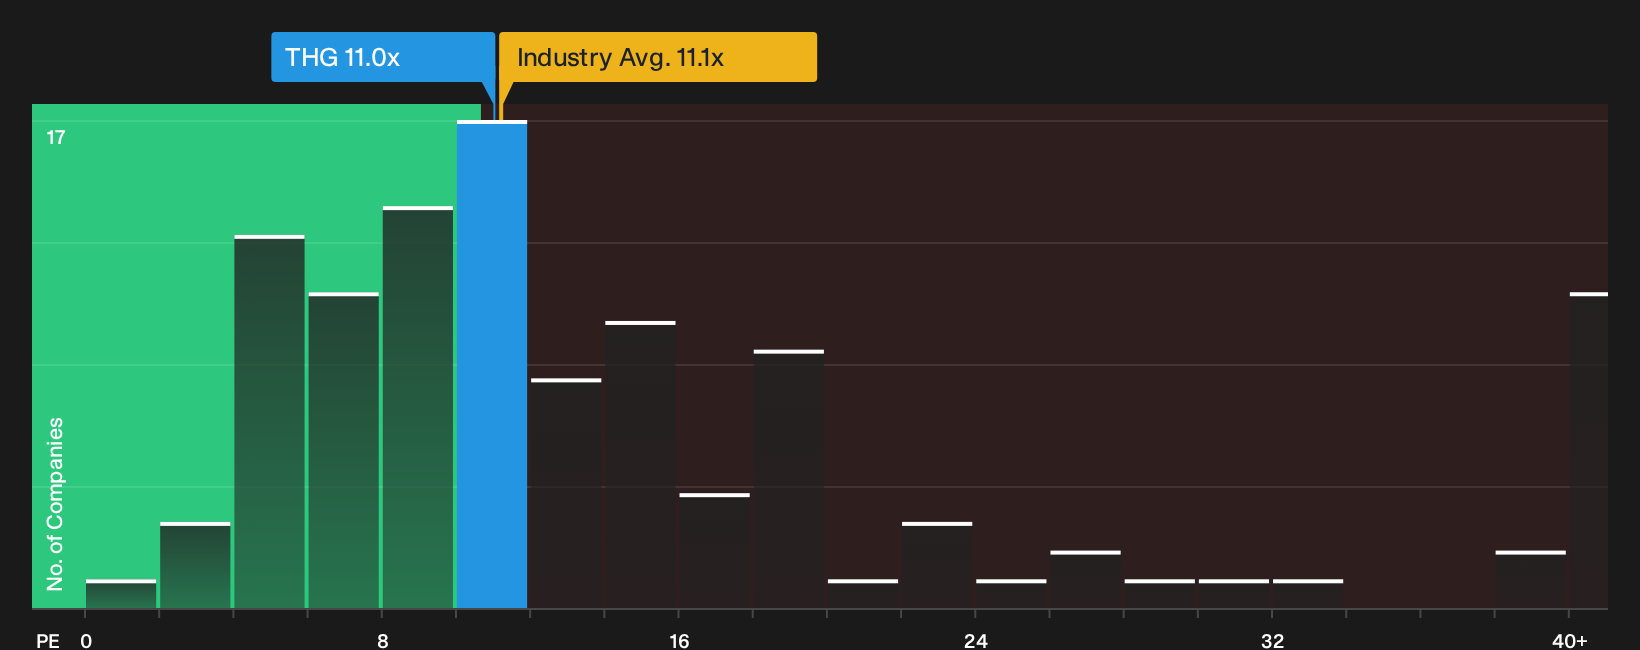
The story changes when you move from fair value models to simple earnings-based pricing. Hanover Insurance Group trades on a P/E of 11x, which is roughly in line with the US Insurance industry at 11.1x, yet above its own fair ratio of 9x that our work points to.
That gap suggests investors are paying a premium to recent fundamentals, while analyst forecasts point to earnings that are expected to decline by an average of 4.7% per year over the next 3 years. The question for you is whether that extra multiple is a fair price for the risks already on the table, or a margin of safety that is shrinking in real time.
See what the numbers say about this price in our valuation breakdown, then compare it with peers to pressure test your own view See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hanover Insurance Group is split between optimism on rewards and caution on risks, so move quickly, review the numbers yourself, and pressure test both sides through the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hanover Insurance Group?
If Hanover Insurance Group has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted ideas that match different investing goals.
- Target resilience by scanning a 30 resilient stocks with low risk scores that may help cushion your portfolio when conditions turn choppy.
- Hunt for quality at a discount through a 29 high quality undervalued stocks that can surface companies where price and fundamentals look out of sync.
- Build a reliable income stream by reviewing a 5 dividend fortresses designed for investors who want yield without losing sight of financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com