


Is Tokyo Electric Power Company Holdings (TSE:9501) Undervalued After Its Fresh Fukushima Grant?
Tokyo Electric Power Company Holdings (TSE:9501) has secured a fresh ¥5.0b grant from the Nuclear Damage Compensation and Decommissioning Facilitation Corporation, supporting upcoming Fukushima related compensation payments and keeping liquidity in focus for investors.
The fresh grant lands while Tokyo Electric Power Company Holdings' share price has eased, with a 30 day share price return of a 4.83% decline, a year to date share price return down 30.36%, and the 1 year total shareholder return down 33.24%. However, the 5 year total shareholder return remains positive at 58.73%, so recent weakness contrasts with a stronger long run record as investors weigh ongoing Fukushima related risks against long term restructuring efforts.
Compare Tokyo Electric Power Company Holdings with other utilities facing substantial capital and regulatory commitments by scanning our hand picked 42 power grid technology and infrastructure stocks for potential alternatives in the grid and infrastructure space.
Tokyo Electric Power Company Holdings' share slide alongside fresh Fukushima funding can signal either deeper concern about the core business or a sentiment swing that has run too far. Which explanation fits the current valuation?
Preferred P/E of 2x: Is it justified?
On the numbers alone, Tokyo Electric Power Company Holdings looks inexpensive. A last close of ¥500 sits alongside a P/E of roughly 2x, which is far lower than both its peers and the wider Asian electric utilities group.
The P/E ratio compares the current share price to earnings per share. For a utility with long running assets and regulated exposure, this gauge often captures what the market is willing to pay for recurring profit while adjusting for one off shocks.
Here, the discount is stark. Tokyo Electric Power Company Holdings trades on 2x earnings compared with a peer average of 7.7x and an Asian electric utilities average of 12.6x. An estimated fair P/E closer to 12x is sometimes referenced as a level the market might consider if Fukushima related and balance sheet concerns ease.
Explore the SWS fair ratio for Tokyo Electric Power Company Holdings.
Result: Price-to-earnings of 2x (UNDERVALUED)
Still, Fukushima related liabilities and any shift in regulation or nuclear policy could quickly change how investors read the low P/E story for Tokyo Electric Power Company Holdings.
Find out about the key risks to this Tokyo Electric Power Company Holdings narrative.
Another view on Tokyo Electric Power Company Holdings
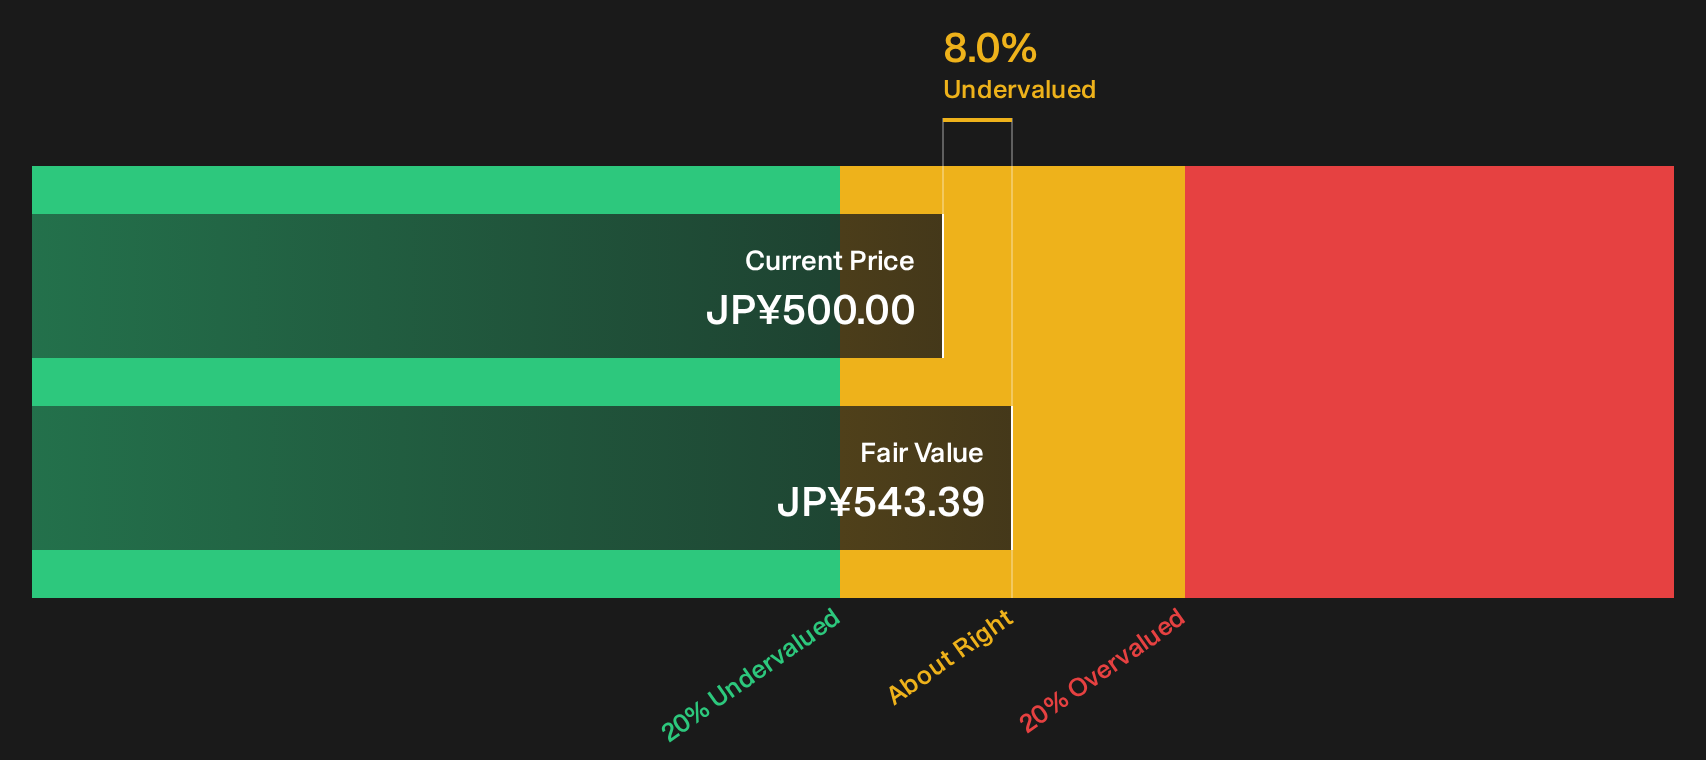
The SWS DCF model offers a second lens. At ¥500, Tokyo Electric Power Company Holdings is assessed at roughly 8% below an estimated future cash flow value of ¥543.39. This still points to undervaluation but with a narrower margin than the 2x P/E suggests. How comfortable are you with a discount driven by cash flow assumptions rather than simple earnings multiples?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Electric Power Company Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone on Tokyo Electric Power Company Holdings leaves you unsure, act while the data is fresh and test the numbers yourself. To weigh both the concerns and potential upsides side by side, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tokyo Electric Power Company Holdings?
Do not stop your research with Tokyo Electric Power Company Holdings. Broaden your watchlist now so you are not relying on a single story or sector.
- Target resilience by reviewing a 22 resilient stocks with low risk scores that can help you focus on businesses with lower risk profiles when markets feel unpredictable.
- Spot potential value by scanning a 72 high quality undiscovered gems that surfaces lesser known companies with strong underlying fundamentals before they appear on everyone else's radar.
- Strengthen your core holdings by using a list of solid balance sheet and fundamentals (23 results) that highlights businesses with sturdier financial footing for the long haul.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com