


Pay With Points Could Be A Big Move For Hilton Stock (HLT)
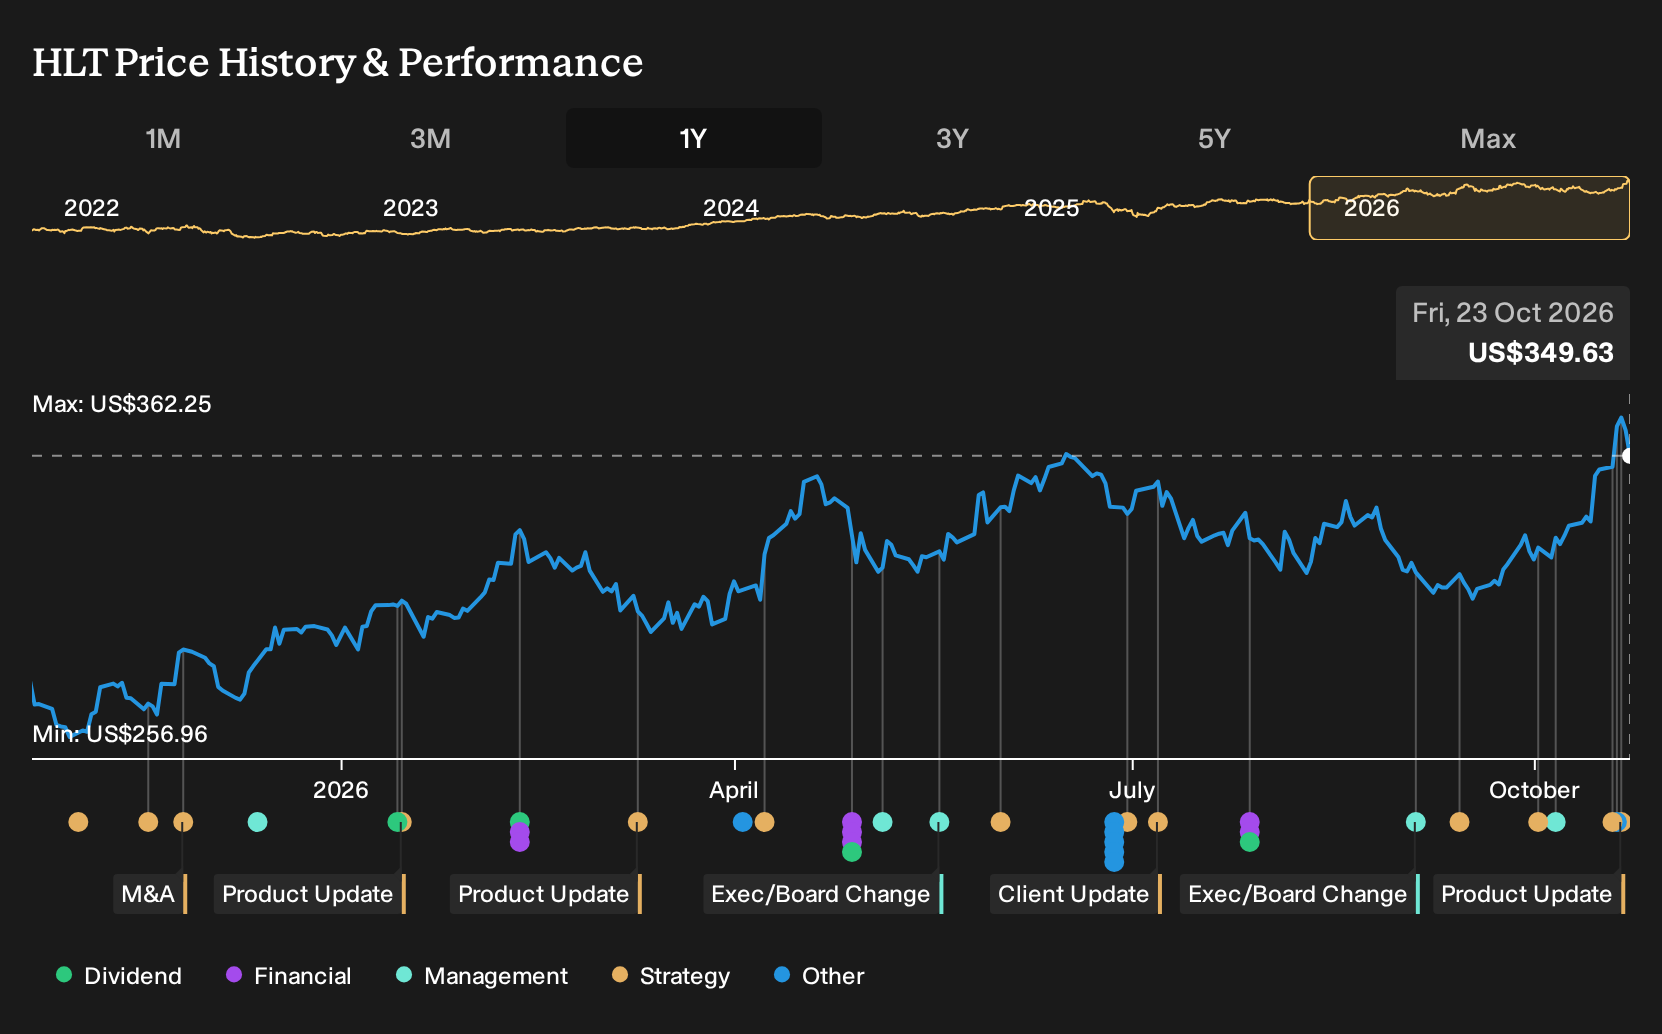
- Hilton Worldwide Holdings recently launched Pay with Points for Hilton Honors elite members in the U.S., and entered a multi-year hotel development agreement with Scandic Hotels Group across Sweden, Norway, Denmark and Finland.
- The combination of a self-service digital points feature and a Nordic development partnership highlights how Hilton is trying to deepen loyalty while widening its fee-earning footprint with limited capital use.
- The next consideration is what these moves, especially the Pay with Points rollout, might mean for Hilton Worldwide Holdings' investment narrative.
Hilton Worldwide Holdings Investment Narrative Recap
To own Hilton Worldwide Holdings, you need to be comfortable with a fee driven model where long term value comes from converting a large room pipeline into profitable openings, keeping RevPAR healthy across regions, and supporting owner margins so those partners keep flagging hotels with Hilton brands. The biggest near term swing factor is still execution on that pipeline while managing weaker pockets of demand in regions like the Middle East and China.
The main operational risk remains pressure on regional RevPAR and the drag from renovations at major owned hotels, which are estimated to be reducing EBITDA by US$20m to US$25m a year. Pay with Points and the Scandic agreement do not radically alter those near term risks, but they sit alongside the existing digital and development catalysts that investors already focus on.
The Pay with Points launch looks most relevant because it ties directly into Hilton Worldwide Holdings' push toward a more digital, high frequency relationship with Hilton Honors members. It takes the existing tech stack that includes Digital Check In, Digital Key and Choose Your Room and adds a new way for elite guests to interact with their Points at checkout, which can support engagement within the app.
For catalysts, the key question is whether this new feature supports occupancy and rate resilience in softer markets by nudging members to concentrate more stays with Hilton, especially as the pipeline scales. Execution risk centers on the test and rollout plan, since the feature is live at 150 hotels today and is expected to reach more than 6,000 properties in the U.S. and Canada by early 2027, with redemption options that vary by property.
Hilton Worldwide Holdings' current analyst narrative points to revenue of US$16.0b and earnings of US$2.7b by 2029, built on assumed yearly revenue growth of 46.3% and an earnings increase of about US$1.1b from US$1.6b today.
Discover why Hilton Worldwide Holdings' fair value appears to be generally consistent with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$246 per share to US$353, which shows how far opinions on Hilton Worldwide Holdings can stretch. When you layer that onto risks around RevPAR softness in the Middle East and China, it is a reminder that you should compare multiple viewpoints before leaning on any single narrative.
Explore another Hilton Worldwide Holdings fair value estimate, including one that suggests as much as 30% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hilton Worldwide Holdings research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Worldwide Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Worldwide Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
Once you have a view on Hilton Worldwide Holdings, it can help to compare it with other businesses that fit clear, rules based criteria. The Simply Wall St Screener lets you scan the market quickly so you can spend more time judging the stories behind the numbers.
- If you want potential value combined with quality fundamentals, start with a curated set of 29 high quality undervalued stocks that may be trading at appealing prices relative to their underlying strength.
- For readers who care most about resilience, focus on a 30 resilient stocks with low risk scores that score well on balance sheet strength and volatility filters.
- Those hunting for less crowded ideas can turn to a 21 high quality undiscovered gems where strong fundamentals have not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com