


Why Everyone Is Watching DXP Enterprises (DXPE) Again
Why DXP Enterprises Is Back On Investors’ Radar
Fresh attention on DXP Enterprises (DXPE) has been sparked by its very large 3 year return of 391.1% and a discounted cash flow analysis suggesting the stock may trade below intrinsic value.
The recent pullback in DXP Enterprises’ share price, with a 7 day share price return down 11.11% and a 30 day share price return down 18.66% to US$156.26, sits against a much stronger backdrop that includes a year to date share price return of 45.06% and a 3 year total shareholder return of about 391%. This suggests that long term momentum remains intact even as investors reassess the story after a strong run and factor in expansion moves such as the water and wastewater acquisitions in Canada and the current discounted cash flow signal of potential undervaluation.
Compare DXP Enterprises with other industrial stocks that pair strong multi year returns with potential valuation gaps using our hand picked 29 high quality undervalued stocks as a starting list.
DXP Enterprises has already delivered very large multi year gains, yet the recent pullback and a DCF pointing to a possible 20% discount raise a simple question: Is the meaningful upside still ahead or already in the rear view mirror?
Most Popular Narrative: 22% Undervalued
On Simply Wall St’s most followed view, DXP Enterprises screens as undervalued, with a fair value of $200 against a last close of $156.26. As a result, the current pullback is being weighed against a story that emphasizes water, wastewater and cash generation.
DXP Enterprises' focus on expanding its water and wastewater platform, including recent acquisitions that extend this business into Canada, is building a larger base of long-cycle municipal and regulatory driven projects that can support revenue and earnings resilience.
The shift toward higher-value engineered solutions, with DXP Water growing to roughly two thirds of IPS sales and IPS reporting higher segment operating income in recent periods, points to a mix change that can sustain a stronger margin profile and support net income.
See why 9 investors see DXP Enterprises as 22% undervalued.
Result: Fair Value of $200 (UNDERVALUED)
Still, the DXP Enterprises story hinges on two pressure points: debt of US$842.5 million remaining manageable, and quarterly results not repeating the Q1 2026 earnings miss.
Find out about the key risks to this DXP Enterprises narrative.
Another View On DXP Enterprises’ Valuation
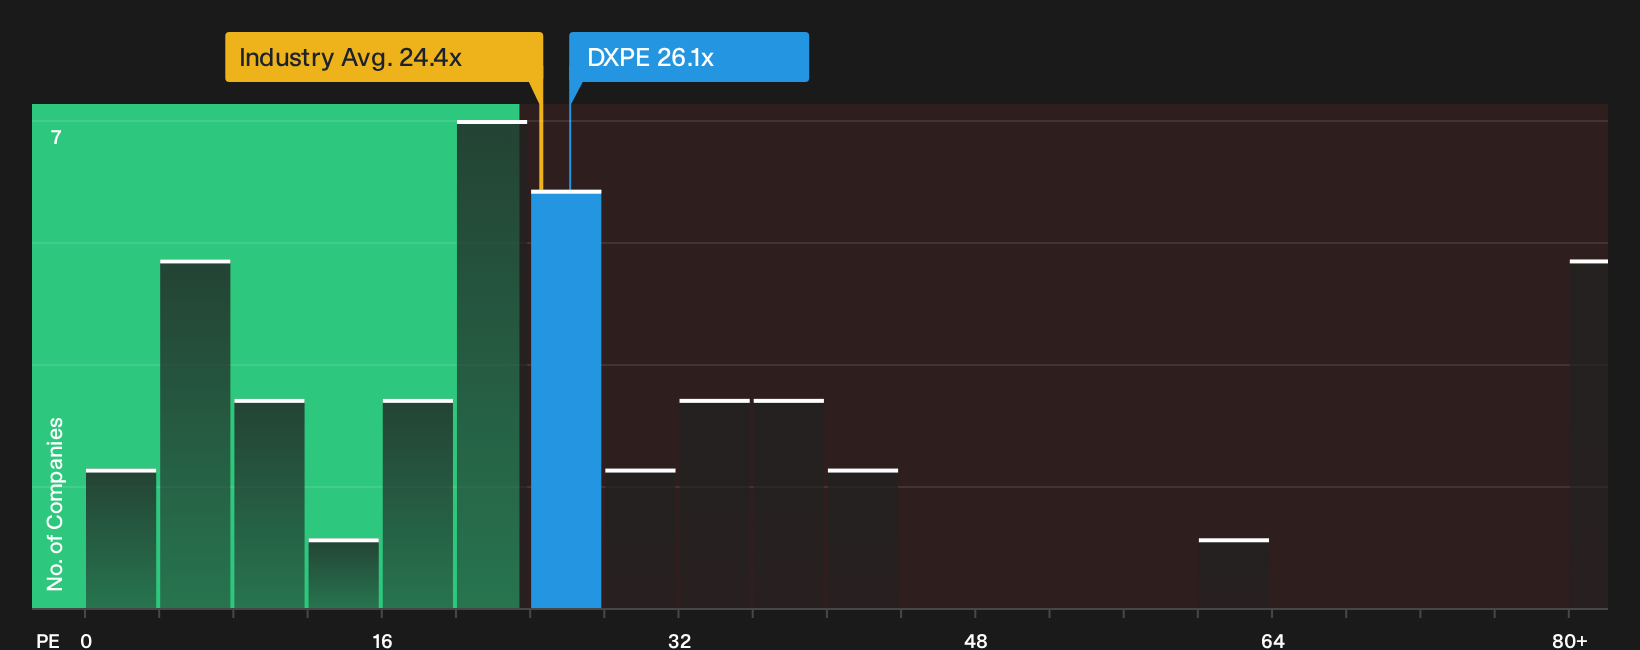
The discounted cash flow work paints DXP Enterprises as undervalued, yet the simple P/E check is less generous. DXPE trades on 26.1x earnings compared with 24.4x for the US Trade Distributors group and a fair ratio of 26.8x. That narrows the perceived cushion and raises a practical question: Is the real risk now in overpaying for quality or underestimating what the market might still be willing to pay?
For investors weighing these mixed valuation signals, it can help to zoom out from DCF spreadsheets and look at how earnings multiples have behaved across peers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on DXP Enterprises so far, right. If you want to move quickly and build your own judgment on the balance of concerns and potential upside, start by reviewing 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond DXP Enterprises?
DXP Enterprises may be on your screen today, yet your next strong idea could come from a completely different corner of the market if you are willing to look.
- Target potential mispricing opportunities by scanning a curated pool of quality companies through our 29 high quality undervalued stocks that appear cheaper than their fundamentals suggest.
- Strengthen the defense in your portfolio by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results) for balance sheet resilience and solid fundamentals.
- Spot less crowded opportunities by checking the 21 high quality undiscovered gems that highlight underfollowed companies with strong underlying metrics before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com