


FDA Dog Antibiotic Approval Could Be A Game Changer For Zoetis Stock
- Zoetis reported that the FDA has approved Convenia RTU for Dogs, a more concentrated cefovecin injectable that provides up to 14 days of treatment for susceptible bacterial skin infections in a single clinic administered dose.
- The new formulation targets medium and large dogs with a smaller injection volume and relies on 18 years of Convenia real world experience and more than 125 supporting studies, which speaks directly to Zoetis’ focus on compliance and clinically validated products.
- We will now look at how Zoetis’ investment narrative could shift as Convenia RTU for Dogs adds a new long acting therapy.
Zoetis Investment Narrative Recap
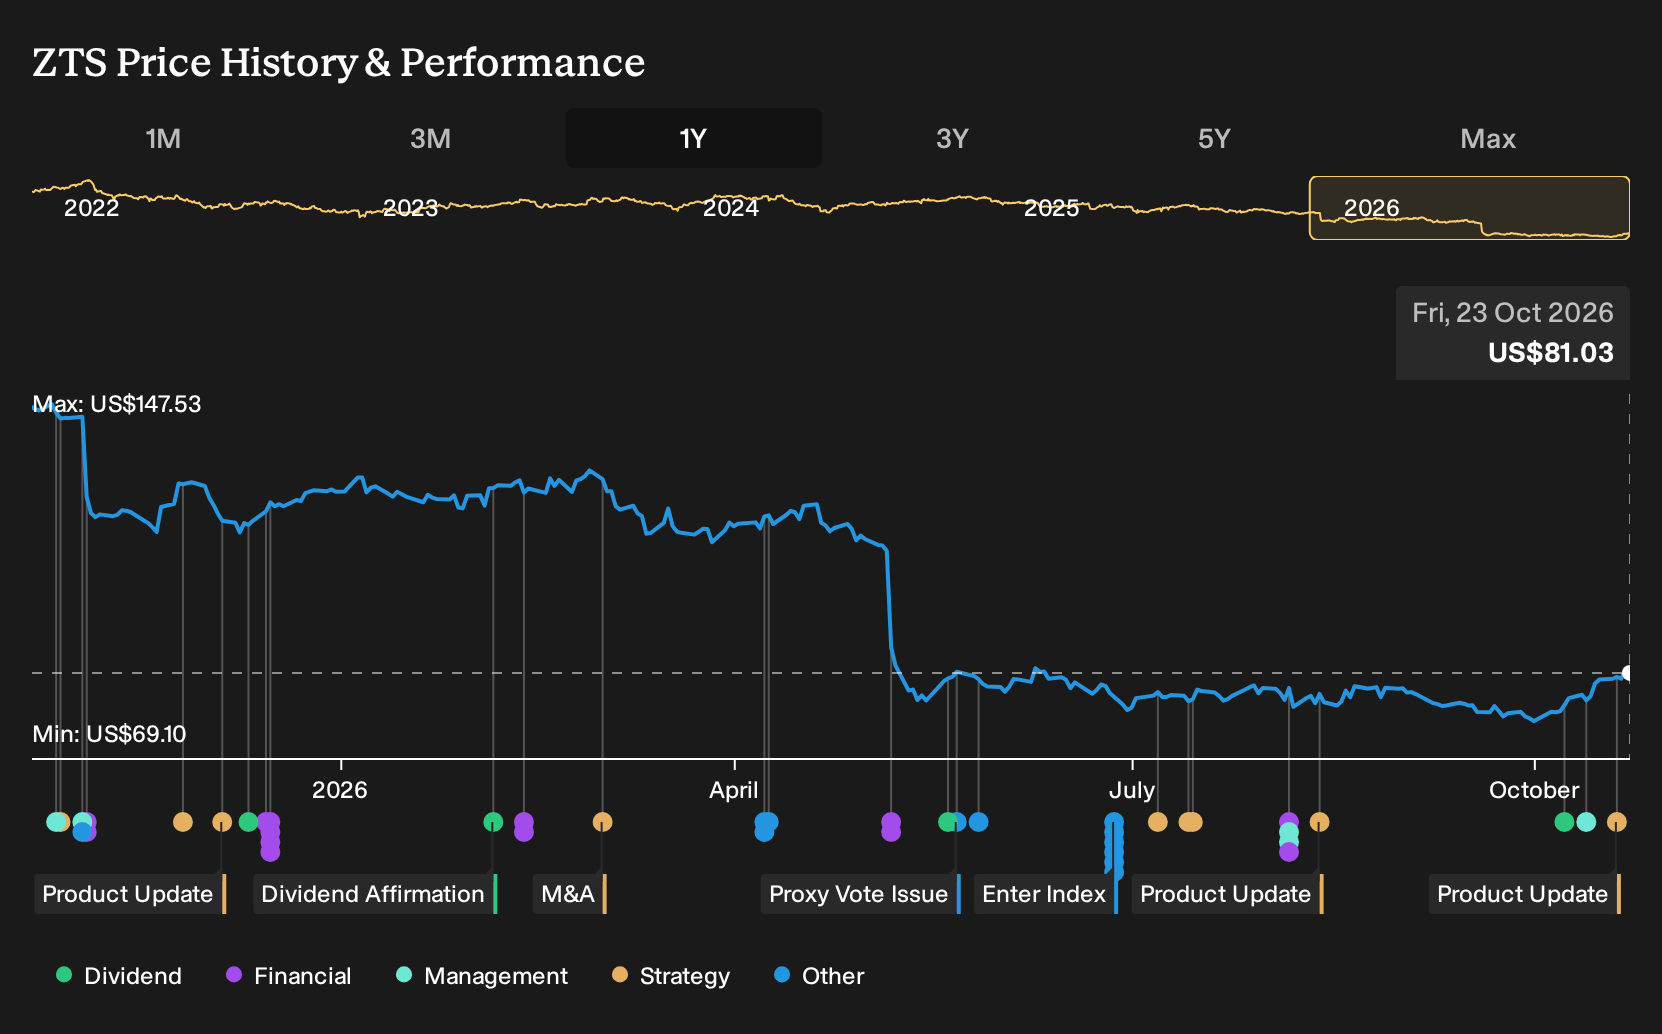
To own Zoetis, you need to believe its broad animal health portfolio and R&D pipeline can offset current pressure in companion animal demand and pricing. The key short term swing factor is execution through a softer U.S. pet market, with upcoming earnings on 5 November 2026 likely to keep attention on any further revenue or margin strain.
Convenia RTU for Dogs fits the long acting, compliance focused story but does not change near term risk that promotional spending and competitive pressure weigh on price realization. The biggest operational risk still centers on how long clinics lean on discounts and rebates, and whether volume for premium therapies stabilizes.
The most relevant recent announcement is the FDA approval of Convenia RTU for Dogs, which extends an established injectable antibiotic into a more concentrated, dog specific format. This keeps Zoetis tied closely to in clinic workflows and full dose compliance, which matters when veterinarians are cautious on client follow through and product switching.
Convenia RTU should sit alongside dermatology, parasiticides and diagnostics as another tool that can support the companion animal franchise as demand remains uneven. The planned 2027 availability means investors watching Zoetis catalysts may focus first on nearer term pipeline readouts and earnings execution, while viewing this approval as incremental support for the longer product cycle.
Zoetis is currently framed around consensus expectations that revenues reach US$9.9b and earnings come in at US$2.7b by 2029, supported by an assumed 1.4% yearly revenue growth rate and an earnings increase of about US$0.1b from US$2.6b today.
Uncover how Zoetis' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on earnings pressure rather than new product wins. The most cautious Zoetis analysts were modeling revenue of about US$9.2b and earnings of US$2.4b by 2029, with shrinking margins. That is a far more pessimistic story than consensus, and the Convenia RTU approval could push these expectations to evolve.
Explore 10 other Zoetis fair value estimates, including one that suggests it could be worth just $80.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Zoetis research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zoetis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zoetis' overall financial health at a glance.
Looking for more investment ideas beyond Zoetis?
If Zoetis has you thinking about where else capital could work hard for you, the Simply Wall St Screener can help you line up a wider watchlist in minutes, filtered around the traits you care about most.
- If you want potential mispricing on your side, scan a curated set of 29 high quality undervalued stocks that pair quality fundamentals with a share price that screens as below intrinsic value on our models.
- If capital protection matters as much as upside, focus on a 30 resilient stocks with low risk scores that score well on balance sheet strength, earnings consistency and overall risk checks.
- If you prefer sturdier fundamentals to story driven moves, build a shortlist from a list of solid balance sheet and fundamentals (24 results) and see which businesses match your return and risk preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com