


Has Bird Construction (TSX:BDT) Run Too Far Ahead Of Its Earnings Power?
Bird Construction (TSX:BDT) has become a talking point after its P/E ratio moved well above construction peers, following exceptionally strong multi-year share gains that leave investors debating how resilient its earnings power really is.
Recent trading has cooled after a huge run, with the share price down 10.39% over the past week and 12.75% over the past month. Yet Bird Construction still shows powerful momentum given its year-to-date share price return of 136.32% and a very large 3-year total shareholder return of more than 6x. This helps explain why the market is now testing how much of that strength is already reflected in today’s CA$69.1 quote and rich P/E multiple.
Compare Bird Construction’s premium P/E and project-driven earnings story with a curated list of solid balance sheet and fundamentals (7 results) that could be better positioned for the next twist in the construction cycle.
Bird Construction now trades at a premium P/E, yet at a 23% discount to the average analyst price target of CA$89.38. Is that a genuine margin of safety or a value trap in the making?
Most Popular Narrative: 23% Undervalued
Bird Construction’s most followed valuation story pegs fair value at about CA$89.38 per share, which sits well above the latest CA$69.1 close and puts the spotlight firmly on how durable that CA$12b backlog and margin profile really are.
Bird Construction is positioned to participate in large Canadian infrastructure, energy and defense programs over multiple years, with combined contracted and pending backlog of about $12b at Q2 2026 that could support future revenue and earnings as this work is executed. Growing use of collaborative contracts and recurring programs is visible in the combined backlog, where over 80% is now tied to these structures and embedded margins are higher than a year earlier, which may support net margin and EBITDA expansion as projects convert to revenue.
See why 173 investors see Bird Construction as 23% undervalued.
Result: Fair Value of CA$89.38 (UNDERVALUED)
Still, the Bird Construction story can crack if project deferrals return or another large customer default hits cash collection and squeezes already thin profit cushions.
Find out about the key risks to this Bird Construction narrative.
Another View: Bird Construction On Earnings Multiples
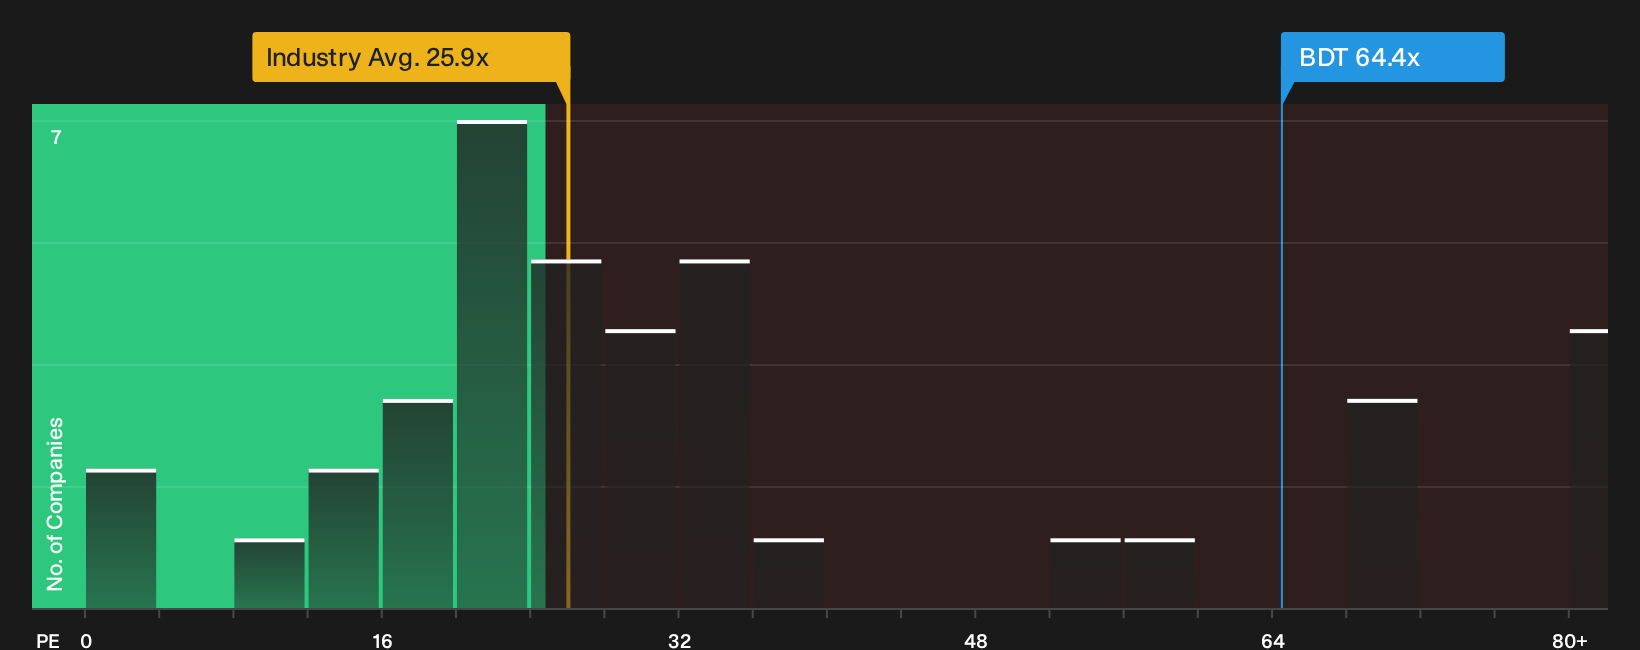
There is a catch. Bird Construction trades on a P/E of 64.4x, which is far above the peer average of 28.4x, the North American construction industry at 25.9x, and even the fair ratio of 58.2x that the market could move toward over time. That kind of gap can increase valuation risk if anything affects the growth story.
To see how much of this premium is backed by the underlying numbers, take a closer look at the valuation breakdown, including the fair ratio signal, in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Bird Construction’s premium P/E and backlog strength can feel hard to square, so move fast and test the story against your own thresholds. To balance that optimism with the concerns already flagged by the data, start with the 2 key rewards and 1 important warning sign.
Looking for more Bird Construction style investment ideas?
If Bird Construction has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now or risk missing the next opportunity hiding in plain sight.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (7 results) that filters for financial strength first.
- Hunt for mispriced potential by running a focused search across a 9 high quality undiscovered gems that screens for quality hiding outside the usual headlines.
- Prioritise capital protection by zeroing in on a 8 resilient stocks with low risk scores that highlights companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com