


STERIS (STE) Nears Earnings As Recurring Revenue Story Points To Higher Fair Value
STERIS (STE) is back in focus as investors look ahead to its Q2 2027 earnings release on 4 November 2026, with projected EPS of $2.67 guiding expectations.
Recent trading has been choppy for STERIS. The share price has climbed over the shorter term, with a 7 day share price return of 4.26% and a 30 day share price return of 11.11%. It remains down year to date, contributing to a 1 year total shareholder return decline of 2.51% but a positive 3 year total shareholder return of 14.33%. This suggests nearer term momentum has picked up even as longer run gains have been more moderate.
Track how STERIS fits into the wider healthcare opportunity set by scanning a handpicked list of solid balance sheet and fundamentals (24 results) that share similar resilience traits.Steris has quietly rebuilt some momentum after a softer year. The key issue now is whether that rebound still leaves enough upside to justify the risk once you run the valuation numbers.
Most Popular Narrative: 12% Undervalued
Simplifying it, the most followed narrative pegs STERIS at a fair value of $263.13 using a 7.68% discount rate, compared with the last close at $232.15. That gap reflects a view that the recurring revenue tilt and large capital projects could justify a richer valuation if execution stays on track.
Continued mix shift toward recurring chemistries and services, which now account for roughly 80% of STERIS revenue versus about 20% a decade ago, can add stability to organic revenue and support operating leverage into earnings.
See why 7 investors see STERIS as 12% undervalued.
Result: Fair Value of $263.13 (UNDERVALUED)
Still, tariff costs and the North Carolina chemistries project, along with associated restructuring charges, could pressure margins and cash generation if execution slips.
Find out about the key risks to this STERIS narrative.
Another View: STERIS On Earnings Multiples
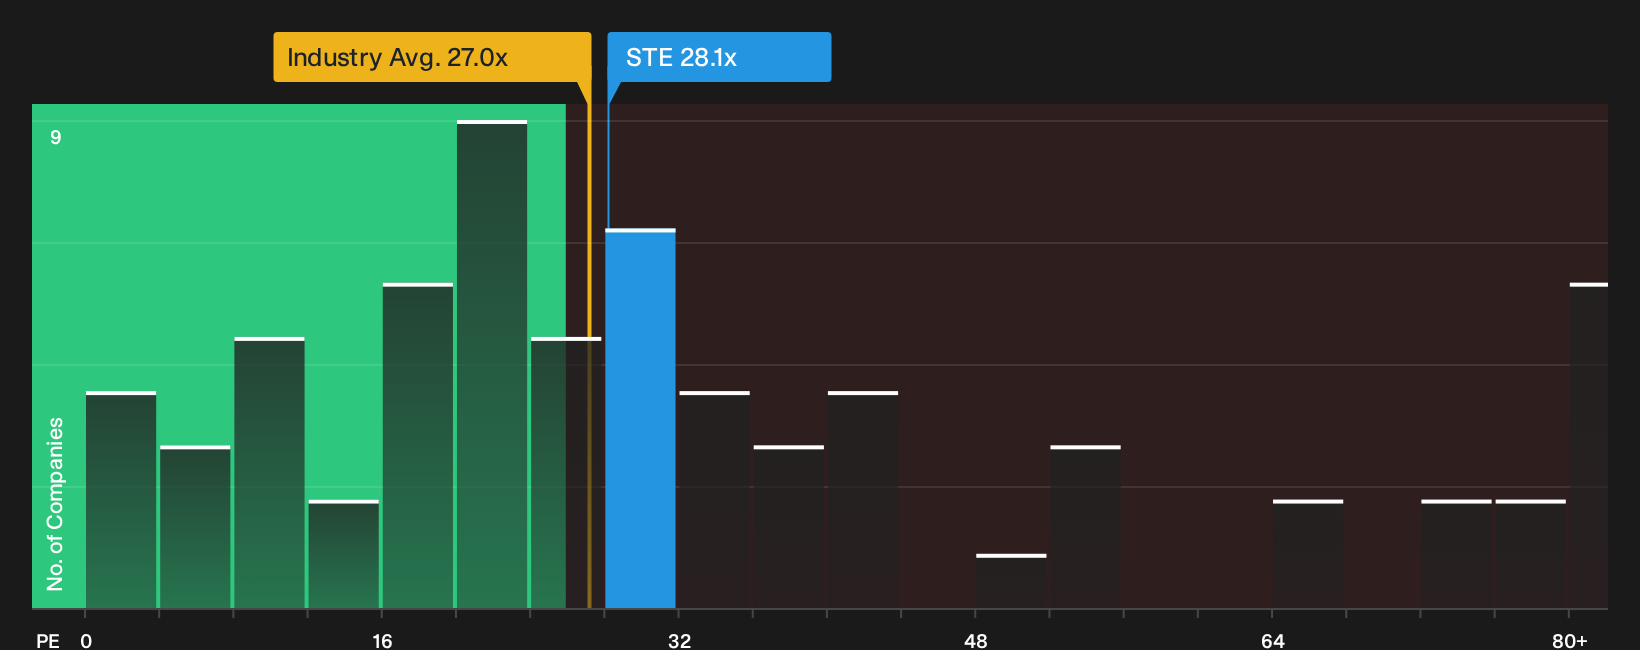
That 12% undervalued fair value hinges on long term cash flows. A simpler cross check uses today’s P/E. STERIS trades on 28.1x, above both its 26.3x fair ratio and the 23.1x peer average and the 27x US Medical Equipment group. This richer tag can limit upside if sentiment cools.
For a closer look at how that premium multiple could shift as conditions change, and whether the current price leaves much room for error, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around STERIS is mixed enough that waiting on the sidelines could leave you reacting instead of deciding. Act early, review the upside and risk drivers yourself, and then weigh them against the 2 key rewards.
Looking for more STERIS sized investment ideas?
If you stop with STERIS, you risk missing other stocks that match your goals. Widen the opportunity set using targeted screeners built for different edges.
- Target dependable cash machines by filtering for a 5 dividend fortresses that focus on income resilience alongside payout strength.
- Chase potential mispricings by scanning a 21 high quality undiscovered gems that marry robust fundamentals with limited market attention.
- Dial down portfolio stress by concentrating on a 30 resilient stocks with low risk scores that score well on financial strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com