


WeRide (WRD) Gains WICV Recognition As Its Valuation Story Faces A Fresh Test
WeRide (WRD) just picked up fresh industry recognition at WICV 2026, where its Physical AI flywheel and GENESIS and WITT platforms were named among the Top 10 Automotive AI Application Cases.
Set against that technical progress, WeRide’s share price tells a different story, with a year to date share price return down 55.6% and a 1 year total shareholder return down 60.8%. This points to fading momentum even after short term gains of 0.97% over 1 day and 2.21% over 7 days.
Look beyond WeRide and see how other AI-focused auto companies are priced by reviewing the hand-picked 95 robotics and automation stocks that are now shaping the next phase of autonomous mobility.
Bulls see WeRide’s industry awards, expanding L2 to L4 footprint, and the analyst target gap as a mispriced growth story. Bears point to heavy losses and a falling share price. Which case does the current valuation lean toward?
Most Popular WeRide Narrative: 68% Undervalued
On the most followed view of WeRide, a fair value of $13.02 sits well above the last close at $4.17, which puts the current share price at a steep discount to that narrative.
The dual deployment of L4 robotaxis and L2+ WePilot 3.0 ADAS in mass production vehicles from Chery EXEED and GAC allows data and software to be reused across product lines. This can spread R&D spending over a larger revenue base and potentially support higher group level margins.
See why 8 investors see WeRide as 68% undervalued.
Result: Fair Value of $13.02 (UNDERVALUED)
Still, the WeRide story can break if regulatory approvals slow or rider adoption disappoints, which could keep high R&D spending from translating into better unit economics.
Find out about the key risks to this WeRide narrative.
Another View: What WeRide’s Sales Multiple Is Saying
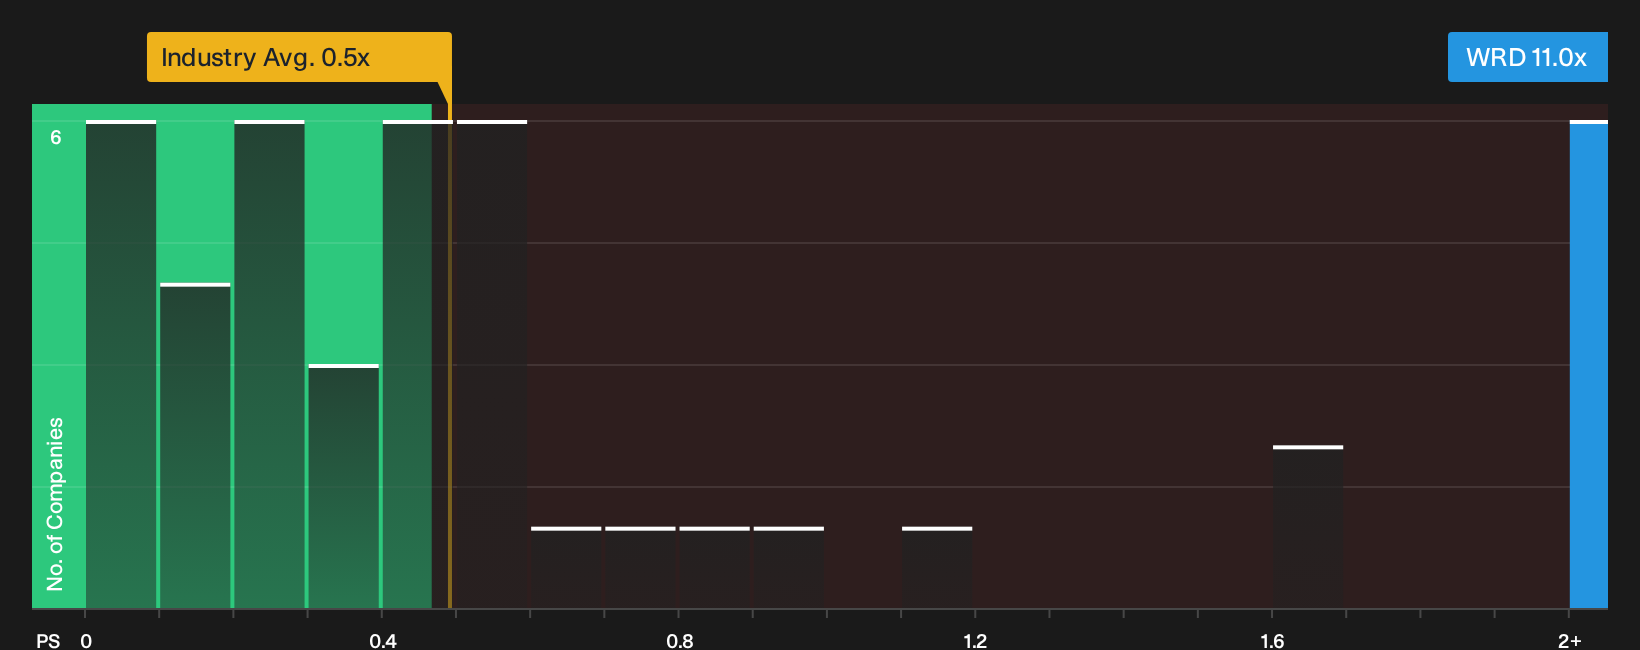
On a simple sales lens, WeRide trades on a P/S of 11x. Peers in the US Auto Components space trade around 0.5x, while the fair ratio estimate for WeRide is 3.4x. That is a wide premium. It raises a straight question for investors: How much execution risk are you really comfortable paying up for?
To see how those valuation gaps line up with the underlying business assumptions, take a closer look at the detailed multiples workup in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around WeRide is split, so move quickly from headlines to hard numbers and build your own view of the potential upside. To see what is driving optimism in the first place, review the 1 key reward.
Looking for more investment ideas beyond WeRide?
If the WeRide setup has your attention, do not stop here. Use Simply Wall Street’s screener to spot other opportunities before the crowd moves first.
- Target stronger downside protection by scanning 30 resilient stocks with low risk scores that score well on resilience and balance across different conditions.
- Hunt for quality at a discount with the focused 21 high quality undiscovered gems that many investors have not yet priced in.
- Build a sturdier core portfolio by filtering through the list of solid balance sheet and fundamentals (24 results) and anchor your research in financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com