


Macerich (MAC) Expands Restaurant Leasing, Is It Still Below Fair Value?
Macerich (MAC) is increasing its focus on food and entertainment, accelerating restaurant leasing across its Class A shopping centers with first to market concepts and high profile dining brands at flagship properties nationwide.
Recent trading suggests this restaurant push is catching investor attention, with a 7 day share price return of 4.97% and a 30 day gain of 6.45% at a latest share price of US$24.10, even though the 90 day move is down 7.77%.
For context, Macerich’s share price return is up 30.13% year to date, while total shareholder return over the past 1 year is 38.16% and over 3 years is very large. This shows how the market has been recalibrating expectations around this real estate investment trust’s repositioning of its malls into more experience led destinations.
Spot similar experience-led real estate stories in our hand picked set of 21 high quality undiscovered gems that pair strong fundamentals with under the radar positioning.Macerich’s move to US$24.10 after a strong year puts a practical question in front of you. Is the better risk reward buying the REIT here, or waiting for a cheaper entry before committing fresh capital?
Most Popular Narrative: 9% Undervalued
Macerich’s most followed narrative pegs fair value at about $26.63, which sits above the recent $24.10 share price and frames the current debate around how much of its turnaround is already reflected.
The focus on experiential and destination-oriented retail (e.g., DICK'S House of Sport, Cheesecake Factory, entertainment concepts) is revitalizing consumer engagement and increasing traffic, positioning the portfolio to benefit from experience-driven spending and capturing higher net margins over time.
See why 1 investors see Macerich as 9% undervalued.
Result: Fair Value of $26.63 (UNDERVALUED)
Still, heavy leverage and concentrated exposure to challenged brick and mortar markets mean tougher refinancing conditions or weaker tenant demand could quickly test this Macerich turnaround story.
Find out about the key risks to this Macerich narrative.
Another View: Macerich Through The P/S Lens
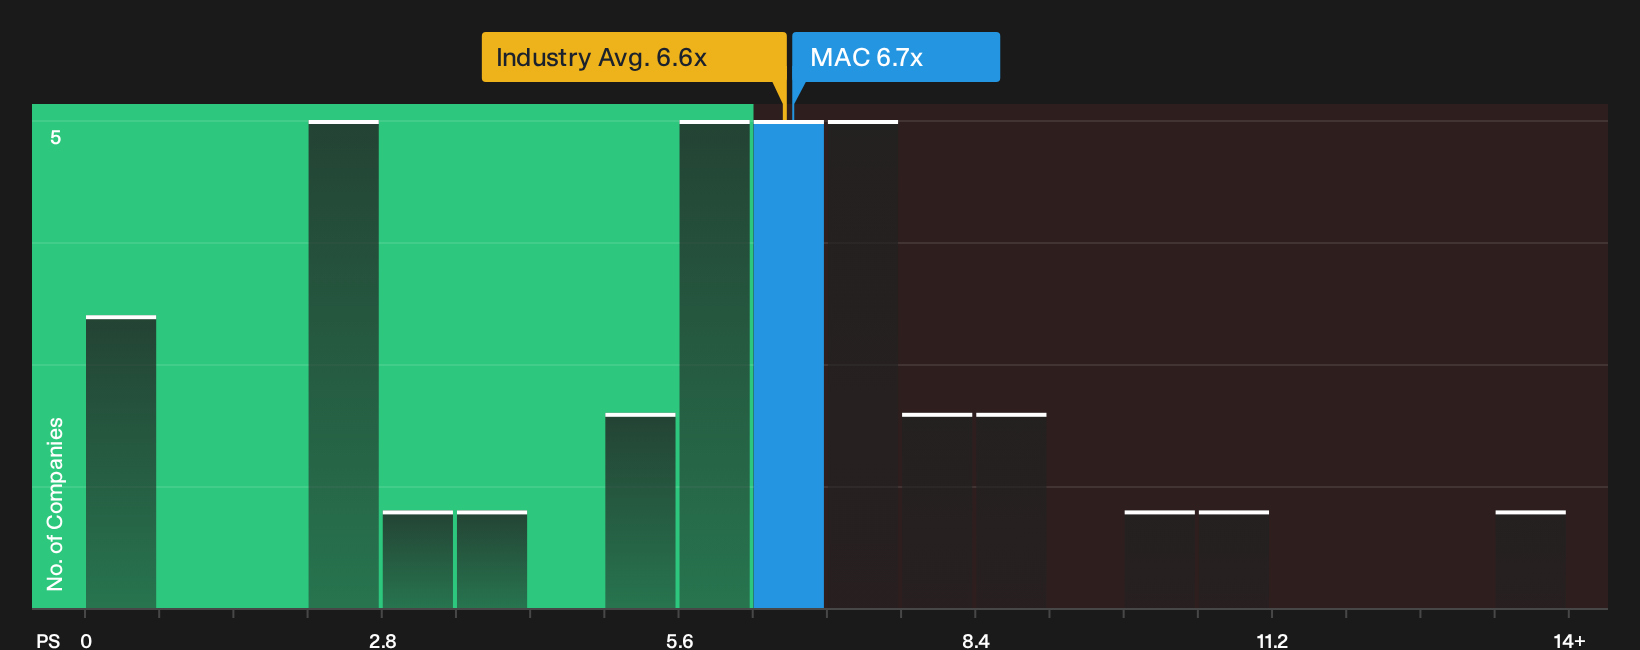
On the flip side of that 9% undervalued fair value story, Macerich trades on a P/S of 6.7x, just above the US Retail REITs industry at 6.6x and well ahead of a fair ratio of 4.2x. That gap points to valuation risk if sentiment cools, or to resilience if experience-led assets stay in demand.
To see how the current price lines up with that P/S gap and what the numbers imply in practice, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you stress test them against your own risk and reward expectations. Move quickly and pressure check Macerich’s story against the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Macerich?
Do not stop with a single real estate story. Use the Simply Wall Street Screener to quickly scan other opportunities that might suit your approach and risk comfort.
- Target companies where quality and value intersect by reviewing our 29 high quality undervalued stocks and see which stocks currently line up with those filters.
- Prioritise stability first and check the list of solid balance sheet and fundamentals (24 results) if you want businesses with stronger financial footing to anchor your portfolio.
- Offset higher risk positions and steady your overall returns with income ideas sourced from the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com