


Can ServisFirst Bancshares (SFBS) Justify Its Valuation After Strong Earnings And Lower Charge Offs?
Why ServisFirst Bancshares Just Drew Fresh Attention
ServisFirst Bancshares (SFBS) has moved back onto investor watchlists after its third quarter report showed higher net interest income and net income, alongside lower net charge offs and a newly authorized share repurchase plan.
Recent trading has been choppy for ServisFirst Bancshares, with the share price falling about 6.5% over the past 90 days, even after a 4.7% gain in the last week. At the same time, the 1 year total shareholder return of 18.6% hints at momentum that has been building over a longer stretch.
Compare ServisFirst Bancshares with other regionally focused banks by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may also be reacting to fresh earnings and buyback news.
ServisFirst Bancshares now pairs a softer three month share price with rising earnings, improving charge offs and a fresh buyback. Does that mix still tilt the risk reward in favour of new buyers at today’s valuation?
Most Popular Narrative: 10.3% Overvalued
ServisFirst Bancshares last closed at $41.22, compared with a widely followed narrative fair value of $37.37, so the discussion now turns to whether recent management actions justify that gap.
The tone shift is instructive less for what changed than for what didn’t. Broughton opened July calling the bank “generally pleased with the results,” then circled back in his closing remarks to sharpen that into something less comfortable (“certainly were pleased with the quarter, not satisfied”), reaching for “eight cylinders” as a self-rating device and landing somewhere just under it. October drops the self-assessment language almost entirely; there’s no cylinder count, no letter grade, no explicit satisfaction rating. The quarter is described through its outputs: EPS growth, margin, efficiency ratio. Management narrates the business; it stops narrating its own performance relative to potential.
See why 1 investors see ServisFirst Bancshares as 10% overvalued.
Result: Fair Value of $37.37 (OVERVALUED)
Still, the ServisFirst Bancshares narrative could be upset if loan growth remains muted or if credit issues, such as the multifamily workout, widen beyond current disclosures.
Find out about the key risks to this ServisFirst Bancshares narrative.
Another View: ServisFirst Bancshares Through A Different Lens
The first narrative tagged ServisFirst Bancshares as about 10.3% overvalued at $41.22 versus a $37.37 fair value. A different approach, our DCF model, points the other way and suggests the shares trade below an estimated future cash flow value of $66.22. Which story feels more realistic to you?
Investors who want to see how that detailed cash flow work is put together can walk through the SWS DCF model step by step here, then weigh it against the narrative fair value before deciding how much conviction to place on either view. Look into how the SWS DCF model arrives at its fair value.
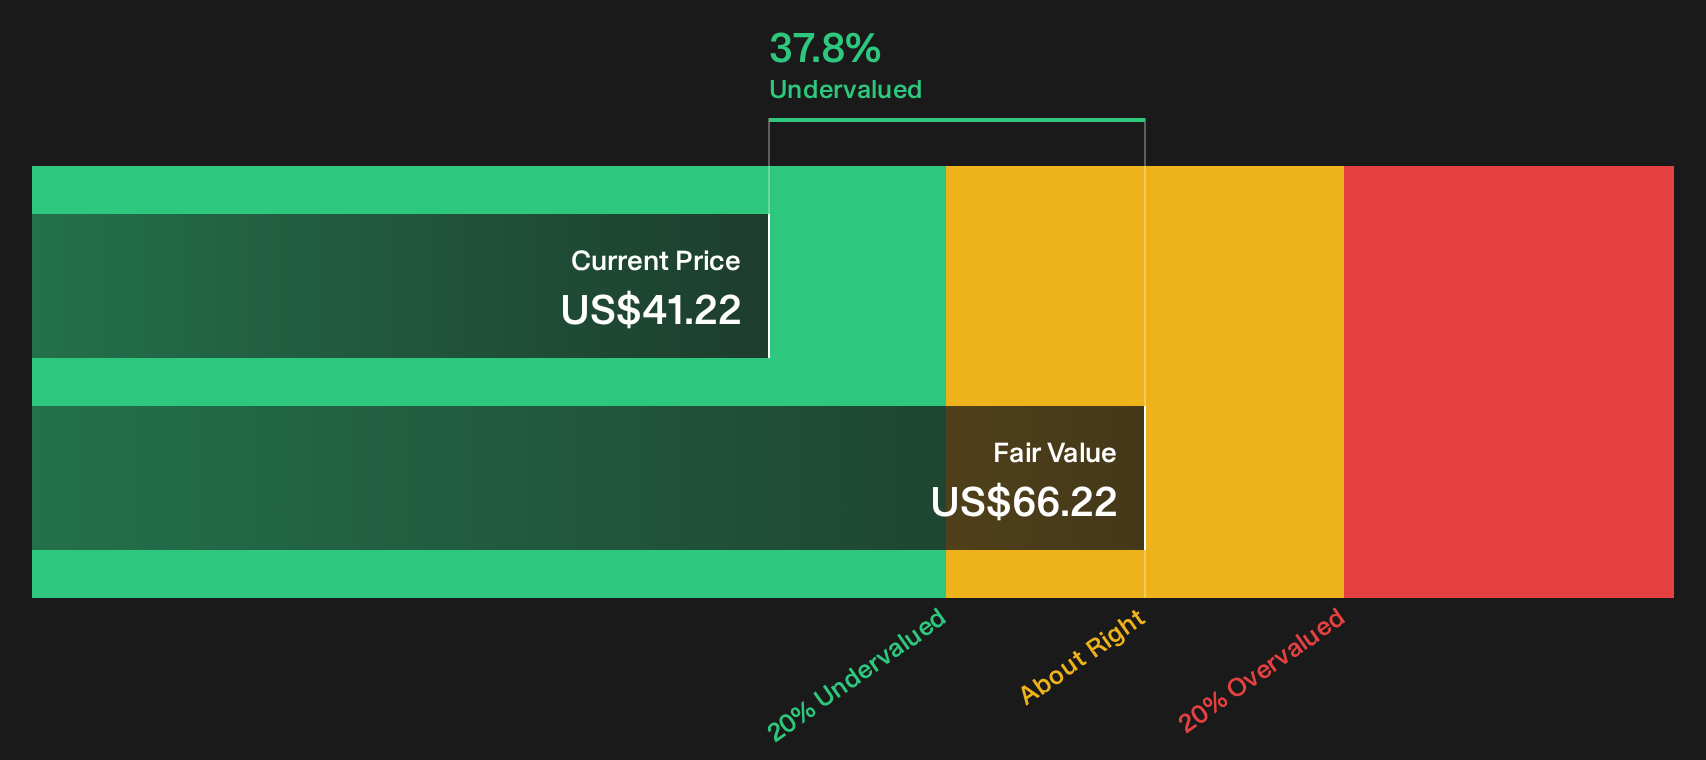
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ServisFirst Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the ServisFirst Bancshares story so far. If you want to move quickly and build your own stance, start with the full view of 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond ServisFirst Bancshares?
If you stop with ServisFirst Bancshares, you risk missing other opportunities that match your style, so put a few more candidates on your radar today using the Simply Wall Street Screener.
- Target resilient balance sheets and steadier fundamentals by reviewing our 30 resilient stocks with low risk scores, which highlights businesses with lower assessed risk profiles.
- Hunt for quality selling at a discount by scanning the 29 high quality undervalued stocks, which filters for financially robust companies trading below their assessed worth.
- Stack potential returns with ongoing income by focusing on the 5 dividend fortresses, which pinpoints higher yielding payers with durable payout track records.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com