


Is New Body Camera Launch Altering The Investment Case For Axon (AXON)?
- Axon Enterprise recently introduced Axon Body 5 and Axon Body 5 Pro, new body-worn cameras with 25x AI processing power, improved connectivity, upgraded audio and video, and longer battery life to support officers in the field.
- The launch ties Axon Body 5 directly into Axon’s AI Era Plan, aiming to shift more public safety work toward AI driven, software rich workflows at the edge.
- The discussion now turns to how Axon Enterprise’s investment narrative could be affected by Axon Body 5’s on-device AI processing power.
Scan 55 AI infrastructure stocks, which, like Axon Enterprise, is building the hardware and software backbone for AI driven policing tools, real time video analytics and edge computing in the field.
Axon Enterprise Investment Narrative Recap
To own Axon Enterprise, you need to buy into a public safety platform that leans heavily on recurring software, AI tools and integrated hardware like TASER devices, cameras and drones. The near term focus is whether that ecosystem keeps translating into higher software and services mix and steadier margins while newer offerings weigh on profitability.
The biggest short term swing factor is execution on large AI Era Plan deployments and newer products such as Dedrone and TASER 10, especially with profitability recently pressured. Key risk still sits in government budgets and contract timing, so Axon Body 5 looks more like an incremental product proof point rather than a standalone catalyst.
The launch of Axon Body 5 ties directly into that AI centric story. The camera’s 25x AI processing capacity, longer battery life and upgraded connectivity are built to keep more intelligence at the edge, which matters if agencies increasingly choose premium software bundles and AI features instead of basic camera contracts.
What really links this to catalysts is the way Axon Body 5 plugs into tools like Draft One, Axon Assistant and Guardian, and into platforms such as Axon Fusus. If agencies adopt those workflows at scale, the result is more software and services usage on top of the existing hardware base, but it also raises scrutiny around privacy, data control and policy that Axon Enterprise must keep managing carefully.
Axon Enterprise's current analyst narrative points to revenues of US$6.9b and earnings of US$444.1 million by 2029, based on a projected 28.8% yearly revenue growth rate and a move in profit margins from 6.2% today to 6.5% in three years. This implies an earnings increase of about US$244.8 million from the current US$199.3 million level.
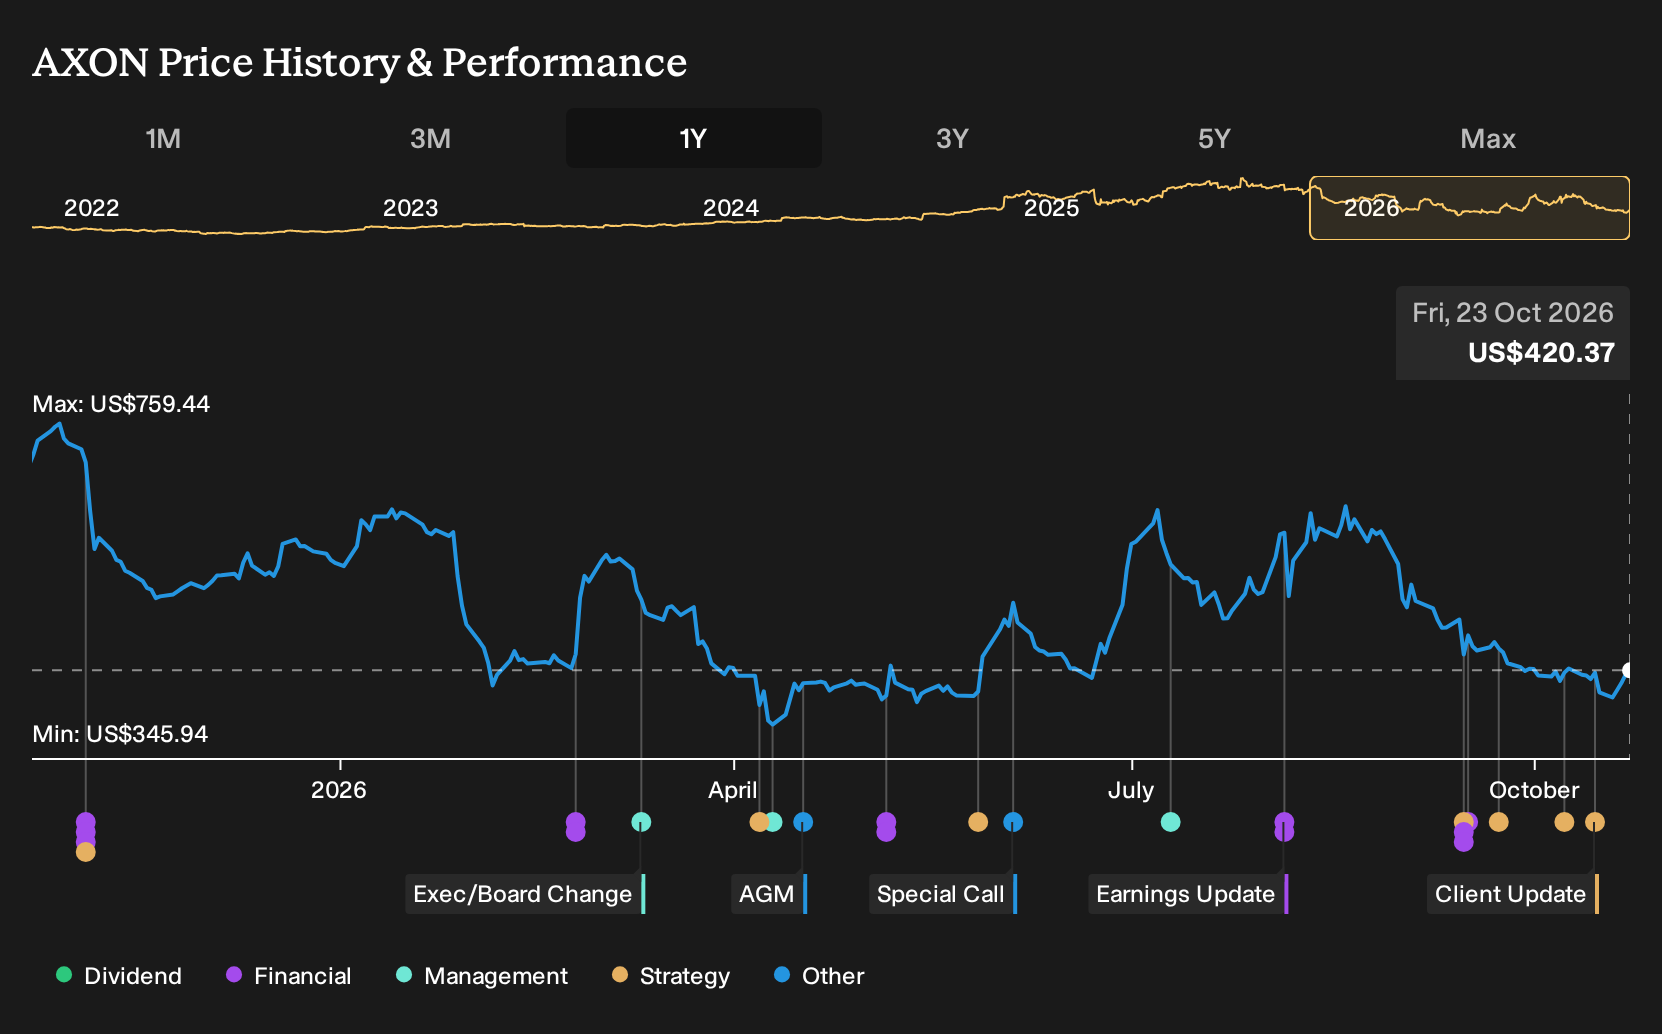
Discover how Axon Enterprise's fair value indicates a 62% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
One alternate view on Axon Enterprise leans hard into upside from AI Era Plan contracts. The most optimistic analysts were already modeling about 35.0% annual revenue growth and earnings of roughly US$949.1 million by 2029 before Axon Body 5. You can treat this launch as a fresh reason to compare those assumptions with more cautious forecasts.
Explore 4 other Axon Enterprise fair value estimates, including one that suggests as much as 62% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Axon Enterprise research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Axon Enterprise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Axon Enterprise's overall financial health at a glance.
Looking For More Investment Ideas Beyond Axon Enterprise?
Once you have a view on Axon Enterprise, it often helps to compare it with a wider set of opportunities that suit your risk profile and income needs. The Simply Wall St Screener can narrow that universe quickly so you spend time assessing a short list rather than sifting through everything on the market.
- If you want potential value with quality fundamentals, start with companies flagged as mispriced on cash flows and balance sheet strength using the 29 high quality undervalued stocks.
- For investors who care most about capital preservation, filter for businesses with steadier profiles and fewer red flags through the 30 resilient stocks with low risk scores.
- If you are hunting for income, focus on resilient payers with higher yields and solid coverage by checking the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com