


Will Raised Dividend Change Getty Realty (GTY) Narrative
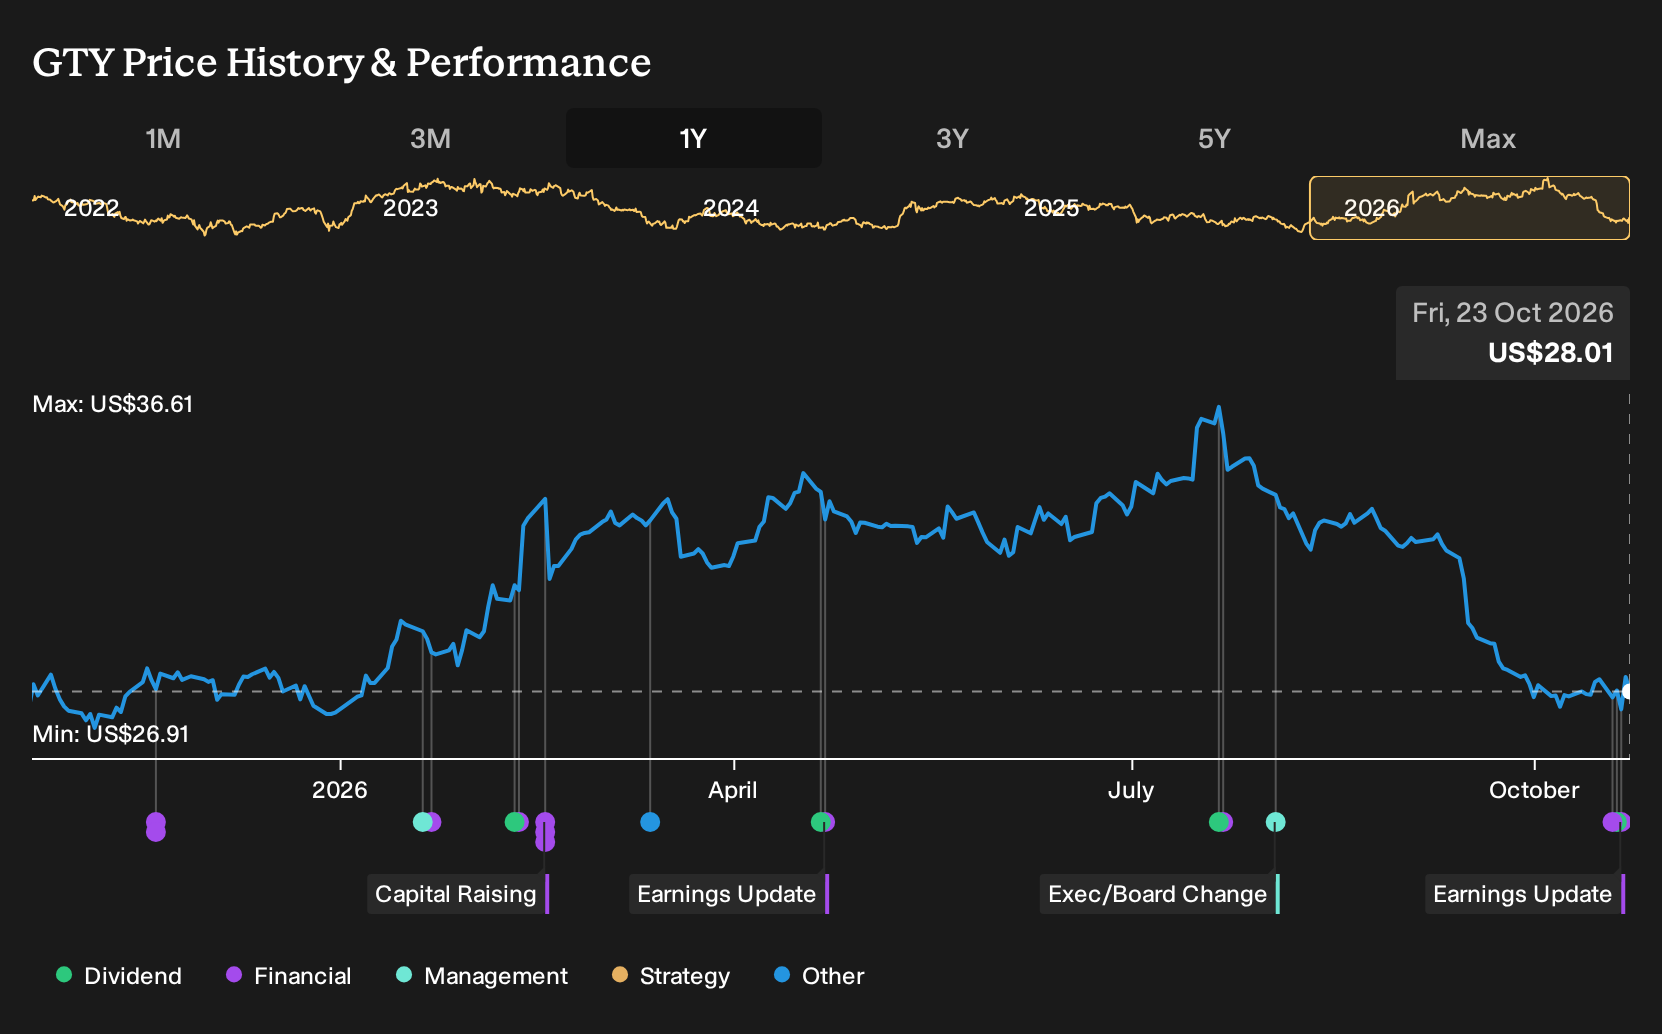
- Getty Realty reported third quarter 2026 revenue of US$62.99 million and net income of US$25.61 million, raised full year AFFO guidance, lifted its quarterly dividend to US$0.50 per share, and put a new US$200 million senior unsecured term loan in place under an amended credit agreement.
- The combination of record sale leaseback activity, an increased dividend, and expanded unsecured funding capacity indicates that management is leaning into Getty Realty's net lease model to support cash generation and an active acquisition program.
- Investors will now be watching how Getty Realty's higher dividend payout interacts with its acquisition-driven investment narrative and updated credit facility.
See how Getty Realty’s latest dividend raise and term loan compare with other real estate plays by exploring our curated list of list of solid balance sheet and fundamentals (24 results)
Getty Realty Investment Narrative Recap
To own Getty Realty, you need to believe its net lease model on convenience and automotive sites can keep occupancy high and rent coverage solid even as interest costs and mobility trends evolve. The latest quarter showed revenue of US$62.99 million and net income of US$25.61 million, with AFFO guidance raised, so the near term story still leans on consistent cash generation.
The key short term catalyst remains execution on the acquisition and sale leaseback pipeline, without eroding spreads between cap rates and funding costs. The biggest risk is that higher financing expenses or weaker tenant economics, including from lower fuel demand at some locations, eat into that spread. The recent results and financing updates do not remove that risk but keep it in check for now.
The US$200 million senior unsecured term loan under the amended credit agreement is the most relevant announcement here. It directly affects how Getty Realty funds deals and manages refinancing. The facility carries an effective interest rate of 5.03% at closing, which matters when new assets are underwritten at mid to high 7% initial yields.
For you as a shareholder, this term loan feeds into both the catalyst and the risk column. It supplies fresh capacity to back the Refuel sale leaseback and the broader external growth program. At the same time, the covenants on leverage, coverage, and restricted payments could cap how far Getty Realty leans into debt or dividends if conditions tighten. Execution now hinges on keeping that balance sheet flexibility aligned with tenant performance and acquisition returns.
Getty Realty's narrative projects US$306.9 million revenue and US$108.1 million earnings by 2029. This assumes 9.6% yearly revenue growth and an earnings increase of about US$11.8 million from US$96.3 million today.
Uncover why Getty Realty's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$33.86 to US$74.33 per share, so private investors are inputting very different expectations for Getty Realty. That spread reflects real world questions around fuel demand, funding costs, and the new term loan. Use these contrasting views to stress test your own thesis.
Explore 2 other Getty Realty fair value estimates, including one that suggests up to 165% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your Getty Realty research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Getty Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getty Realty's overall financial health at a glance.
Looking for more investment ideas beyond Getty Realty?
Once you have a handle on Getty Realty, it often helps to compare it with other listed businesses that share similar qualities or offer a different risk and income profile. The Simply Wall St Screener can narrow that universe quickly so you can focus on a shortlist that fits your own goals.
- For investors who care most about quality at a sensible entry point, you can filter for established companies trading below their assessed worth with the 29 high quality undervalued stocks.
- If resilience and balance sheet strength sit at the top of your checklist, you can start with a 30 resilient stocks with low risk scores that scores well on debt and financial stability.
- Those hunting for ideas that the market may be overlooking can widen the opportunity set with a 21 high quality undiscovered gems that still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com