


Parcel Volume Surge Change The Bull Case For J&T Express Stock (SEHK:1519)?
- J&T Global Express reported third quarter 2026 operating results showing global parcel volume of 9.58 billion, up 24.8% year on year, with average daily parcels at 104.2 million and above 100 million for a second straight quarter.
- Across the first nine months of 2026, parcel flows reached 27.09 billion and 99.2 million per day. J&T Global Express kept its lead in Southeast Asia and recorded robust contributions from Other Markets and record high growth in China.
- We will now examine how J&T Global Express's global parcel volume momentum could influence its existing investment narrative.
J&T Global Express Investment Narrative Recap
To own J&T Global Express, you need to believe that parcel density, automation and cross border reach can offset pressure on yields, especially in China. The latest volume update signals that demand for its network remains healthy in key regions. For the near term, the main swing factor stays the same: can management convert heavy traffic into stable unit economics?
The biggest operational risk still sits in price competition and capital hungry expansion. Rapid parcel growth does not automatically fix revenue per parcel or cash generation. The new data does not materially change that trade off. It simply shows the firm continues to win volume, while execution on margins and capex discipline remains the key test.
With no fresh company specific announcements beyond these operating results, the most relevant context is still the earlier focus on automation and technology roll out across hubs and routes. Higher volumes running through more automated sorting and transport can strengthen that thesis because fixed investments are spread over a larger base of shipments.
For you as an investor, the link between this update and those prior plans sits in operating leverage. If J&T Global Express keeps feeding more parcels into the same or only slightly larger network, then the existing push into smart equipment, route optimization and partner models becomes even more important. Execution risk stays around whether pricing, cost savings and capex needs balance out as the network scales.
J&T Global Express' current analyst storyline points to revenues of US$24.9b and earnings of US$1.3b by 2029. That path assumes revenue growth of 20.1% per year and an earnings increase of roughly 3.6x from current earnings of US$362.1m.
Uncover how J&T Global Express' fair value indicates a 51% potential upside to its current price before sentiment narrows that valuation gap.
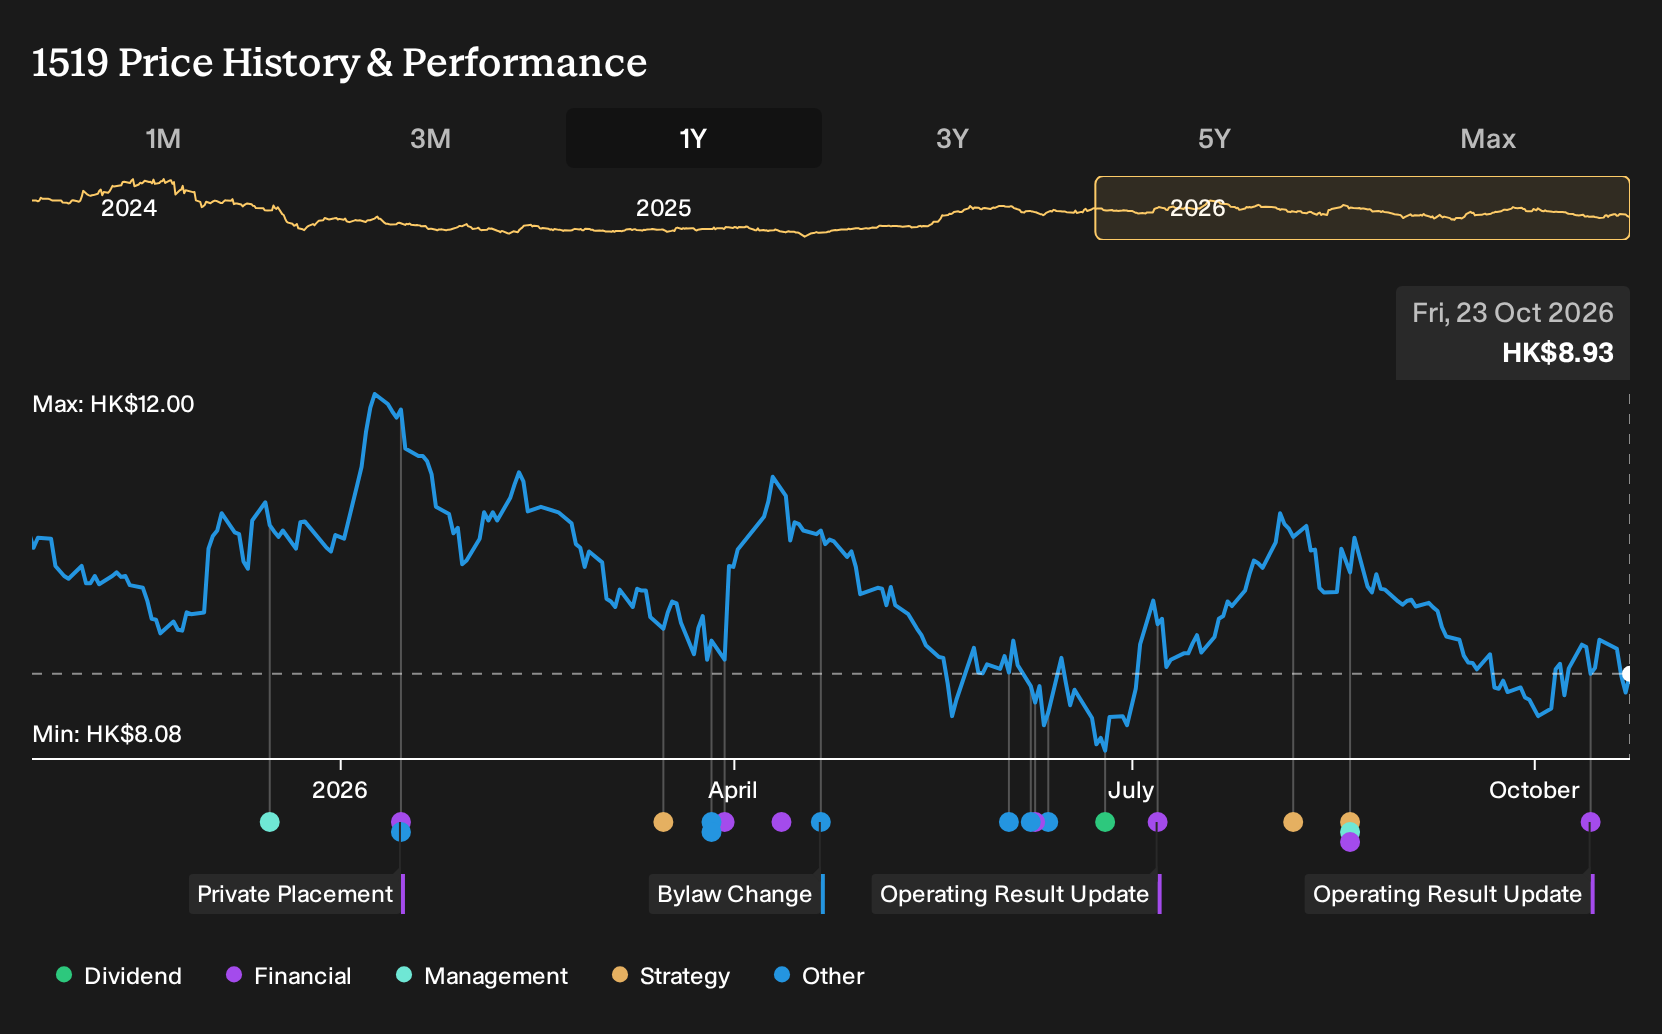
Exploring Other Perspectives
One alternate view on J&T Global Express leans hard into geopolitical risk. Those analysts worry that rising trade barriers cap cross border parcel flows and make today’s volume update less durable. Their forecasts were already sharper, with revenue assumptions around US$20.5b and earnings near US$962.2m by 2029. That gap shows how widely opinions differ and why you may want to compare several narratives once this new data filters into models.
Explore another J&T Global Express fair value estimate, including one that suggests it could be worth just HK$13.48.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your J&T Global Express research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for J&T Global Express. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J&T Global Express' overall financial health at a glance.
Looking for more investment ideas beyond J&T Global Express?
If J&T Global Express has sharpened your interest in logistics and broader equity opportunities, it can help to compare it with a wider set of listed businesses that share similar strengths or address very different goals in your portfolio.
- For investors focused on strong balance sheets over headline growth stories, start with this curated list of solid balance sheet and fundamentals (205 results) that prioritises financial resilience and funding flexibility.
- If you want potential mispriced opportunities backed by solid fundamentals, scan the 613 high quality undiscovered gems that often sit outside mainstream attention but still meet strict quality checks.
- When stability and capital preservation matter most, filter for companies that historically show lower risk scores through the 221 resilient stocks with low risk scores and see which profiles suit your long term plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com