


MakeMyTrip (MMYT) Could Be 44% Undervalued As Quick Ride Talks Raise The Stakes
MakeMyTrip (MMYT) is reportedly evaluating an acquisition of car and bike pooling platform Quick Ride through its redBus unit. The potential deal is currently in due diligence and is structured as a mix of cash and equity.
The Quick Ride talks land at a time when MakeMyTrip’s 1-day share price return declined 7.17%, capping a 7-day fall of 9.67% and a 30-day drop of 9.97%, while the 1-year total shareholder return is down 53.08% but still up 32.90% over five years. This suggests that short term momentum has faded even as long term holders remain in positive territory.
Scan how MakeMyTrip compares with other travel and consumer services plays that screen for 29 high quality undervalued stocks based on strong cash flows and balance sheets.
Bulls point to MakeMyTrip’s revenue and net income growth and the Quick Ride option, while bears focus on the share price slide. Which side do the current valuation and fundamentals lean toward?
Most Popular Narrative: 44% Undervalued
MakeMyTrip’s most followed narrative pegs fair value at $75.40 a share, well above the recent $42.09 close, so the gap to that thesis is wide.
The current valuation implies the market is pricing MakeMyTrip below what a bullish narrative would view as the full value of its market position, AI investments and planned India listing.
The shift of Indian travel from occasional to recurring consumption, with customers taking more frequent leisure, family, pilgrimage and short break trips across both air and ground transport, gives MakeMyTrip a larger base of repeat transactions to drive gross bookings and revenue.
See why 10 investors see MakeMyTrip as 44% undervalued.
Result: Fair Value of $75.40 (UNDERVALUED)
Still, the bullish MakeMyTrip story can break if higher oil prices keep airfares elevated, or if the India listing and convertible bonds dilute future earnings power.
Find out about the key risks to this MakeMyTrip narrative.
Another View: MakeMyTrip Looks Expensive On Earnings
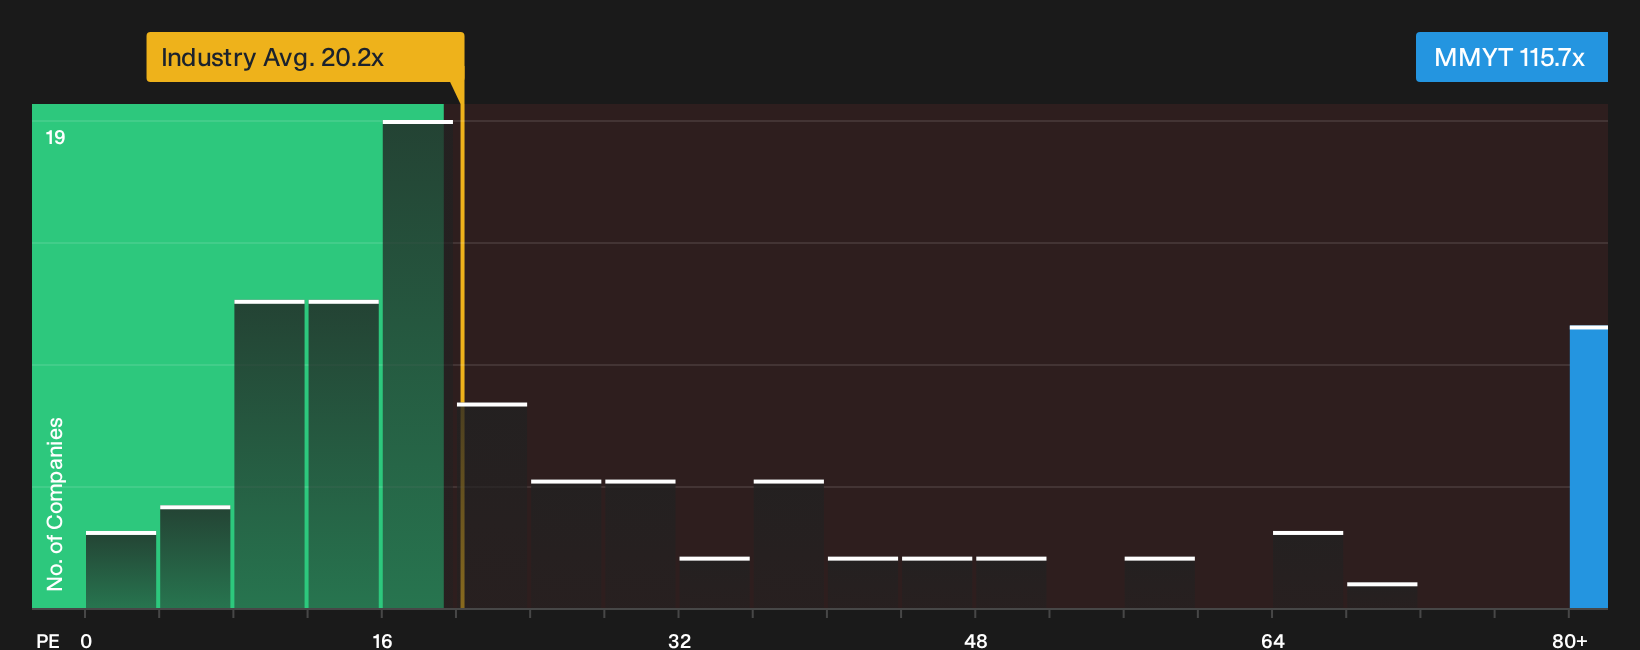
The 44% upside narrative looks different once you view MakeMyTrip through its current P/E. The stock trades at 115.7x earnings, compared with a fair ratio of 44.7x, a peer average of 16.2x and a US Hospitality sector level of 20.2x. This wide gap points to meaningful valuation risk if sentiment or forecasts shift. Which version of value do you trust more right now?
For a closer look at how those earnings multiples compare and what the fair ratio implies for possible repricing over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on MakeMyTrip is clearly split right now, which makes your own read of the data even more important. Take a moment to weigh both the upside potential and the downside flags by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MakeMyTrip?
If MakeMyTrip has your attention, do not stop there. Use the Simply Wall Street Screener to quickly surface other companies that might better fit your plan.
- Target resilient opportunities by zeroing in on 30 resilient stocks with low risk scores that aim to help keep portfolio swings in check.
- Spot potential mispricings early by scanning a curated 21 high quality undiscovered gems that many investors may not be watching yet.
- Support capital preservation by focusing on a list of solid balance sheet and fundamentals (24 results) that filters for robust financial footing before trouble shows up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com