


Ardelyx (ARDX) Stock Could Trade Below Fair Value After Lawsuit Filing
Ardelyx has gone through a wide range of outcomes for shareholders over the past few years, which raises a straightforward question for anyone looking at the stock today. Is the current share price sensibly linked to what the business is generating from its sales base?
- Over the past 5 years, Ardelyx has delivered a share price gain of about 154.5%, putting the focus squarely on whether that move still lines up with its underlying revenue profile.
- Recent real world data around XPHOZAH and IBSRELA, alongside allegations in a securities class action about how past commercial prospects were communicated, can both influence how investors think about the durability and potential scale of future sales streams.
- The analysts covering Ardelyx have run their own numbers. See what analysts think Ardelyx's shares could be worth.
The issue now is whether Ardelyx's current market value is adequately supported by its sales when set against the Fair Ratio benchmark.
If you want to pressure test this same sales linked valuation question across a wider set of companies, scan the 29 high quality undervalued stocks.
Is Ardelyx Still Cheap on Sales?
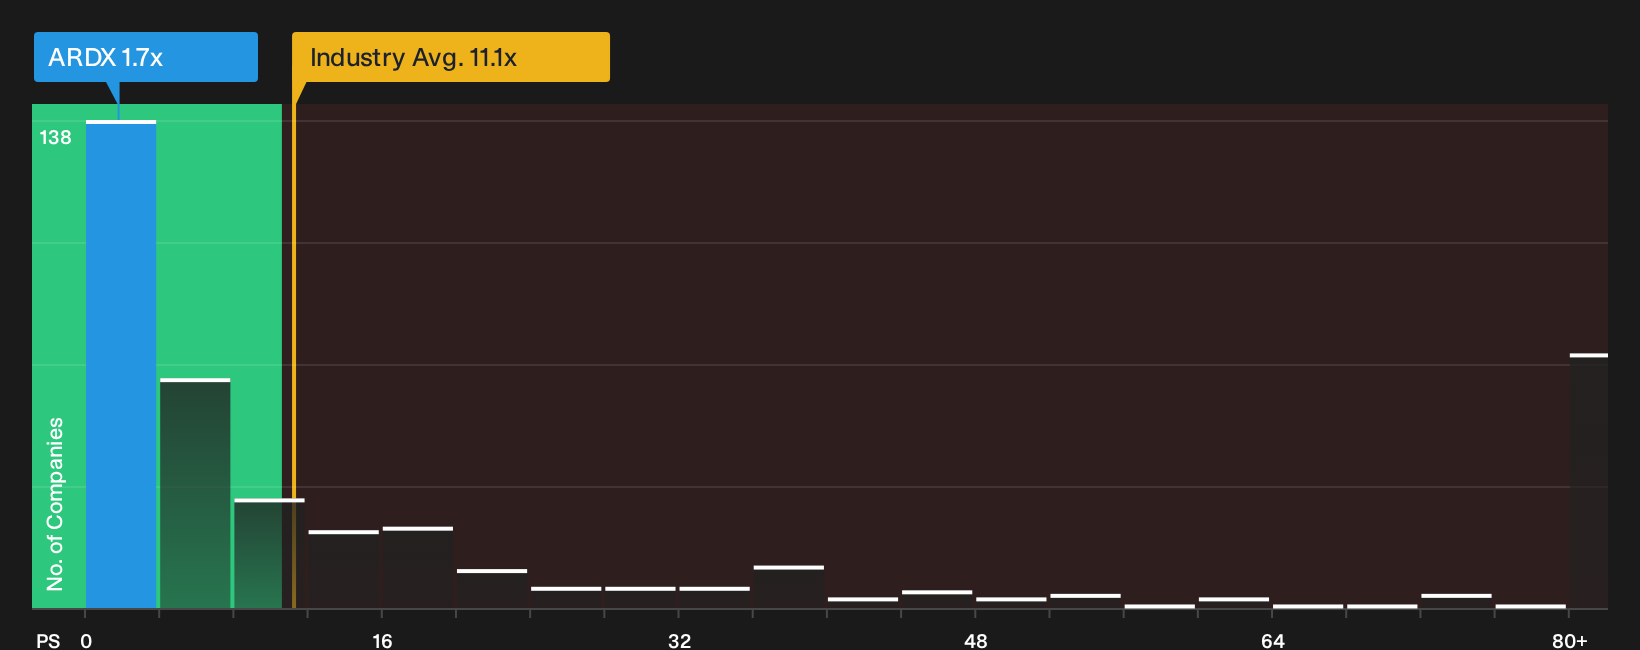
The P/S ratio tends to suit Ardelyx because the business is still building its earnings base while already generating a measurable level of product revenue. Ardelyx trades on a P/S of 1.7x, compared with about 11.1x for the broader biotechs sector and roughly 20.1x for peers in its group. On this framework, the stock changes hands at a marked discount to both its industry and closer comparables.
The tailored Fair Ratio, which reflects Ardelyx's own growth profile, margins, scale and risk, sits above the current 1.7x P/S level, so the shares screen as undervalued on this metric. Because the ongoing securities class action around XPHOZAH and IBSRELA guidance has raised questions about how past prospects were framed, this gap suggests investor caution has pulled the multiple below what the business fundamentals alone might imply. Explore the numbers behind Ardelyx's P/S valuation.
The Ardelyx Narrative: What Would Justify Today's Price?
Narratives pick up where Ardelyx's valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to occur for the shares to look meaningfully higher or lower than today. Each narrative treats Ardelyx's implied worth as a thesis about how the business could develop over time, so you can track whether the story it sketches is holding up against new information on Simply Wall St's Community page.
One of the top community narratives on Ardelyx: 76% undervalued
"Strategic partnerships and licensing deals, including existing international collaborations and potential future EU partnerships, provide non-dilutive capital through milestones and royalties..."
Discover why this Narrative puts Ardelyx at 76% undervalued.
Before moving on from Ardelyx, one more factor deserves space in your thinking
The people steering Ardelyx and the way they are rewarded can either reinforce the current valuation story or quietly pull against it, so it pays to see how those incentives really line up. See who runs Ardelyx and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com