


i-80 Gold Shares Rose Even As Sales Fell
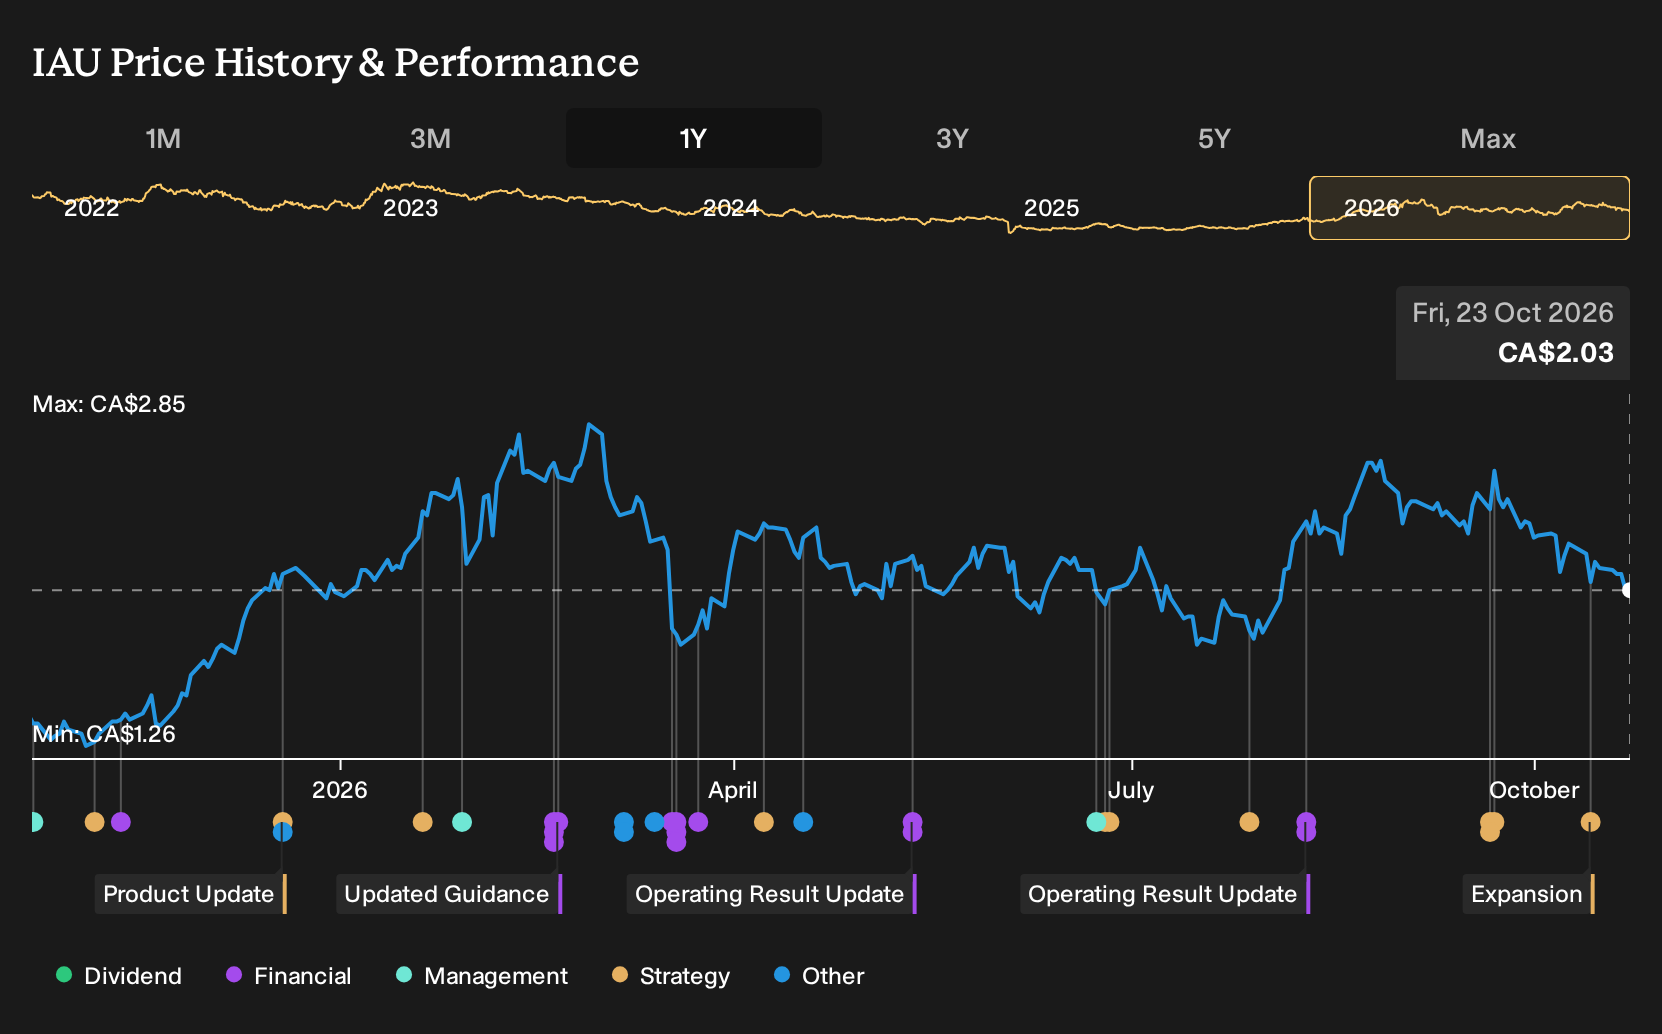
i-80 Gold spent the year telling a mixed story. Progress updates on Nevada projects arrived alongside quarterly figures that showed revenue and profit both declining, with net margin falling from 108.5% to 215.7% negative. Holding i-80 Gold over the past year would have returned 48.2%, including dividends. If you were weighing that decision in October 2025, how should you have compared upbeat project milestones with a deeper reported loss?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
i-80 Gold has already moved. Pinpoint other ways to investigate the theme among 35 elite gold producer stocks.
The Argument You Would Have Been Weighing On i-80 Gold
The shares cost CA$1.37 at the start of the period, and the disagreement was about how far i-80 Gold could run if its Nevada build out went to plan.
The optimistic Narrative pointed to a Fair Value of CA$2.28, tied to assumptions that revenue could grow 72.4% a year and that margins might move from a deep loss to a 17.3% profit level by around 2028.
The cautious Narrative anchored on a Fair Value of CA$1.05, built around 57.0% revenue growth, a 27.1% profit margin assumption, and concern about heavy funding needs of roughly CA$900m to CA$950m.
What The Results Changed For The i-80 Gold Argument
The clearest development for i-80 Gold came from project execution. Archimedes, Granite Creek and Lone Tree all moved toward planned production and processing, while more than US$1b of financing and a terminated gold offtake agreement increased flexibility. At the same time, Q2 2026 revenue slipped to US$24.3m and the firm reported a deeper loss, with net margin falling to 215.7% negative. The evidence cut both ways.
The episode turned on one assumption. You had to judge whether faster Nevada build outs and drilling progress would outweigh ongoing reported losses. When you look at similar developers, track two things in each report. First, check whether project timelines and funding plans stay intact. Second, compare that against the direction of net margin and absolute profit.
What Today's i-80 Gold Price Already Assumes
Today i-80 Gold trades at CA$2.03, after a 48.2% gain over the past year. The selected bullish Narrative argues that its Fair Value sits above that level, rooted in expectations around Nevada production ramp up and the shift to more in-house processing.
On that view, the current quote still leaves little credit for successful execution at Lone Tree and continued reserve growth across the Nevada portfolio.
"Progress towards commissioning the refurbished Lone Tree autoclave by 2027 (potentially earlier), which will drive much higher gold recovery rates (from approximately 55% to 60% to approximately 92%) and lower operating costs per ounce compared to third-party toll milling, should significantly expand net margins and operational cash flow."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond i-80 Gold
i-80 Gold focuses your attention on Nevada builds and processing choices. You can also look one step away.
Some explorers work earlier in the chain. Their role is turning historical resource work and fresh drilling into a modern technical picture.
One such business is updating a long-standing gold and copper project. It is blending older estimates with recent core, assays and modelling.
The new study will reassess how much mineralisation fits an economic shell. It will also factor in copper and silver, which could reshape project economics.
If that picture changes meaningfully, your view of value across this part of the sector might shift too.
One Narrative has already put a figure on it. → Uncover the company trading 66% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com