


Rocket Lab (RKLB) Stock Looks Above Fair Value On Its Three Year Run
Rocket Lab has swung from sharp drawdowns in recent months to a very large gain over the past three years. That puts a simple question front and center for you as an investor: Is the current share price really backed up by the company’s sales today and what those sales could reasonably turn into over time?
- Over the past three years, Rocket Lab has delivered a return of more than 10x. As a result, a lot now rests on whether its revenue base can carry that kind of re-rating.
- The latest delay to the Neutron rocket’s maiden flight pushes expected revenue and cash inflows further out. This can reshape how you think about the timing of sales growth that might one day justify the current valuation.
- The analysts covering Rocket Lab have run their own numbers. See what analysts think Rocket Lab's shares could be worth.
The issue now is whether Rocket Lab’s present market value is reasonably supported by its sales, once you line it up against what buyers are typically willing to pay on this lens.
If you want to explore the same question you are asking about Rocket Lab across a wider field, compare this against 29 high quality undervalued stocks.
Has Rocket Lab Run Too Far on Sales?
P/S fits Rocket Lab because investors are focusing more on what the business can generate in revenue than on current earnings.
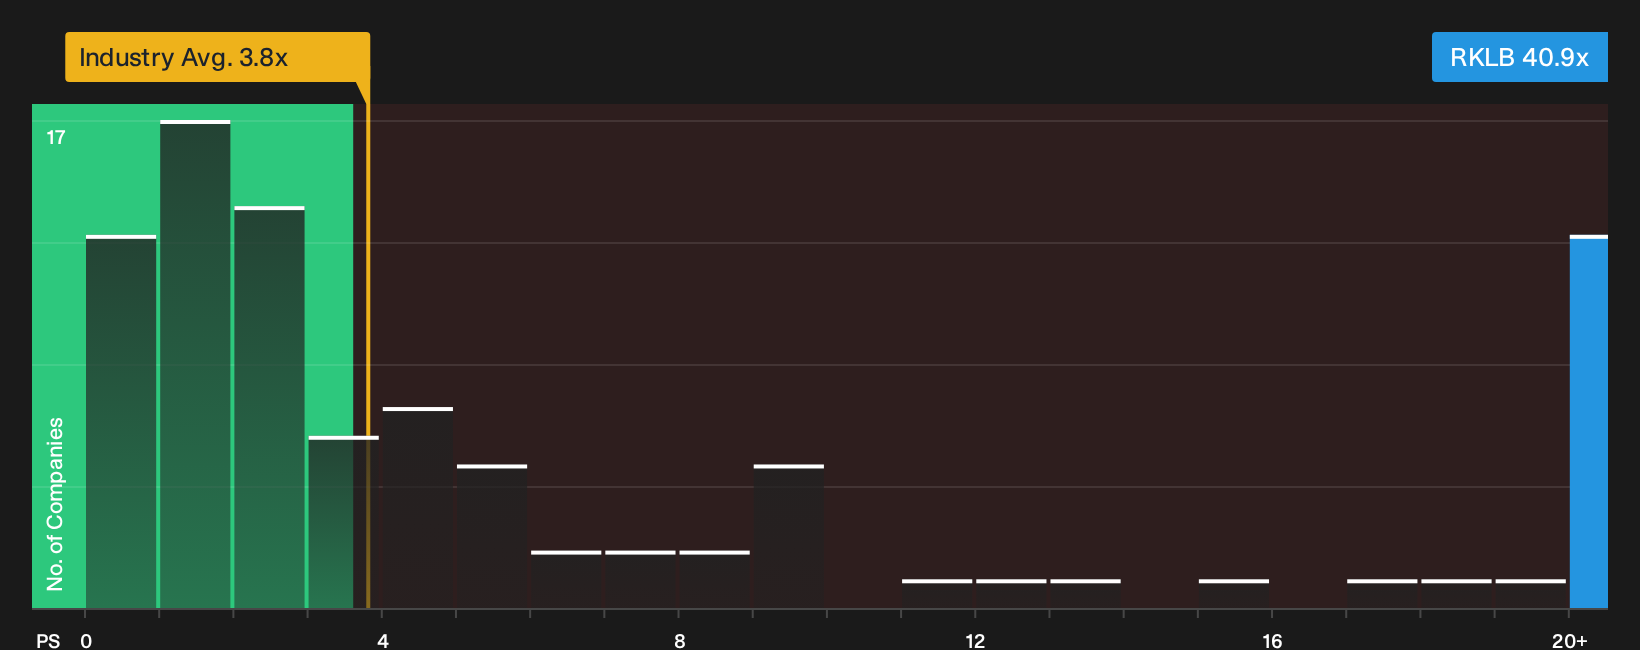
On this lens, Rocket Lab trades at about 40.9x P/S, far above the Aerospace & Defense industry average of roughly 3.8x and a peer group closer to 7.1x. The tailored fair multiple from the model, which factors in the company’s growth profile, margins, scale and risk, sits materially lower, so the current P/S screens as overvalued on this framework. Because the gap is very wide, the fair level is better read as a warning flag that the valuation is highly demanding rather than a precise target.
Despite the recent Neutron launch delay pushing revenue expectations further out, the market is still assigning Rocket Lab a sales multiple that implies a much richer profile than sector norms and closer peers. That calls for you to weigh how comfortable you are with execution risk, the timing of future contracts and how durable the current revenue base really is before leaning on this P/S figure. Explore the numbers behind Rocket Lab's P/S valuation.
The Rocket Lab Narrative: What Would Justify Today's Price?
For Rocket Lab, Simply Wall St Narratives pick up where the P/S puzzle leaves off and describe the future path for growth, margins and earnings that would need to occur for the stock to be worth materially more or materially less than today’s price. Instead of giving a single figure from a ratio or model, these Narratives explain the specific future that figure relies on so you can monitor whether reality is tracking that story over time on the Community page.
Rocket Lab splits the community sharply, with one camp treating the current price as an entry into a much larger space business and the other arguing the shares already bake in a flawless Neutron outcome.
Bull case: 46% undervalued
"Rocket Lab USA seeks to vertically integrate itself throughout the $800 billion space 'backbone' in order to attract the customers operating within that $1 trillion top component of the 'space economy'..."
Discover why this Narrative puts Rocket Lab at 46% undervalued.
Bear case: 224% overvalued
"The entire valuation is 'priced for perfection,' which means any delay causes volatility..."
Explore why this Narrative puts Rocket Lab at 224% overvalued.
Rocket Lab’s valuation is only half the story
Before treating the current P/S as the full picture on Rocket Lab, it helps to know that our broader checks have picked up specific concerns that deserve a closer look from you. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com