


Japan Post Holdings (TSE:6178) Falls Back As Valuation Questions Return
Japan Post Holdings (TSE:6178) drew fresh attention after its recent share move, with the stock down 9.2% over the past month and 7.1% over the past 3 months.
The recent slide has softened short term momentum, with the share price down 9.2% over the past month. Even so, Japan Post Holdings still carries a year to date share price return of 35.4% and a 1 year total shareholder return of 65.68%, which points to strong earlier enthusiasm now being reassessed as investors recalibrate growth expectations and risk.
Scan how other insurers and financials with solid fundamentals are trading by comparing Japan Post Holdings against our curated list of solid balance sheet and fundamentals (23 results).
Japan Post Holdings now trades below analyst targets while sitting roughly in line with some fair value estimates. Is this discount a genuine opportunity, or a signal that the market’s caution is warranted?
Price-to-Earnings of 14.8x: Is it justified?
On earnings, Japan Post Holdings trades on a P/E of 14.8x, which lines up with a market that is willing to pay a reasonable price for current profits but is not offering a clear bargain relative to closer peers.
The P/E ratio compares the share price to per share earnings and gives a quick sense of how much investors are paying for each unit of profit. For a diversified financial and insurance group like Japan Post Holdings, this metric is a common shorthand for how the market weighs its earnings profile, forecast growth and perceived risk.
Against the domestic Insurance industry, that 14.8x multiple sits slightly below the Japan Insurance average of 15.4x. This suggests local investors are not stretching to pay up for Japan Post Holdings compared with home market peers. The fair P/E ratio estimate of 17.7x points to a level the market could move toward if sentiment around its earnings quality and growth forecasts were to align with that model.
On a broader regional view, the picture shifts. The same 14.8x P/E looks expensive compared with the wider Asian Insurance industry average of 10.4x and also above the narrower peer group average of 11.9x. This shows investors are already paying a premium versus many regional alternatives even before considering any move toward the 17.7x fair value signal.
Explore the SWS fair ratio for Japan Post Holdings.
Result: Price-to-Earnings of 14.8x (ABOUT RIGHT)
Still, Japan Post Holdings depends heavily on domestic demand and interest rate conditions, so weaker postal volumes or pressure on financial margins could quickly change how that 14.8x P/E looks.
Find out about the key risks to this Japan Post Holdings narrative.
Another view on Japan Post Holdings
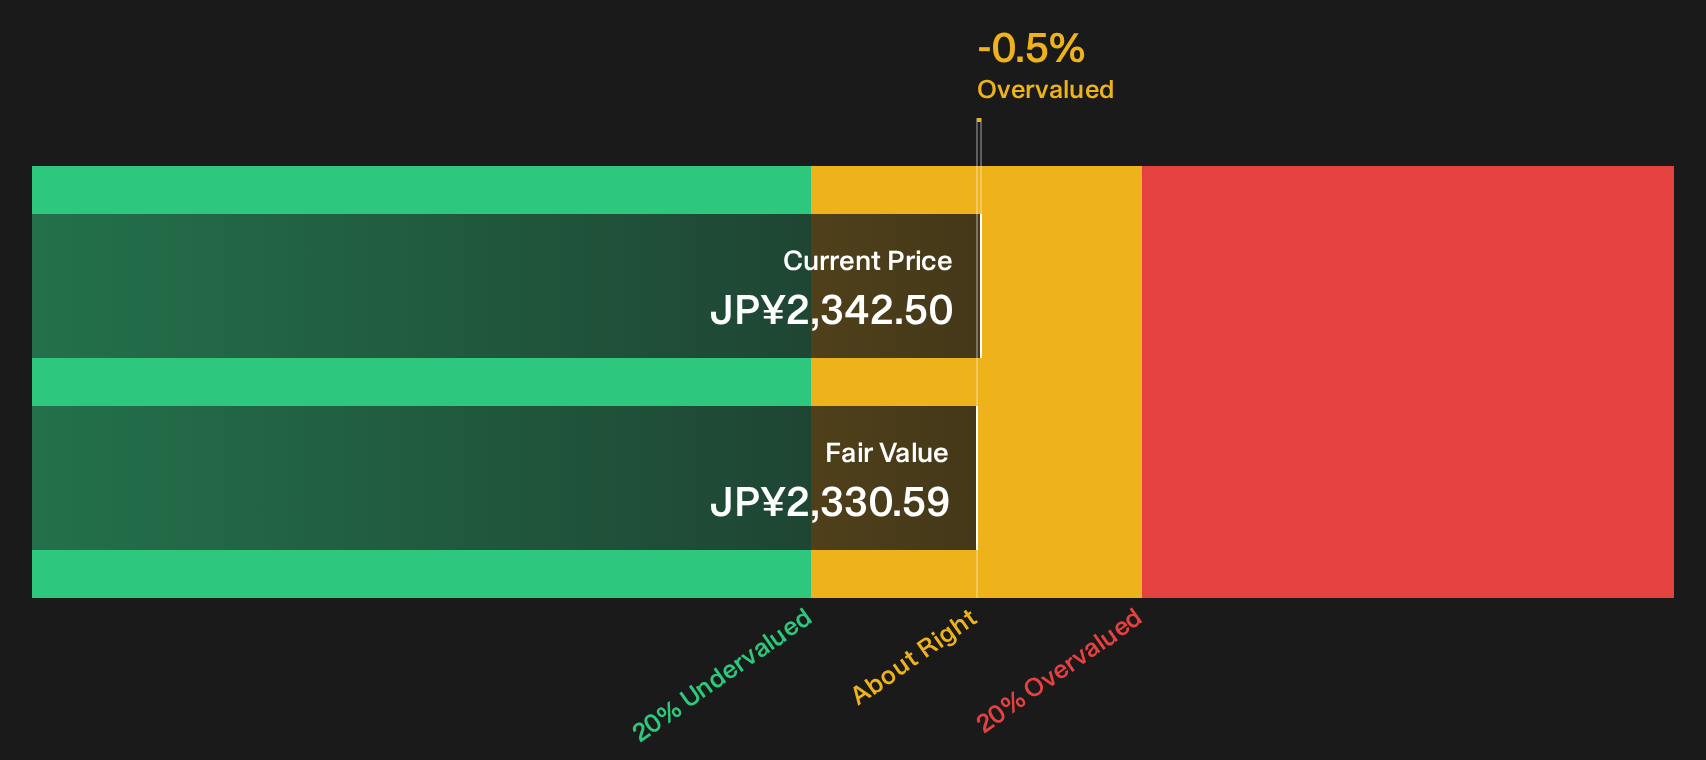
On a cash flow lens, the picture shifts. Japan Post Holdings at ¥2,342.5 is trading slightly above the SWS DCF model estimate of future cash flow value at ¥2,330.59, which points to the shares being marginally overvalued on this approach rather than clearly cheap.
That kind of tight gap between price and model value leaves little room if forecasts or interest rate assumptions change, so it raises a fair question for investors. Is this a margin of safety you are comfortable with, or is it a signal to demand a bigger discount for uncertainty?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Post Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals can feel uncomfortable, especially when a stock like Japan Post Holdings has both clear risks and clear potential upsides on the table. It may help to act promptly, review the underlying data, and decide whether the balance suits your approach by weighing its 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Japan Post Holdings?
If Japan Post Holdings no longer feels like the only contender, do not sit on the sidelines while other opportunities line up for your watchlist.
- Target resilience first by checking companies with stronger balance sheets and fundamentals through our focused list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricing by scanning a curated pool of quality stocks that screen as attractively valued in the 14 high quality undervalued stocks.
- Strengthen your income layer by reviewing companies with higher yields and sturdier payouts inside the 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com