


Is WSFS Financial (WSFS) Undervalued Following Its Third Quarter Earnings Beat?
WSFS Financial (WSFS) just posted third quarter 2026 results that showed higher net income, earnings per share, and net interest income versus a year earlier, alongside a reaffirmed quarterly dividend of US$0.20 per share.
At a share price of US$79.02, WSFS Financial has seen a strong year so far, with a year to date share price return of 43.54% and a 1 year total shareholder return of 50.68% that reflects both price gains and dividends.
Spot opportunities beyond WSFS Financial by scanning a curated set of banks and financials that currently screen as 29 high quality undervalued stocks.After that earnings beat and a 43.5% year to date surge, WSFS Financial still trades below both intrinsic value estimates and analyst targets. Is the market’s caution on funding and credit risks offering a genuine discount?
Most Popular Narrative: 11% Undervalued
Against WSFS Financial's last close of $79.02, the most followed narrative pins fair value near $88.92, so the story leans toward undervaluation with a 7.2% discount rate doing the heavy lifting in the model.
Continuation of high core ROA and core ROTCE, together with capital levels above the stated CET1 target, provides room for WSFS Financial to keep returning a large portion of earnings through share repurchases, which can lift earnings per share even if overall revenue growth is modest.
See why 0 investors see WSFS Financial as 11% undervalued.
Result: Fair Value of $88.92 (UNDERVALUED)
Still, the WSFS Financial narrative depends on deposit costs staying contained and on Cash Connect avoiding a sharp revenue hit if rate cuts and lower volumes persist.
Find out about the key risks to this WSFS Financial narrative.
Another View: What P/E Says About WSFS Financial
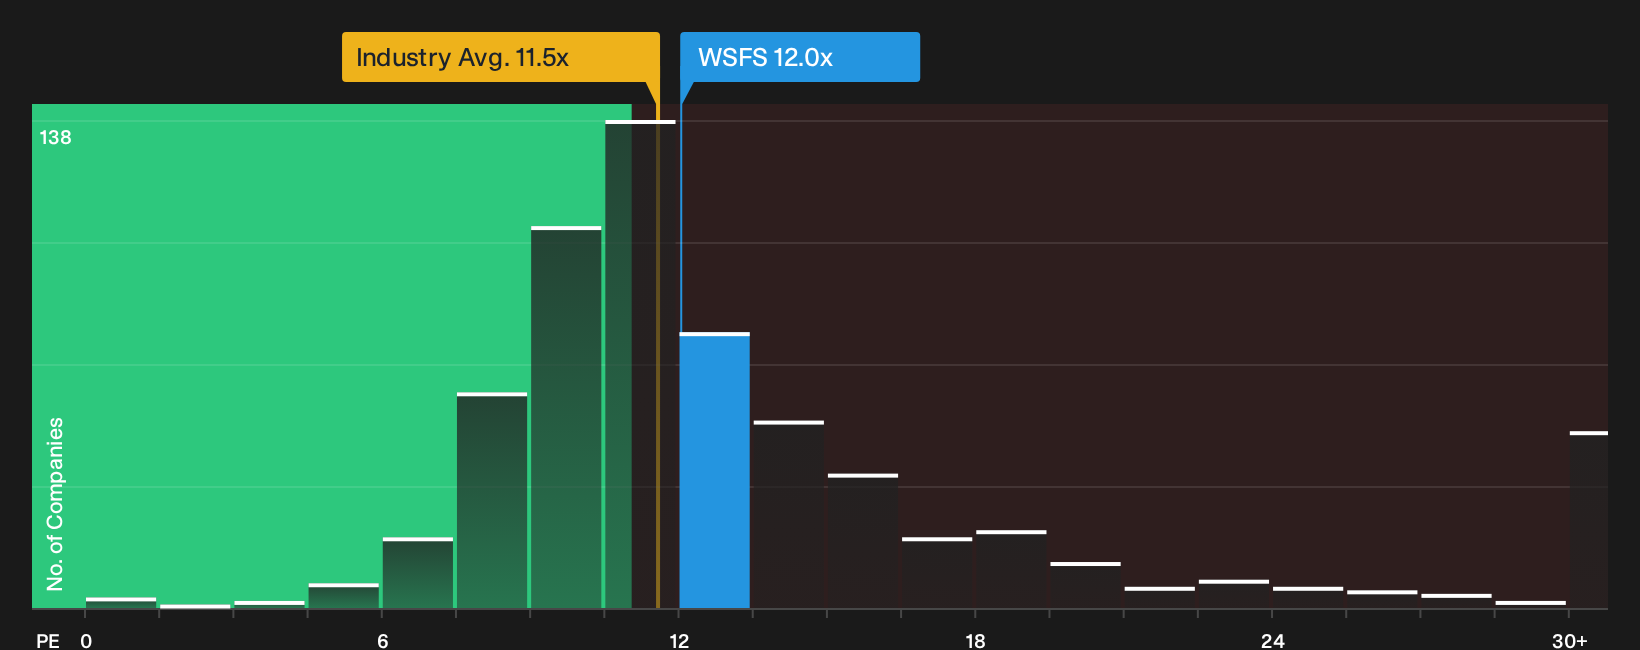
On simple P/E math, WSFS Financial looks less generous. The stock trades on about 12x earnings, slightly above both the US Banks group at 11.6x and an estimated fair ratio of 10.6x, which points to less margin for error if the story softens.
That richer multiple sits alongside a narrative that still flags funding costs, Cash Connect sensitivity and only moderate forecast growth. If earnings or credit trends fall short of expectations, how quickly could that valuation premium unwind for current shareholders?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on WSFS Financial so far, with both risk flags and upside markers on the table, mean the next move is yours to assess. To see the balance between what could go right and what could go wrong, start by weighing the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond WSFS Financial?
Do not stop with a single bank when the market is packed with other opportunities that could fit your risk profile or income goals just as well.
- Target potential underpriced opportunities by scanning a curated pool of quality companies that currently screen as 29 high quality undervalued stocks.
- Strengthen your focus on resilience and capital strength by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you filter for sturdier balance sheets.
- Spot potential early-stage opportunities before they are widely followed by checking a handpicked set of 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com