


Imperial Oil (TSX:IMO) Could Be 14% Overvalued Before Quarterly Earnings
Imperial Oil earnings report draws investor focus
Imperial Oil (TSX:IMO) heads into next week with attention on its upcoming quarterly earnings release, where the market is watching how actual results stack up against expectations of $3.43 per share.
Recent trading has been strong overall, with the share price up 8.62% over the past month and 54.30% year to date. A 51.37% total shareholder return over the past year and a very large 5 year total shareholder return suggest that momentum around Imperial Oil is still building rather than fading.
Scan for other energy stocks showing similar pre earnings momentum to Imperial Oil by reviewing the curated 3 high quality undervalued stocks now.
After a 54.30% year to date climb, Imperial Oil now sits near CA$188.72 and expectations are high. Is most of the upside already captured, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 14% Overvalued
On Simply Wall St’s most followed narrative, Imperial Oil’s fair value sits at about CA$165.59, which is below the last close at CA$188.72. That gap puts the upcoming earnings release into sharp focus as investors weigh how much of the long term story is already reflected in the price.
The numbers and this narrative’s view that Imperial Oil is fairly valued imply the share price already reflects both the company’s recent free cash generation and its commitment to return surplus cash through dividends and buybacks.
See why 30 investors see Imperial Oil as 14% overvalued.
Result: Fair Value of CA$165.59 (OVERVALUED)
Still, tighter decarbonization rules or sustained high maintenance needs at Kearl, Syncrude and Cold Lake could pressure Imperial Oil’s cash generation narrative.
Find out about the key risks to this Imperial Oil narrative.
Another View: Imperial Oil’s P/E Tells A Different Story
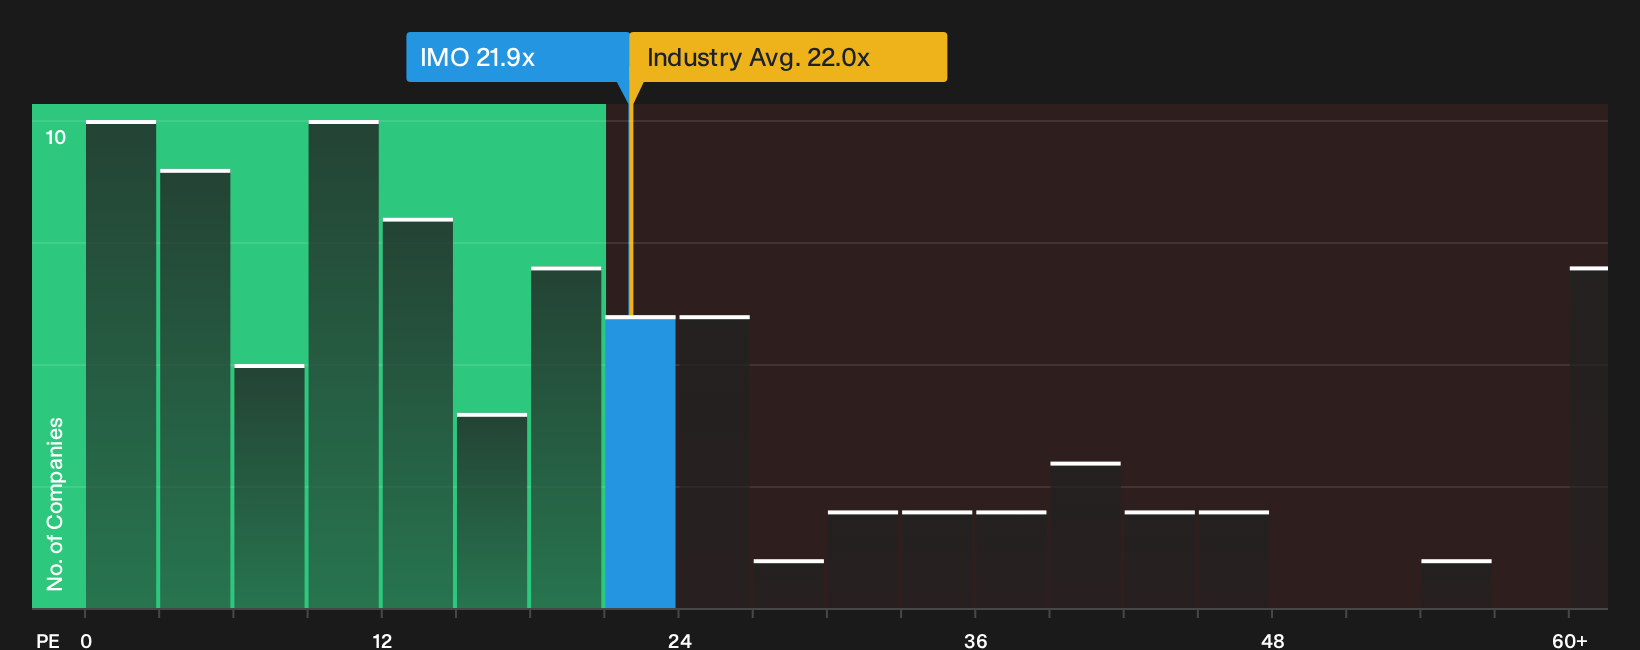
While the Simply Wall St fair value narrative flags Imperial Oil as 14% overvalued around CA$165.59, the current P/E of 21.9x adds another layer. That multiple sits just above the 16.1x fair ratio estimate and roughly in line with the 22x Canadian Oil and Gas industry average.
In practice, this means investors are paying a premium to the fair ratio and only a tiny discount to the wider sector, even as earnings are forecast to decline by about 2% per year over the next three years and revenue is expected to edge down by 0.5% annually. Is that pricing you are comfortable with for Imperial Oil at CA$188.72?
To stress test this view against a more detailed relative-pricing breakdown, review the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how Imperial Oil’s valuation stacks up beside peers, have a look at
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Imperial Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and earnings expectations can pull you in opposite directions, so move quickly from headline takes to your own checklist of facts. To weigh both the upside story and the areas of concern in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Imperial Oil?
If Imperial Oil has your attention, broaden your watchlist so you are not relying on a single story when markets move fast.
- Target steady income potential by reviewing dividend payers screened for resilience through the 3 dividend fortresses.
- Hunt for mispriced opportunities by scanning companies that combine quality fundamentals with cheaper valuations through the 9 high quality undiscovered gems.
- Prioritize capital preservation by focusing on businesses with stronger financial footing using the list of solid balance sheet and fundamentals (7 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com