


Should Dividend Hike Require Action From Prosperity Bancshares Stock Investors?
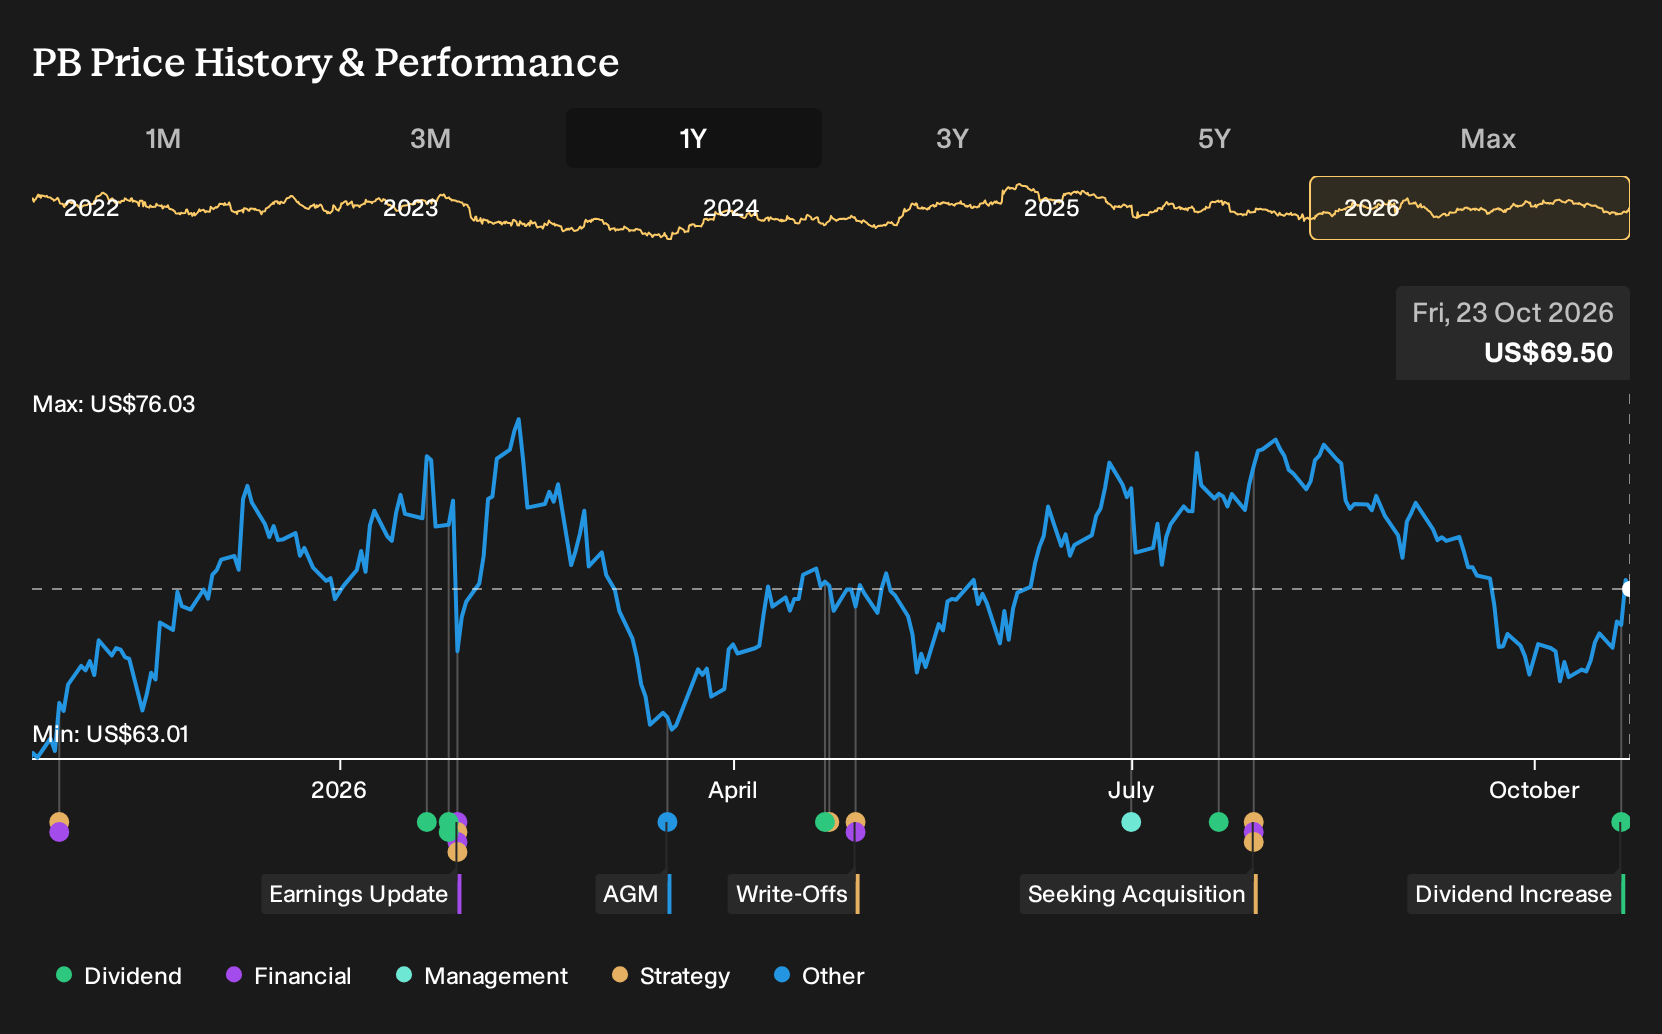
- Prosperity Bancshares' board approved a higher fourth quarter 2026 dividend of US$0.64 per share, a 6.67% increase, payable on January 4, 2027 to shareholders of record on December 15, 2026.
- The richer payout signals management's willingness to return more capital, even as the business focuses on integrating recent acquisitions and maintaining operating efficiency across its Texas and Oklahoma footprint.
- We will now see how Prosperity Bancshares' investment narrative could be influenced by this higher dividend commitment.
Prosperity Bancshares Investment Narrative Recap
To own Prosperity Bancshares, you need to be comfortable with a relatively traditional regional bank story. The focus is on integrating recent acquisitions, keeping the efficiency ratio in the mid 40% range and using a low cost deposit base to support net interest margin. The higher dividend is a sign the board is sticking with this capital return playbook.
The near term swing factor is still execution on credit quality and loan growth, not the dividend bump. Pressure from shared national credits and flattish legacy loan balances keeps asset quality and balance sheet momentum in focus. If those hold steady, the higher payout mainly tweaks income rather than the core thesis.
The most relevant datapoint alongside the dividend increase is Prosperity Bancshares’ record of beating earnings expectations in the last two quarters, with a positive Earnings ESP of 0.22% going into the 28 October 2026 report. That track record has kept attention on whether reported profit matches the cost save and margin story.
If upcoming results align with prior beats, it would support the idea that integration, funding costs and net interest margin guidance are tracking to plan. That matters more than any single dividend move. A miss, especially if tied to higher net charge offs or weak organic loans, would keep the credit and growth risks front and centre despite the richer payout.
Prosperity Bancshares' current analyst narrative anchors on revenue reaching about US$2.5b and earnings of roughly US$1.1b by 2029. This outlook is built on an assumed 21.1% yearly revenue increase and an earnings step up of about US$537.7m from the US$562.3m reported today.
Uncover how Prosperity Bancshares' fair value indicates a 17% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$81.54 to US$117.99, so retail views on Prosperity Bancshares already cover a wide valuation band. When you set those against ongoing risks around nonperforming loans and flattish legacy balances, you can see why opinions may differ sharply, making it worth exploring multiple viewpoints.
Explore another Prosperity Bancshares fair value estimate, including one that suggests up to 70% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Prosperity Bancshares research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prosperity Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prosperity Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Prosperity Bancshares?
If Prosperity Bancshares has sharpened your focus on income, balance sheet strength and valuation, it can be helpful to widen the lens and scan for other stocks that fit your preferences using the Simply Wall St Screener.
- For investors who want potential upside with quality fundamentals, check out a curated set of 21 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation ranks high for you, focus on stability first by reviewing a 30 resilient stocks with low risk scores that screens for resilience according to Simply Wall St's risk model.
- Income seekers who care about staying power can compare Prosperity Bancshares' yield with a list of solid balance sheet and fundamentals (24 results) to find dividend payers backed by stronger finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com