


How Investors May Respond To FLSmidth (CPSE:FLS) North America Gold Mill Order
- FLSmidth & Co. A/S reported a DKK 225 million order to supply its mill technologies, including SAG and ball mills with FLS Armour liners, to a North American gold project. Installation and commissioning are planned for 2028, with booking in the third quarter of 2026.
- The contract underlines ongoing demand for FLSmidth’s mineral processing equipment and adds visibility to the equipment backlog, even though financial guidance for 2026 remains unchanged.
- We will now assess how this large North American grinding order could shape FLSmidth’s investment narrative around mining focused growth.
Compare FLSmidth’s mining-focused momentum with other targeted opportunities by scanning our hand picked 16 top copper producer stocks that may benefit from similar long term metals demand themes.
FLSmidth Investment Narrative Recap
To own FLSmidth, you need to believe the mining focused model can keep turning equipment orders and a growing service base into steadier earnings and eventually stronger cash generation. The big near term swing factor is still whether the Product segment and large greenfield projects convert from pipeline to revenue without long gaps or execution hiccups.
The key risk remains weak cash conversion and working capital tied up in big projects, which could limit firepower for acquisitions or shareholder payouts. The new gold grinding order and leadership changes do not appear to materially change that near term equation, although they do add some operational and backlog visibility.
The appointment of Gonzalo Del Carpio as Chief Operational Excellence Officer looks most relevant here. FLSmidth is trying to scale Services, Products and Pumps, Cyclones & Valves while also pursuing acquisitions. As a result, a dedicated focus on process discipline and simplification matters for whether margins and project delivery stay on track.
This role sits alongside new ELT hires in strategy, M&A and People. The entire leadership bench is being refreshed while the company is still working through cash flow pressure and integrating large orders like the North American grinding package. For you as an investor, execution quality under this relatively new team is now a central catalyst and a clear operational risk.
What The Current FLSmidth Forecasts Assume
FLSmidth's narrative projects DKK 18.5 billion revenue and DKK 2.1 billion earnings by 2029. This builds on analysts assuming 7.9% yearly revenue growth and an earnings increase of about DKK 500 million from DKK 1.6 billion today.
For you as an investor, these consensus numbers sketch out a simple picture. Analysts are effectively saying the mining focused model needs to turn mid single digit revenue expansion into slightly better margins, then translate that combination into higher profit and cash over the next several years.
The forecast path assumes revenue growing by 7.9% each year, while profit margins move from 10.6% to 11.4%. That mix of top line progress and modest margin uplift is what underpins the expectation of earnings at DKK 2.1b by 2029.
The earnings bridge matters. The step up from DKK 1.6b today to a consensus DKK 2.1b implies roughly DKK 500m more profit, which needs to come from steadier project execution, a larger installed base in Services and Pumps, Cyclones & Valves, and fewer problem contracts in Products.
On these estimates, FLSmidth would be trading on a P/E of 18.4x 2029 earnings compared with about 20.0x today. Analysts are therefore baking in a slightly lower valuation multiple on higher earnings, which suggests the story depends more on delivery of that extra DKK 500m than on re rating.
The valuation sketch includes another moving part. Consensus assumes shares outstanding shrink by roughly 3.41% each year for the next three years, which, if it happens, would mechanically lift earnings per share even if absolute profit stayed flat.
Discounting those future cash flows at about 6.7% to 6.72% is the final ingredient used in the external models. For you, the practical takeaway is that any change in perceived risk, cost of capital or long term mining activity would flow directly into how that discount rate and the resulting fair value are set.
Uncover why FLSmidth's fair value indicates an 18% potential upside to its current price that could narrow quickly.
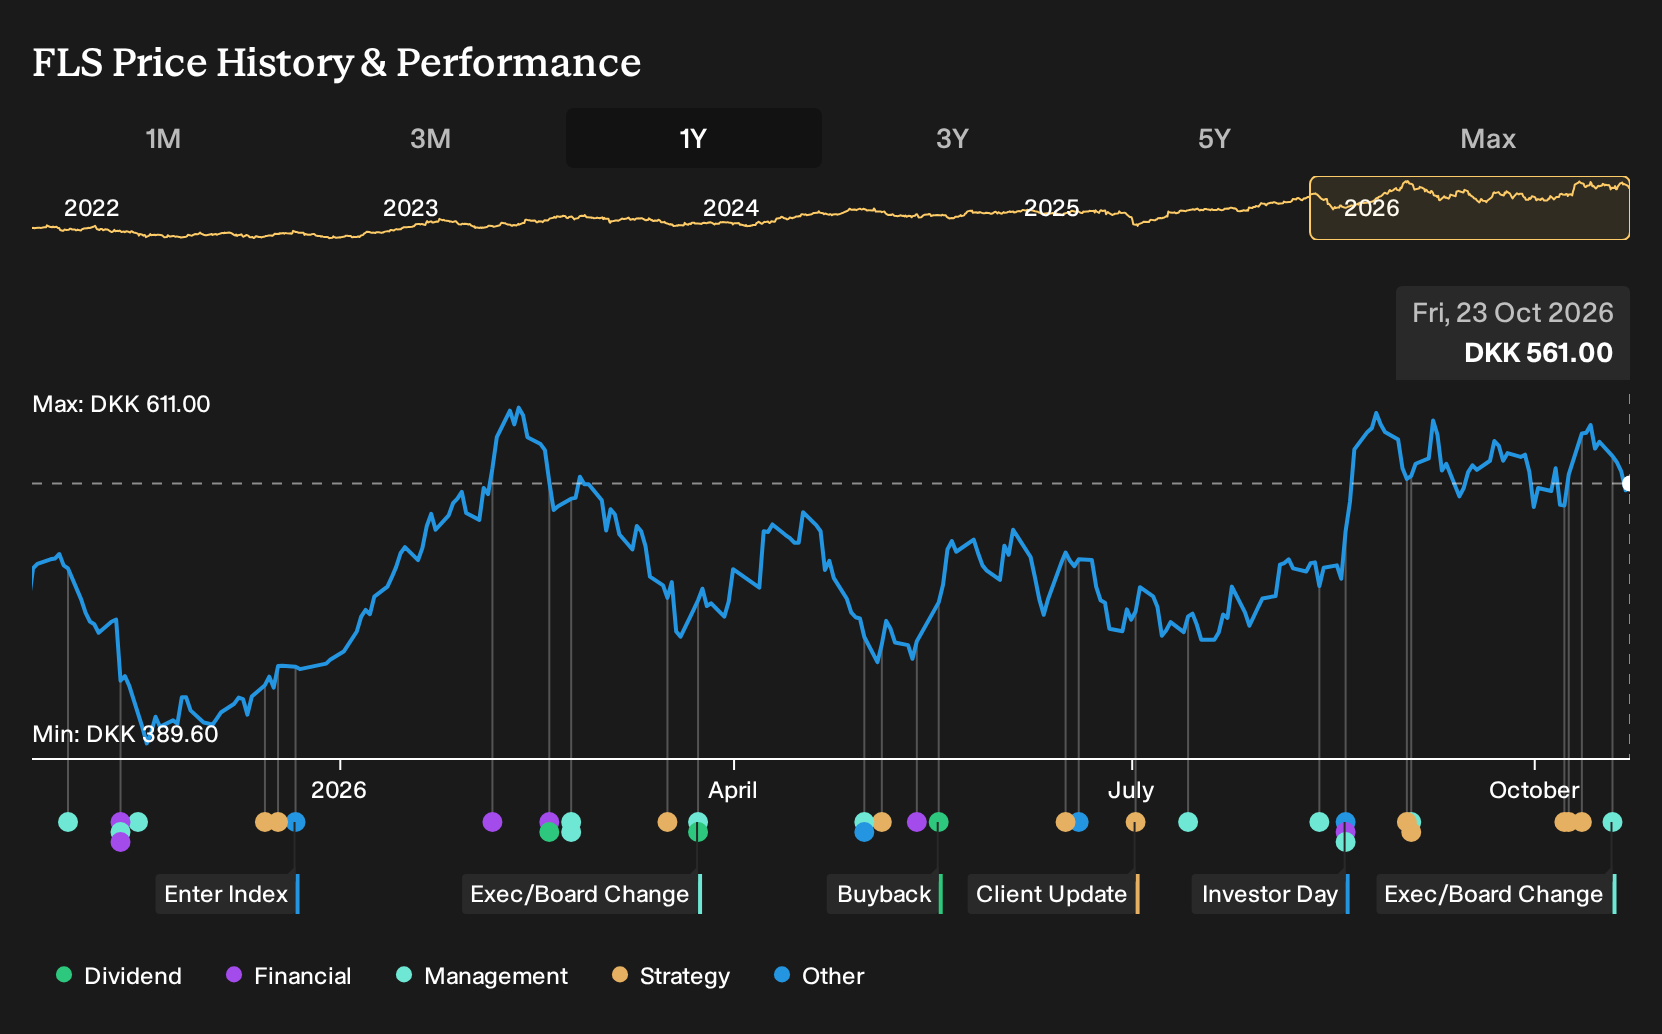
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for FLSmidth. They lean heavily on the idea that services and Pumps, Cyclones & Valves, at roughly 80% of revenue, can support the bullish case. Before this gold grinding order and the new operational excellence role, the highest forecasts were already assuming about 9.6% annual revenue growth and DKK 2.2b earnings by 2029. That is much more upbeat than the lower end expectations near DKK 1.7b. Your own view on this leadership change and the new DKK 225m contract may influence where you position yourself between those narratives.
Explore 2 other FLSmidth fair value estimates, including one that suggests as much as 63% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your FLSmidth research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FLSmidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review FLSmidth's overall financial health at a glance.
Looking For More Investment Ideas Beyond FLSmidth?
If the FLSmidth story has sharpened your thinking about risk, cash flow and execution, it can be useful to compare it with other opportunities that share some of the same traits or offer a different balance of quality and valuation. The Simply Wall St Screener lets you quickly filter for the kind of business profile that fits your approach.
- If you want a focus on quality at a discount, start with a curated group of sturdier businesses through our 195 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, narrow the field to companies with cleaner finances using this list of solid balance sheet and fundamentals (205 results).
- If you are hunting for fresher stories with solid fundamentals, scan a tighter pool of potential future leaders via our 612 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com