


How Investors May Respond To 1st Source (SRCE) Earnings Beat
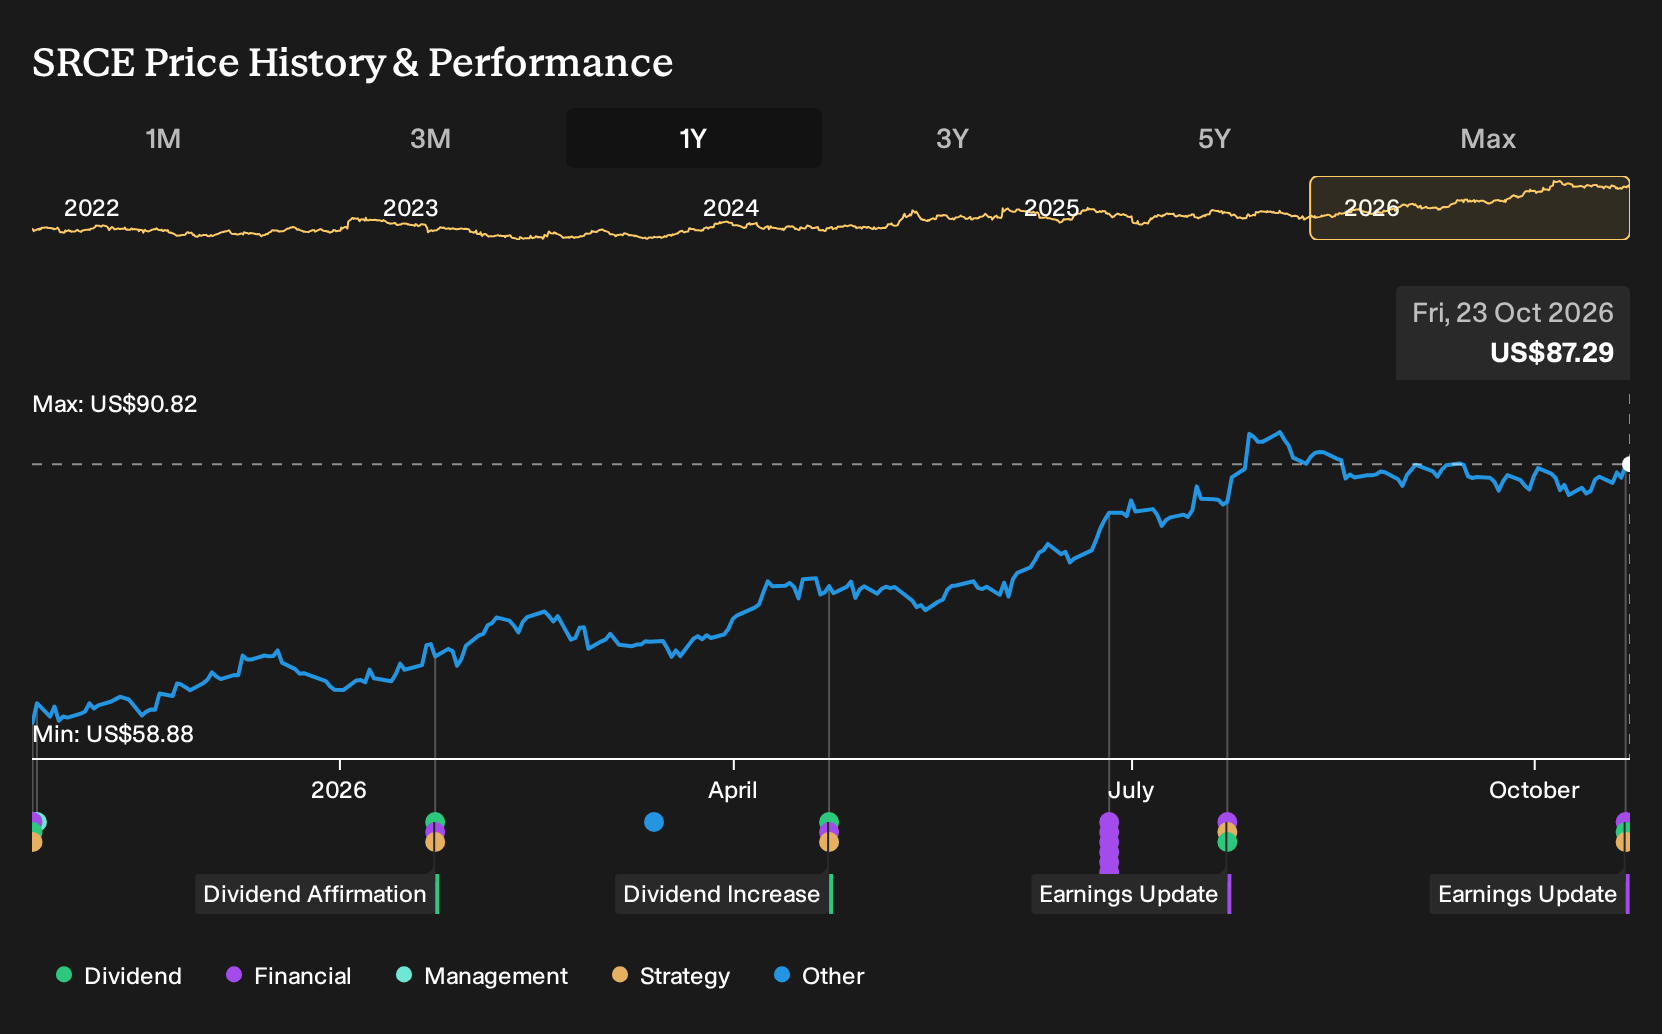
- 1st Source reported third quarter 2026 net interest income of US$95.59 million and net income of US$49.54 million, with basic and diluted earnings per share from continuing operations of US$2.03. The company also reported lower net charge offs of US$0.33 million and approved a higher quarterly dividend of US$0.45 per share for November.
- The combination of higher earnings per share, reduced credit losses, and a 12.5% dividend increase indicates that 1st Source is pairing profitability with asset quality discipline and a willingness to return more cash to shareholders.
- The next area of attention is how 1st Source's higher earnings and dividend increase may reshape the investment narrative that investors rely on.
What Is 1st Source's Investment Narrative?
To own 1st Source, you need to be comfortable with a straightforward banking story. Earnings lean heavily on net interest income, which reached US$95.59 million in the third quarter, and on keeping credit costs contained, with net charge offs at US$0.33 million. The bank still runs a capital intensive model across commercial lending, equipment finance, and aircraft leasing, so consistent credit discipline and funding access matter more than any single quarter.
The fresh data point is that 1st Source is pairing higher earnings per share with a 12.5% dividend bump, while net charge offs remain low. That combination supports the idea of a relatively resilient regional bank that can both reinvest and return cash in the near term. Short term, the key swing factors remain funding costs, credit quality, and any shift in loan demand, and this latest report mostly reinforces rather than rewrites that script.
That said, all of this strength still has to be weighed against one underappreciated pressure that sits just offstage.
There's only one way to know the right time to buy, sell or hold 1st Source. Head to Simply Wall St's company report for the latest analysis of 1st Source's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$89.67 to US$134.65 per share, which is a wide band for 1st Source. That spread shows how far opinions can diverge. When these views are considered alongside today’s earnings strength and dividend lift, there is a clear reason to explore multiple viewpoints.
Explore another 1st Source fair value estimate, including one that suggests as much as 54% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your 1st Source research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for 1st Source. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 1st Source's overall financial health at a glance.
Looking For More Investment Ideas Beyond 1st Source?
If 1st Source has sharpened your focus on earnings strength, dividends, and balance sheet quality, it can help to widen the lens and compare it with other opportunities that share similar traits.
- For readers who care most about income resilience, scan a hand picked set of 5 dividend fortresses that pair meaningful yields with fundamental support.
- If capital preservation sits higher on your list, review a curated group of 30 resilient stocks with low risk scores that score well on financial stability metrics.
- When you want to tilt toward quality that is not yet widely followed, sift through 21 high quality undiscovered gems that combine solid fundamentals with less crowding from other investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com