


Microsoft And 2 More Blue Chip Stocks To Watch
Rising interest rates are back in focus as the Federal Reserve signals a pause now but keeps the door open for further hikes. Costlier money often exposes weak balance sheets, while financially solid companies can keep funding operations on their own terms. That is where ultra resilient, low risk leaders come in. This article highlights three such stocks that can help form the bedrock of a more durable portfolio.
The three low risk leaders below are only a starting sample, while the full screen surfaced another 27 companies with equally solid balance sheets and compelling stories that are not covered here.
If you want to identify and analyze those extra opportunities with the same discipline, head straight into the Low Risk Leaders screener.
Microsoft (MSFT)
Overview: Microsoft is a global software and cloud provider whose Azure platform and Microsoft 365 subscriptions anchor long-term enterprise technology spending.
Operations: Microsoft generates about US$140b from Productivity and Business Processes, US$138b from Intelligent Cloud, and US$54b from More Personal Computing, with revenue roughly split between the United States and other countries.
Market Cap: US$3.9t
Microsoft matters in a Low Risk Leaders screen because its Azure and Microsoft 365 ecosystems tie large enterprises into multi year, subscription based relationships that can support resilience when credit costs rise.
"Microsoft just completed a fiscal year in which it earned $101.8 billion in net income. That is not a typo. One hundred and one point eight billion dollars in profit."
What those headline profits mean for future resilience depends heavily on how one unseen pressure shapes margins over the next few years.
Those pressures are already shaping how Microsoft spends and prices. This is exactly what the full narrative for Microsoft unpacks so you see where resilience and risk may be decoupling.

Spotify Technology (SPOT)
Overview: Spotify Technology runs a global audio streaming platform where users pay for Premium subscriptions or use an ad supported service for music, podcasts, and audiobooks.
Operations: Spotify Technology generates about €16.9b from Premium subscriptions and €1.9b from Ad Supported services, mainly across the United States and other international markets.
Market Cap: US$120.1b
Spotify Technology fits the Low Risk Leaders theme through its Premium tier, which brings in recurring subscription cash flows that can help smooth earnings when advertising changes through the cycle.
"Ongoing advances in AI driven personalization, including the Large Taste Model that is already associated with lifting metrics such as autoplay saves, podcast discovery and DJ engagement, point to a product that may further influence user retention and net margins as listening intensity changes."
A key question for Spotify Technology is whether one shift in how existing users are monetized can quietly reshape margins for years to come.
That quiet shift in monetization is exactly what the full narrative for Spotify Technology unpacks, revealing how AI driven engagement could accelerate both upside potential and the risk profile for Spotify Technology.

Costco Wholesale (COST)
Overview: Costco Wholesale runs membership-based warehouse clubs worldwide, using recurring membership fees and low-margin, high-volume retailing to support relatively steady cash flows.
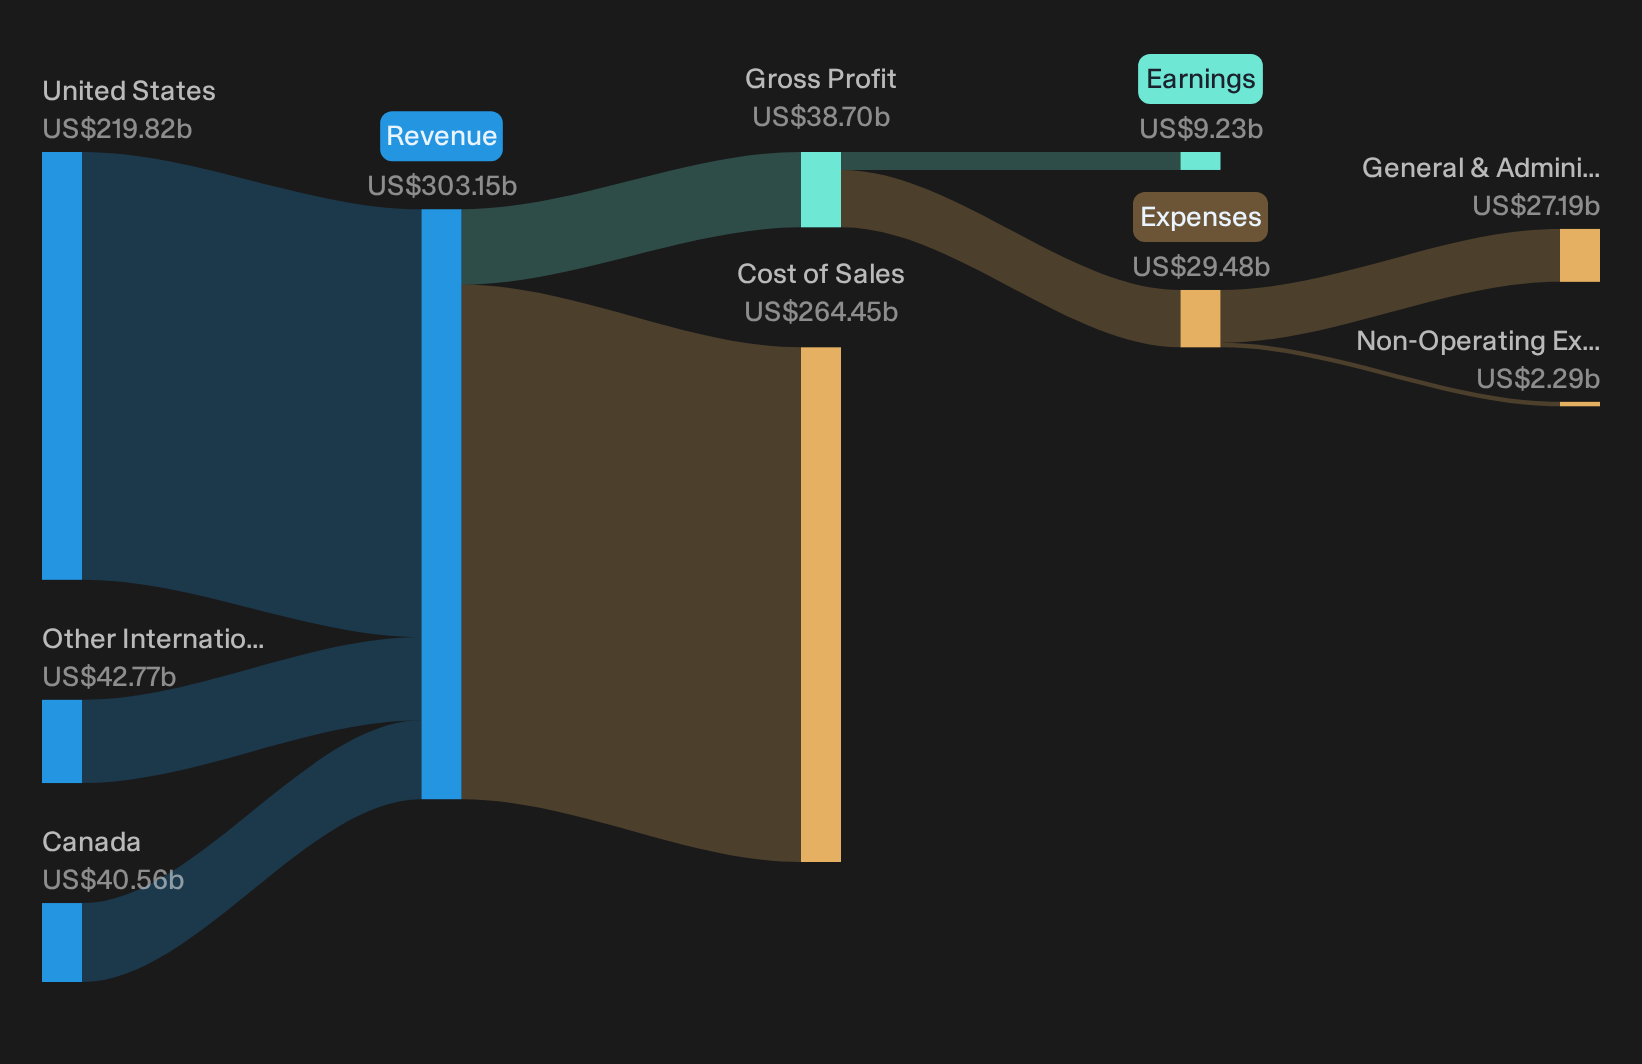
Operations: Costco Wholesale generates about US$303.2b from membership warehouses, with roughly US$219.8b in the United States, US$40.6b in Canada, and US$42.8b from other international markets.
Market Cap: US$444.6b
For a Low Risk Leaders screen, Costco Wholesale matters because recurring membership income and conservative warehouse operations help support resilient cash generation even as it invests heavily to grow.
"The modernization of the ad business and app functionality under Millerchip is a key catalyst for margin expansion in my forecast."
What happens to Costco Wholesale’s earnings power depends heavily on how one quiet shift in member engagement filters through pricing and profit margins.
That quiet shift in member engagement is exactly what the full narrative for Costco Wholesale breaks down, revealing how pricing power and margins could be quietly accelerating.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Breakout momentum, flying volumes, or quietly dropping valuations often get caught early by focused screens. Use that edge while it matters and act now.
- Spot companies with strong payouts and sturdy balance sheets before yield hunters arrive by scanning the 5 dividend fortresses curated for income resilience.
- Track under the radar operators with robust operations and clean finances using the curated 21 high quality undiscovered gems before momentum traders catch the shift.
- Position ahead of a potential infrastructure build out by reviewing the hand picked 42 power grid technology and infrastructure stocks that targets firms tied to grid upgrades and reliability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com