


Union Pacific (UNP) Could Be 11% Undervalued Following Record Quarter And 2026 Guidance
Union Pacific (UNP) just delivered record third quarter operating revenue, alongside higher intermodal volumes, improved efficiency and reaffirmed guidance for high single digit EPS growth in 2026, supported by a sizeable US$3.5b capital plan.
Union Pacific shares have climbed strongly year to date, with a 26.29% share price return and 38.06% total shareholder return over 1 year. The latest 6.97% 1 month share price gain suggests momentum is building as record results and guidance updates land alongside the CFO retirement news.
Scan how Union Pacific's latest record quarter compares with other rail and transport players by checking a curated list of solid balance sheet and fundamentals (24 results) built for this kind of earnings momentum story.
Union Pacific’s shares have already rerated on record earnings and fresh guidance, yet the stock still trades below analyst targets and an intrinsic value estimate. Does that setup leave more upside than downside from here?
Most Popular Narrative: 11% Undervalued
On the prevailing narrative, Union Pacific’s fair value of $329.88 sits above the latest $292.87 close, which puts the current rally in context and ties the upside case firmly to execution rather than hope.
The proposed merger with Norfolk Southern, including targeted annual revenue synergies of US$1.8b and cost synergies of US$1b and a plan to resume share repurchases by year 2 after closing, would materially reshape the network footprint and could lift long term earnings and cash flow if executed as outlined.
See why 92 investors see Union Pacific as 11% undervalued.
Result: Fair Value of $329.88 (UNDERVALUED)
Still, the story around Union Pacific only holds if diesel costs ease or are offset, and if the Norfolk Southern merger clears regulators without heavy concessions.
Find out about the key risks to this Union Pacific narrative.
Another View on Union Pacific’s Valuation
Union Pacific screens as undervalued on the narrative fair value of $329.88, yet the SWS DCF model points the other way. On that cash flow view, the current $292.87 price sits above an estimate of $256.79, which frames the recent rally as carrying more valuation risk than the narrative alone suggests. Which lens do you trust more when real cash flows, not stories, drive your returns?
Look into how the SWS DCF model arrives at its fair value.
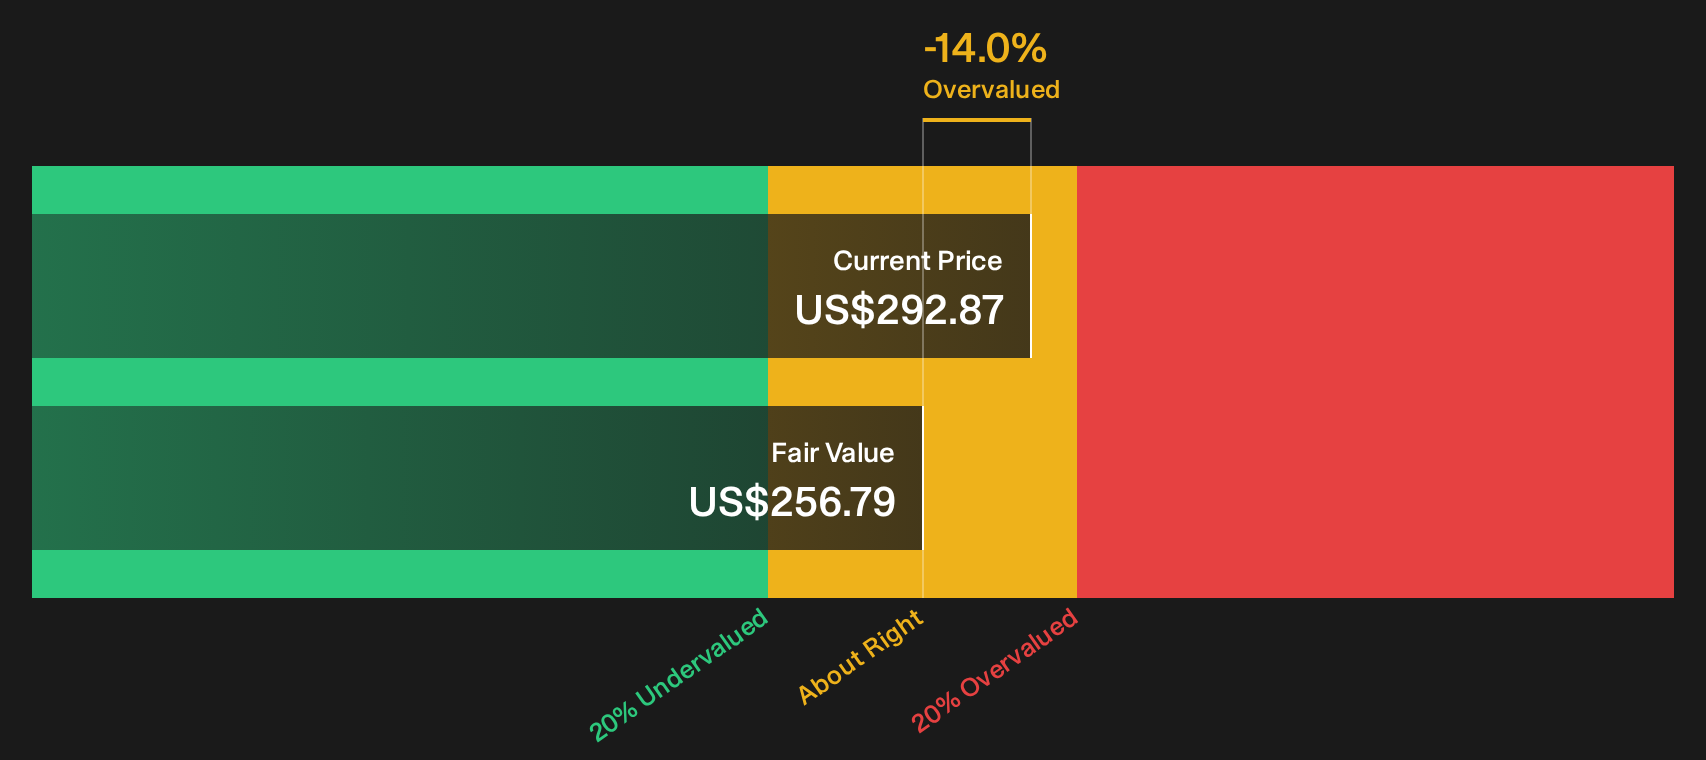
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Union Pacific for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling pulled between the bullish fair value story and the cautious DCF signal? Act while the details are fresh, review the data, and weigh the 4 key rewards and 1 important warning sign.
Looking for more Union Pacific style ideas?
If Union Pacific has sharpened your focus on pricing, returns and risk, do not stop here. Your next opportunity could already be on the Simply Wall Street Screener.
- Target steadier compounding by checking a curated mix of resilient businesses with low risk scores through the 30 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which companies currently screen as high quality undervalued through the 29 high quality undervalued stocks.
- Stack potential income on top of price returns by reviewing a focused set of companies with yields of 5% or higher in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com