


Sodexo Stock In Focus After Full Year Results And 2027 Outlook Reaffirmed
- Sodexo released its full year 2026 results, reporting flat revenue, a 3.4% underlying operating margin and a proposed €1.74 dividend per share.
- Restructuring charges compressed reported profitability, even as Q4 organic growth outpaced earlier quarters and recent European food service acquisitions expanded Sodexo's contract footprint.
- Next is a review of how Sodexo's flat annual revenue, combined with stronger Q4 organic growth, could influence the longer term investment narrative.
Sodexo Investment Narrative Recap
To own Sodexo, you need to believe the Shift & Grow 2030 plan can gradually lift organic growth and margins from today’s modest levels, even after a year of flat reported revenue and a 3.4% underlying operating margin. In the near term, the key question is whether the recent Q4 momentum and new European contracts can offset the drag from restructuring.
The biggest operational risk right now is execution. A high level of one-off restructuring, heavier transformation spending and a still thin 1.3% net margin leave little room for missteps. The latest numbers and board review do not radically change that balance, but they keep attention firmly on delivery.
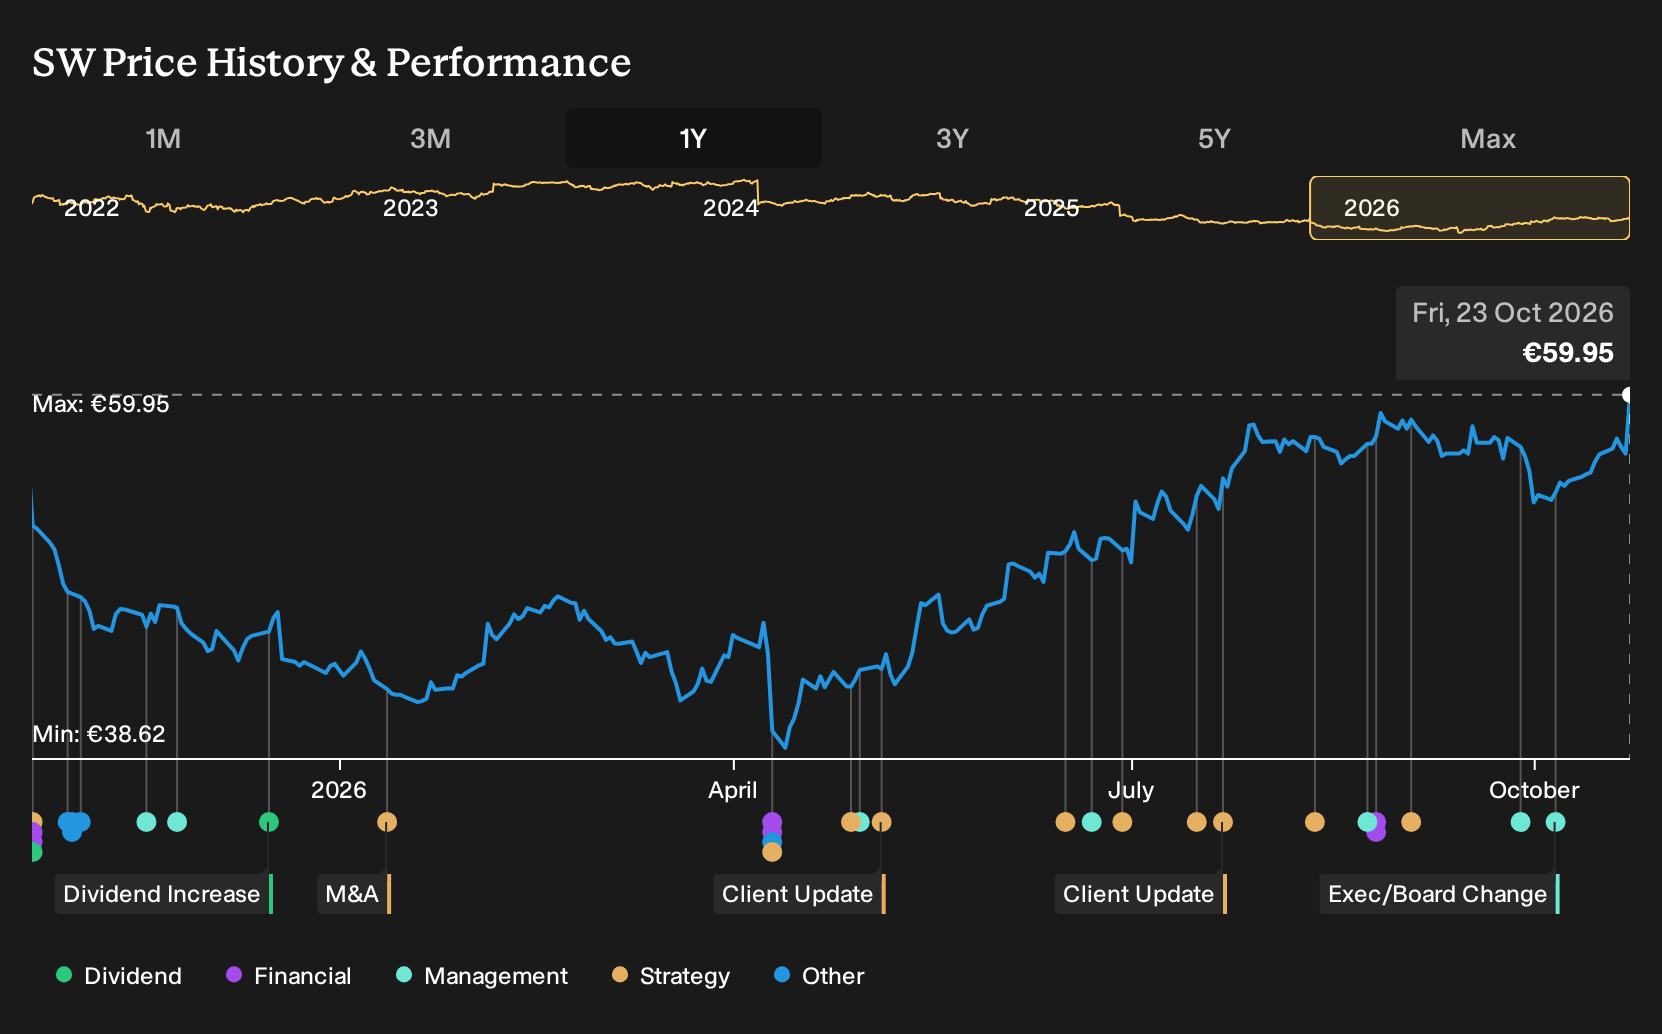
The most relevant announcement for you is the proposed €1.74 dividend per share, tied to a 50% payout of underlying net income. It offers a direct view of how Sodexo is converting a low net margin into cash returns while still funding about €1 billion of planned transformation spending and higher capital expenditure.
For potential catalysts, that payout sits alongside management’s 2030 goals for higher organic growth and an operating margin of more than 5%. If execution on productivity, procurement integration and large account wins continues to align with the 2030 plan, the dividend could remain one way to assess discipline. If margins remain compressed or debt remains elevated, that same policy could increase risk.
Sodexo's consensus narrative points to €26.6b in revenue and €608.6m in earnings by 2029, built on 3.5% yearly revenue growth and an earnings increase of about €304.6m from €304.0m today.
Uncover why Sodexo's fair value indicates a 6% potential downside to its current price, suggesting that this premium may not be sustainable.
Exploring Other Perspectives
One alternate view on Sodexo leans heavily on the digital story. The most optimistic analysts were modelling revenue of about €26.7b and earnings of roughly €664.7m by 2029, helped by Sodexo Spark and automation. With the new dividend proposal and board meeting now public, those upbeat forecasts are likely to be revisited.
Explore 3 other Sodexo fair value estimates, including one that suggests potential upside of as much as 13% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sodexo research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Sodexo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sodexo's overall financial health at a glance.
Looking for more investment ideas beyond Sodexo?
Once you have a view on Sodexo, it makes sense to widen the lens and compare it with other companies that fit different risk, income and quality profiles using the Simply Wall St Screener.
- If capital preservation is your priority, start with a basket of companies that score well on stability and risk by reviewing the 222 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and fundamentals, focus on businesses with robust finances through the list of solid balance sheet and fundamentals (205 results).
- If you want to hunt for opportunities that are less widely followed, scan a curated pool of under-the-radar candidates in the 612 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com