


BancFirst (BANF), What Is Behind The Fresh Attention?
BancFirst (BANF) is back in focus after its third quarter earnings on 21 October 2026, with higher net income, rising earnings per share and increased charge-offs drawing fresh attention to the stock.
BancFirst now trades at US$111.21, with a 7 day share price return of 2.0% and a 30 day gain of 2.3% that partly offsets a 90 day share price decline of 4.1%, while the 5 year total shareholder return of 86.98% shows the longer record that current earnings and Tulsa expansion are being measured against.
Capitalize on the renewed interest in BancFirst by comparing it with a curated 29 high quality undervalued stocks that share solid fundamentals and may be priced more conservatively than recent earnings suggest.Stronger earnings, a premium P/E and higher charge-offs now pull in different directions for BancFirst. Does that balance still reward new buyers at this price, or does it mainly benefit those already on board?
Most Popular Narrative: 11% Undervalued
BancFirst's most followed narrative points to a fair value of about $124 per share, compared with the latest close at $111.21. This frames the current debate around whether investors are being paid enough for the bank's mix of growth, quality and premium pricing.
Continued consolidation in the Tulsa market through the completed American Bank of Oklahoma integration and the planned Spirit BankCorp acquisition increases BancFirst’s branch footprint, loans and deposits in a key metropolitan area. This can support higher revenue and earnings if those assets are deployed efficiently.
See why 1 investors see BancFirst as 11% undervalued.
Result: Fair Value of $124 (UNDERVALUED)
Still, the story can change quickly if Tulsa acquisitions drag on efficiency or if BancFirst’s premium P/E multiple compresses because of slower revenue progress.
Find out about the key risks to this BancFirst narrative.
Another View: BancFirst Looks Expensive On Earnings
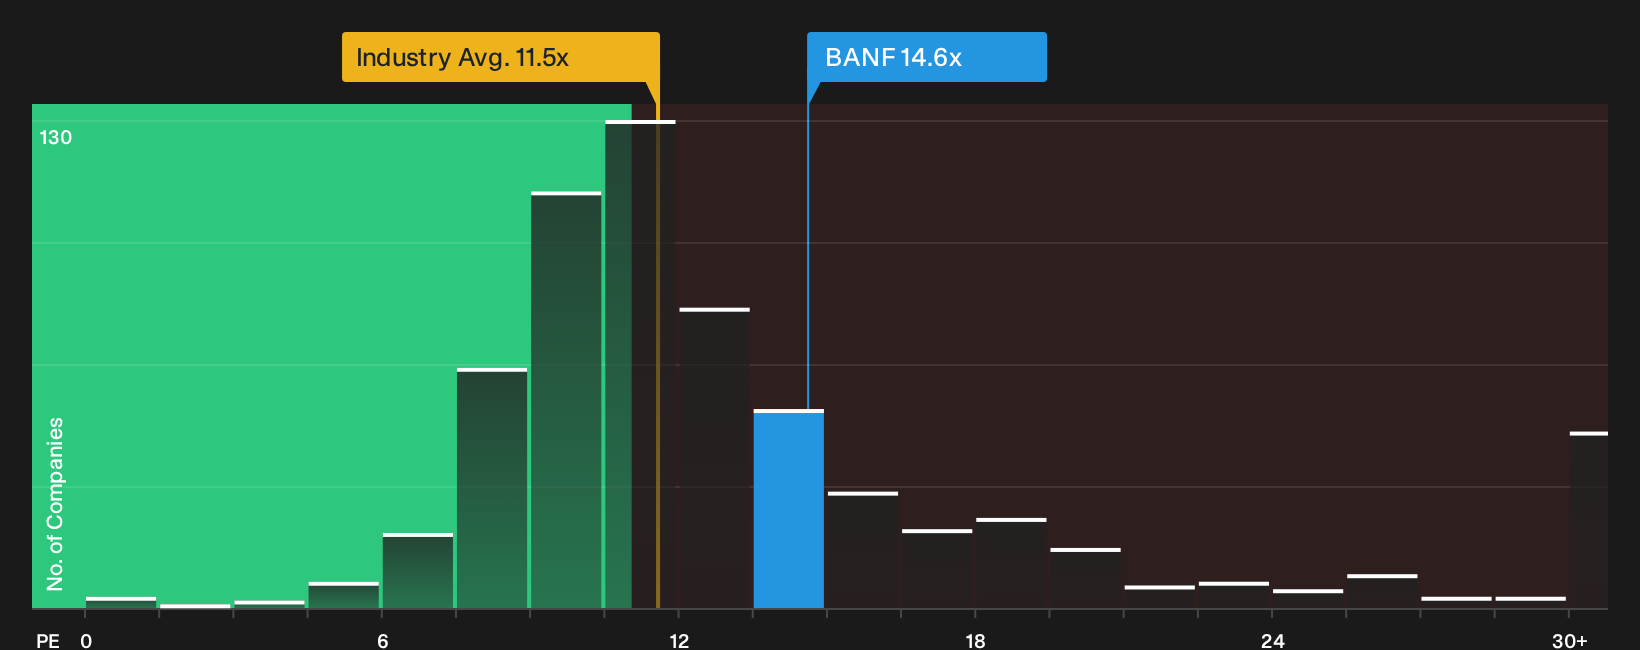
On the flip side of that fair value story, BancFirst trades on a P/E of 14.6x compared with 11.6x for the wider US Banks group and 13.4x for peers, while the fair ratio is 11.8x. That richer multiple can reward confidence or simply compress if sentiment cools.
For a deeper look at what this gap could mean over time, including where the P/E might gravitate toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around BancFirst feels finely balanced, consider reviewing the numbers yourself and testing the story. Then weigh up both sides through 4 key rewards and 1 important warning sign
Looking for more BancFirst investment ideas?
If BancFirst has your attention but you want a broader watchlist, use these focused screeners to pressure test your thinking and spot opportunities you might otherwise miss.
- Target potential upside by reviewing a 21 high quality undiscovered gems that pair strong fundamentals with relatively low investor attention.
- Prioritise sleep-at-night resilience by scanning a 30 resilient stocks with low risk scores built around sturdier balance sheets and lower overall risk scores.
- Sharpen your focus on financial strength by zeroing in on a list of solid balance sheet and fundamentals (24 results) that can better withstand tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com